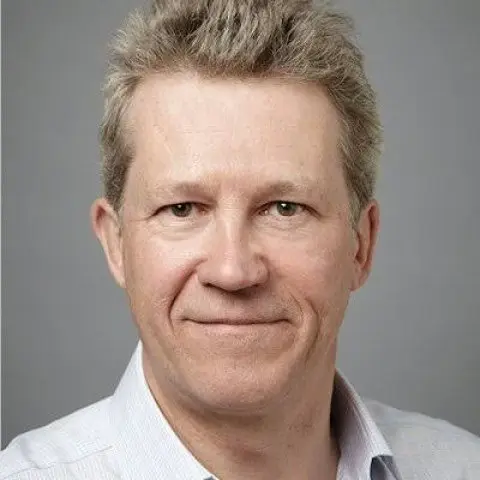
CAMBRIDGE, UK — One of the United Kingdom’s most experienced and prolific angel investors has issued a stark warning that Britain is systematically selling its most promising technology companies before they ever reach true global scale. According to industry veteran Simon Thorpe, this premature exit strategy leaves overseas acquirers and foreign investors to capture the vast majority of economic and strategic value built on British soil.
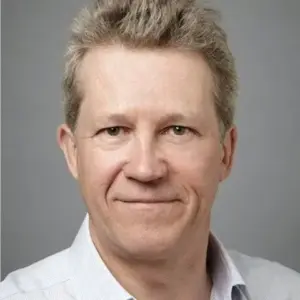
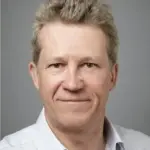
Thorpe, the founder of Delta2020 and the former chair of the prestigious Cambridge Angels, brings deep industry perspective to the debate. Over a career spanning more than 15 years, he has personally backed more than 60 early-stage UK startups. Across that portfolio, he has recorded 14 successful exits, a notable track record in the high-risk world of early-stage venture investing.
However, a closer look at those exits reveals a troubling trend for the domestic ecosystem: out of those 14 liquidity events, only a single acquisition involved a UK-based buyer. The rest were snapped up by international corporations, most notably tech giants from the United States, effectively transferring domestic intellectual property and specialized engineering talent across borders long before the companies could mature into independent British anchors of the global technology landscape.
Thorpe highlighted these concerns during a comprehensive interview on the latest episode of SyndicateRoom’s Angel Insights podcast, hosted by Tom Britton. Addressing the structural challenges facing the nation’s innovation economy, Thorpe did not mince words regarding the current lifecycle of British startups.
"Sadly, yes, we are selling our companies too early," Thorpe told listeners during the podcast. "We are good at startups in the UK. We’re not so good at scale-ups."
Value Built in Britain, Captured Elsewhere
The mechanics behind these early acquisitions often bypass traditional financial metrics like near-term revenue. Instead, foreign buyers frequently target UK firms for their underlying human capital, specialized technological breakthroughs, and advanced intellectual property. These overseas entities recognize high-value engineering talent and proprietary research that can be integrated into massive global operations at a fraction of the cost required to develop it internally.
Thorpe pointed to specific, high-profile historical examples from his own investment career to illustrate the dynamic. When Apple acquired Spectral Edge in 2019—a Cambridge-originated image-processing company that specialized in computational photography and which Thorpe had personally backed—the iPhone maker was not buying a massive balance sheet or a sprawling commercial sales force.
"They wanted the technology and the people," Thorpe explained, emphasizing how foreign corporations routinely absorb the foundational genius of British research and development hubs to fuel their own offshore product pipelines.
This structural shortfall is not confined strictly to the exit market; it plagues the growth-funding pipeline as well. Scale-up capital remains notoriously difficult to secure in quantities comparable to the United States or parts of Asia. Consequently, promising British enterprises are frequently forced to look abroad for the substantial capital injections required to fund international expansion and R&D at scale.
A prime example of this ongoing trend can be seen in Quantexa, a prominent London-headquartered data analytics and decision intelligence company. As one of the largest holdings in the portfolio of venture capital firm AlbionVC, Quantexa successfully secured a massive $175 million Series F funding round. However, the round was led not by domestic financial institutions, but by the venture arm of the Ontario Teachers’ Pension Plan, a Canadian institutional giant.
This reliance on foreign institutional capital raises pressing economic questions for the UK financial sector. "Why isn’t it a UK pension fund that’s investing in that company?" Thorpe asked, pointing to a persistent disconnect between domestic capital pools and domestic high-growth technology champions.
Thorpe acknowledges that recent policy initiatives, such as the Mansion House pension reforms designed to unlock capital from institutional retirement pots and direct it toward venture capital and private equity, represent a step in the right direction. Nevertheless, he warns that the implementation timetable is far too slow to address the immediate needs of today’s scale-ups. Furthermore, decades of conservative, income-focused investment strategies mean that UK pension funds currently lack the specialized in-house expertise required to properly evaluate, diligence, and manage high-risk, high-reward growth technology companies.
The Case for "Replacement Capital" and Broader Ambition
Until domestic institutional money matures and flows freely into the UK tech sector, Thorpe argues that the ecosystem urgently requires alternative financial mechanisms. Specifically, the market needs more sources of specialized "replacement capital" capable of buying out early-stage angel investors and providing the substantial liquidity needed to fund subsequent phases of growth. Without such mechanisms, a trade sale to an overseas buyer remains the default and often only viable exit route for founders and early backers looking to realize returns.
The conversation around funding also extends into matters of national sovereignty and industrial ambition, particularly within critical, future-defining sectors such as artificial intelligence and advanced semiconductors. Thorpe drew a sharp comparison between the UK government’s 2023 commitment of £1 billion over a decade to support the domestic semiconductor industry and the monumental $52 billion allocated by the United States under the CHIPS Act.
Contrasting these two figures, Thorpe asserted that the correct funding figure for the UK in the global technology race is "certainly more than a billion. And we are not ambitious enough." He suggested that instead of attempting to outspend superpowers unilaterally, Britain should forge strategic partnerships with major European economies, pooling resources and focusing relentlessly on areas of genuine domestic research and engineering strength.
Within this broader framework, Thorpe views angel investors not as the final architects of massive global corporations, but as the indispensable scouts of the financial system.
"They are seeking out these great little nuggets of great people and great tech, and helping them get on the ladder… and pass the baton on to institutional funding," Thorpe said.
Tom Britton, co-founder of SyndicateRoom and the host of the Angel Insights podcast, underscored Thorpe’s observations by highlighting how individual track records reflect systemic national hurdles.
"Simon’s record makes the point better than any statistic: when British companies sell, they mostly sell abroad," Britton said. "Exits are good news for founders and investors. What the UK needs is enough capital in the room that founders get a real choice about when to sell."
 FinTech News
 FinTech News
 FinTech News