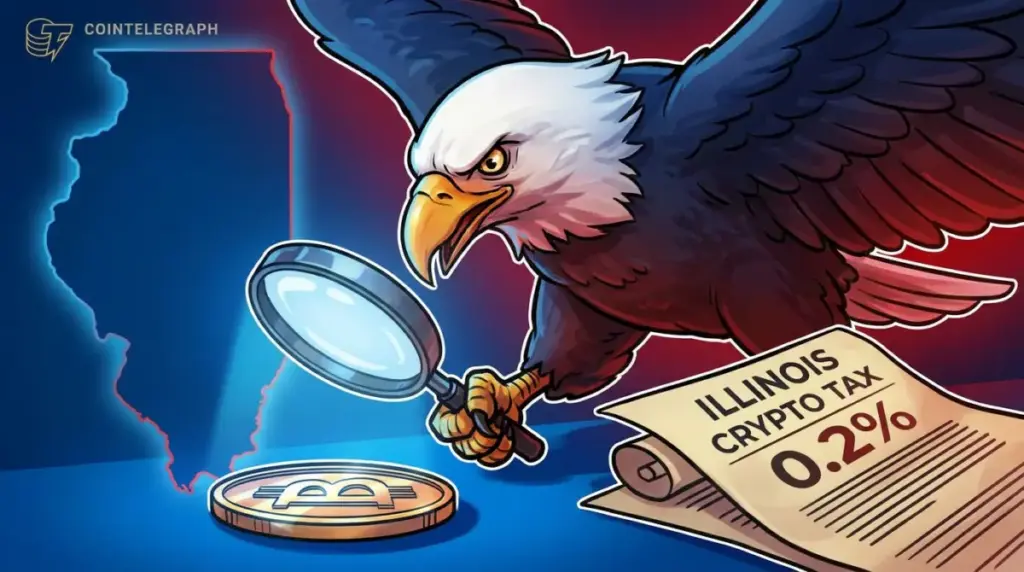
An unprecedented coalition spanning the United States Department of Justice, major business and financial industry groups, and leading decentralized finance (DeFi) firms has thrown its full weight behind a high-stakes legal challenge. Together, these entities are targeting Illinois’ controversial 0.2% digital asset tax, arguing that the legislative measure unfairly singles out cryptocurrency transactions and threatens to impose heavy tax burdens even on investors who suffer financial losses.
Over the course of a critical week, the legal landscape surrounding the dispute shifted dramatically. The US Department of Justice formally weighed in by filing a statement of interest, while heavy-hitting traditional financial and commercial advocates—including the US Chamber of Commerce and the Securities Industry and Financial Markets Association (SIFMA)—submitted a joint amicus curiae filing. Simultaneously, a powerful coalition of prominent venture capital firms and crypto protocols, featuring Andreessen Horowitz, Paradigm, Uniswap, and Aave Labs, submitted their own detailed brief, according to a joint announcement released on Thursday by the Blockchain Association and the Crypto Council for Innovation.
At the center of the controversy is a state law enacted in June that imposes a broad 0.2% tax on the total value of digital assets whenever they are exchanged, transferred, or stored. Crucially, this levy applies regardless of whether an individual transaction generates an actual economic profit or results in a loss.
The battle lines in federal court were drawn earlier this year. The Digital Chamber initiated the legal offensive by filing a lawsuit against Illinois Attorney General Kwame Raoul and state revenue official David Harris in July. That challenge was quickly followed by a separate, coordinated lawsuit filed in August by the Blockchain Association and the Crypto Council for Innovation. Originally designed to take effect at the start of the year on January 1, the implementation of the tax was subsequently postponed to July 1, 2027. This delay provided crucial breathing room, allowing the ongoing legal challenges and mounting opposition to proceed through the court system without immediate enforcement against market participants.
When the tax was first conceptualized and advanced through the state legislature, Illinois officials projected that the digital asset levy would generate approximately $60 million in revenue for the state’s 2027 fiscal year, according to figures released by the governor’s budget office. Illinois House Speaker Emanuel “Chris” Welch had previously championed the measure as a key component of a broader affordability agenda. Proponents framed the tax as a necessary step toward closing corporate loopholes and ensuring that large technology companies and prominent cryptocurrency investors pay what lawmakers described as their fair share. Despite the growing legal pressure and widespread industry outcry, lawmakers involved in crafting the legislation and the governor’s office did not respond to requests for comment before publication.
Business groups warn of crypto tax costs and legal violations
As the litigation moves forward, traditional financial institutions and commercial advocacy groups are sounding the alarm over the practical and legal implications of the state law. In a detailed court filing submitted on November 6, SIFMA and the US Chamber of Commerce warned that the Illinois digital asset tax would inevitably ripple far beyond the borders of the state, directly affecting commercial banks, broker-dealers, asset custodians, and financial asset managers operating nationwide. They cautioned that the measure would expose these entities to immense, unprecedented compliance costs while imposing an unconscionable financial burden on everyday customers and institutional investors alike.
The business groups highlighted the inherent economic absurdity of a transaction tax untethered from realized gains. Pointing to the mechanics of the law, the filing noted that a customer who loses money on a trade ultimately owes the exact same tax liability as a customer who successfully earns a profit. Furthermore, the organizations emphasized that moving the exact same digital asset between two separate accounts or wallets could trigger multiple tax liabilities at both ends, all without an actual sale taking place, a realized financial gain being recorded, or any underlying change in beneficial ownership.
To comply with such a mandate, financial firms would be forced to engineer entirely new, costly technological systems capable of identifying residency for Illinois-based customers, continuously valuing complex digital assets, and accurately determining which specific network interactions cross the threshold into taxable events. All of this would have to be achieved under the threat of potential criminal penalties for compliance failures.
Beyond logistical nightmares, the industry groups argued that the tax represents a form of unconstitutional discrimination against digital asset services. They pointed out that comparable, high-frequency transactions involving traditional financial assets and securities are not subjected to a similar tax structure. Consequently, the measure potentially violates federal internet tax protections as well as fundamental constitutional requirements governing interstate commerce and uniform state taxation.
DOJ challenges tax policy as DeFi firms warn of developer liability
The federal government has also stepped into the legal fray to challenge the state-level initiative. On November 6, the US Department of Justice filed its statement of interest, asserting that Illinois’ digital asset tax actively undermines broader federal policy objectives. Specifically, the DOJ argued that the tax conflicts with federal efforts to foster cryptocurrency innovation and secure long-term United States leadership in the rapidly evolving digital economy.
The federal filing drew direct attention to recent national initiatives, such as the conceptualization of a Strategic Bitcoin Reserve and the passage of the GENIUS Act, which established a comprehensive federal regulatory framework for stablecoins. The Justice Department maintained that imposing punitive or less favorable tax treatments on digital assets at the state level directly contradicts and obstructs these overarching national priorities.
In parallel with the federal and institutional pushback, the decentralized finance sector has raised distinct and urgent concerns regarding who might ultimately be held legally responsible for collecting and remitting the tax. In a separate amicus brief filed on November 11 by a dedicated DeFi education and defense coalition, industry representatives argued that the enforcement mechanisms envisioned by Illinois could effectively impose impossible compliance obligations on software developers, node operators, and other decentralized blockchain participants. These participants characteristically lack access to sensitive customer information, exercise no direct control over user funds, and possess no administrative mechanism to collect or remit state taxes.
 Crypto Regulation & Policy
 Crypto Regulation & Policy
 Crypto Regulation & Policy