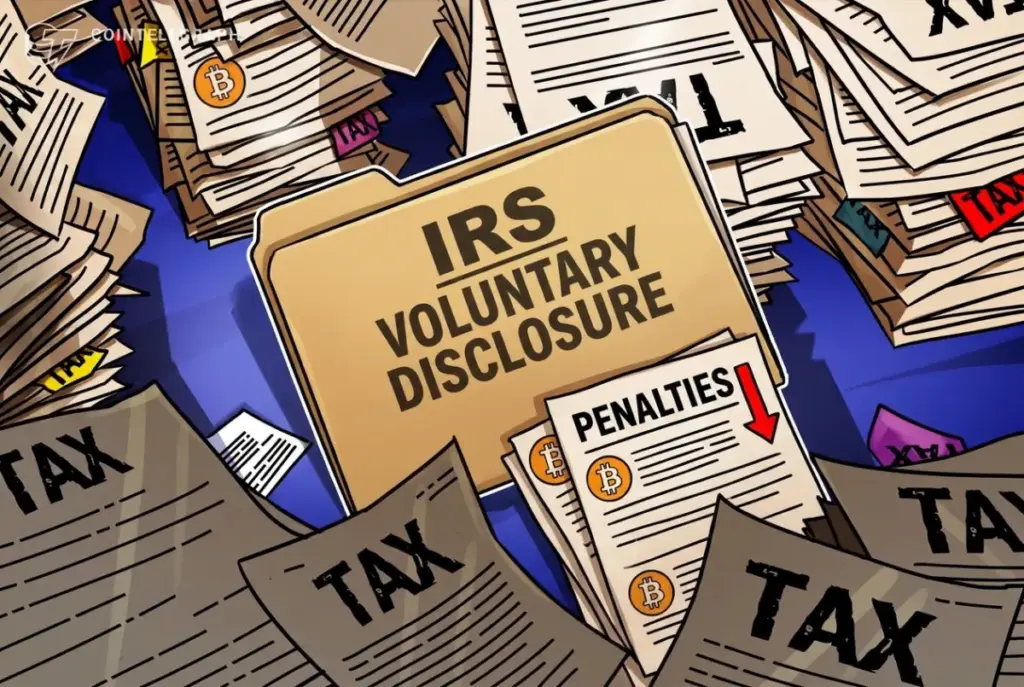
The United States Internal Revenue Service is currently preparing a comprehensive overhaul of its voluntary disclosure program, introducing strategic plans designed to significantly reduce financial penalties and accelerate the overall resolution timeline for tax violations. According to a report published by Forbes, this major administrative shift will encompass a wide array of noncompliance issues, including those involving complex digital assets and cryptocurrencies.
Speaking at the recent UCLA Extension Tax Controversy Conference, IRS Criminal Investigation Chief Jarod Koopman outlined the agency’s ambitious timeline, revealing that officials aim to formally introduce the newly revised program before the month of December. A cornerstone of the upcoming changes is a strict target resolution window, with the agency planning to close and resolve cases within a mere 120 days from the exact date that taxpayers successfully complete the required submission process.
This dramatic compression of the timeline marks a stark departure from the current administrative framework. Under the existing voluntary disclosure program, taxpayers frequently find themselves navigating a protracted process that can stretch out for a year or even longer before reaching a final resolution with federal authorities. By streamlining these procedures, the IRS hopes to encourage a higher volume of noncompliant individuals to step forward voluntarily, clearing up backlogs and bringing past tax liabilities into good standing much more efficiently.
Despite the growing prominence of digital assets in tax enforcement, the forthcoming overhaul will reportedly not establish a standalone or separate disclosure process specifically tailored for cryptocurrencies and other digital tokens. Koopman clarified to conference attendees that the agency intends to handle digital asset infractions through the exact same voluntary disclosure procedures that are routinely applied to more traditional forms of tax noncompliance, such as foreign bank accounts, hidden offshore income, and domestic reporting omissions.
Furthermore, the IRS official indicated that the financial penalties enforced under the revised program will be substantially lower than those currently levied against delinquent taxpayers. While Koopman deliberately refrained from providing exact figures or specific percentage reductions during his presentation, he noted that the agency is actively exploring flexible mechanisms to ease the financial burden of compliance. Among the options being considered, the IRS may allow taxpayers to settle their outstanding liabilities through structured installment plans or formal offers in compromise, providing a more manageable path forward for individuals who might otherwise struggle to pay their lump-sum tax debts.
To fully understand the significance of this upcoming IRS administrative shift, it is helpful to examine the specific target audience for the agency’s existing voluntary disclosure framework. The current iteration of the IRS voluntary disclosure program is specifically intended for taxpayers whose willful failure to comply with federal tax laws exposes them to the severe risk of criminal prosecution. It is explicitly not designed for individuals who merely made unintentional reporting errors, mathematical mistakes, or simple misunderstandings on their annual tax filings. For willful violators, coming forward voluntarily has historically been viewed as a crucial step to mitigate the threat of criminal charges, though it has traditionally come with heavy civil fraud penalties and exhaustive investigative delays.
While the IRS moves forward with its internal administrative reforms to address willful noncompliance and general tax violations, federal lawmakers on Capitol Hill are simultaneously considering a separate legislative voluntary disclosure program. This congressional initiative is specifically aimed at a different demographic: crypto taxpayers, including individuals who made honest, unintentional reporting errors regarding their digital asset transactions.
This legislative effort is embodied in Section 502 of the proposed Digital Asset Tax Certainty Act. Unlike the broad administrative program managed by the IRS, the proposed bill would establish a distinct, specialized process allowing taxpayers to correct past reporting violations under clearly defined and predictable penalties. The legislative push acknowledges the immense complexity and evolving nature of cryptocurrency tax law, which has left many retail investors and casual traders uncertain about how to properly report complex transactions like decentralized finance yields, non-fungible token trades, and airdrops. The Digital Asset Tax Certainty Act successfully cleared a notable legislative hurdle when it was approved by the House Ways and Means Committee, signaling growing bipartisan interest in establishing clearer pathways for cryptocurrency tax compliance as the federal government continues to ramp up its oversight of the digital economy.
 Crypto Regulation & Policy
 Crypto Regulation & Policy
 Crypto Regulation & Policy