Luxor’s Monthly Lookback Series for September 2026 reveals a unique tug-of-war in the Bitcoin mining economy, where rising asset prices and climbing network difficulty effectively neutralized one another. Following an explosive August rally that added $7.70 to the hashprice in just twelve days, September brought a combination of continuing Bitcoin momentum and increased network competition. Ultimately, spot hashprice finished the month almost precisely where it began, closing within a dollar of its opening mark while market participants navigated shifting macroeconomic conditions, regulatory hurdles, and the official end of the Texas summer cooling season.
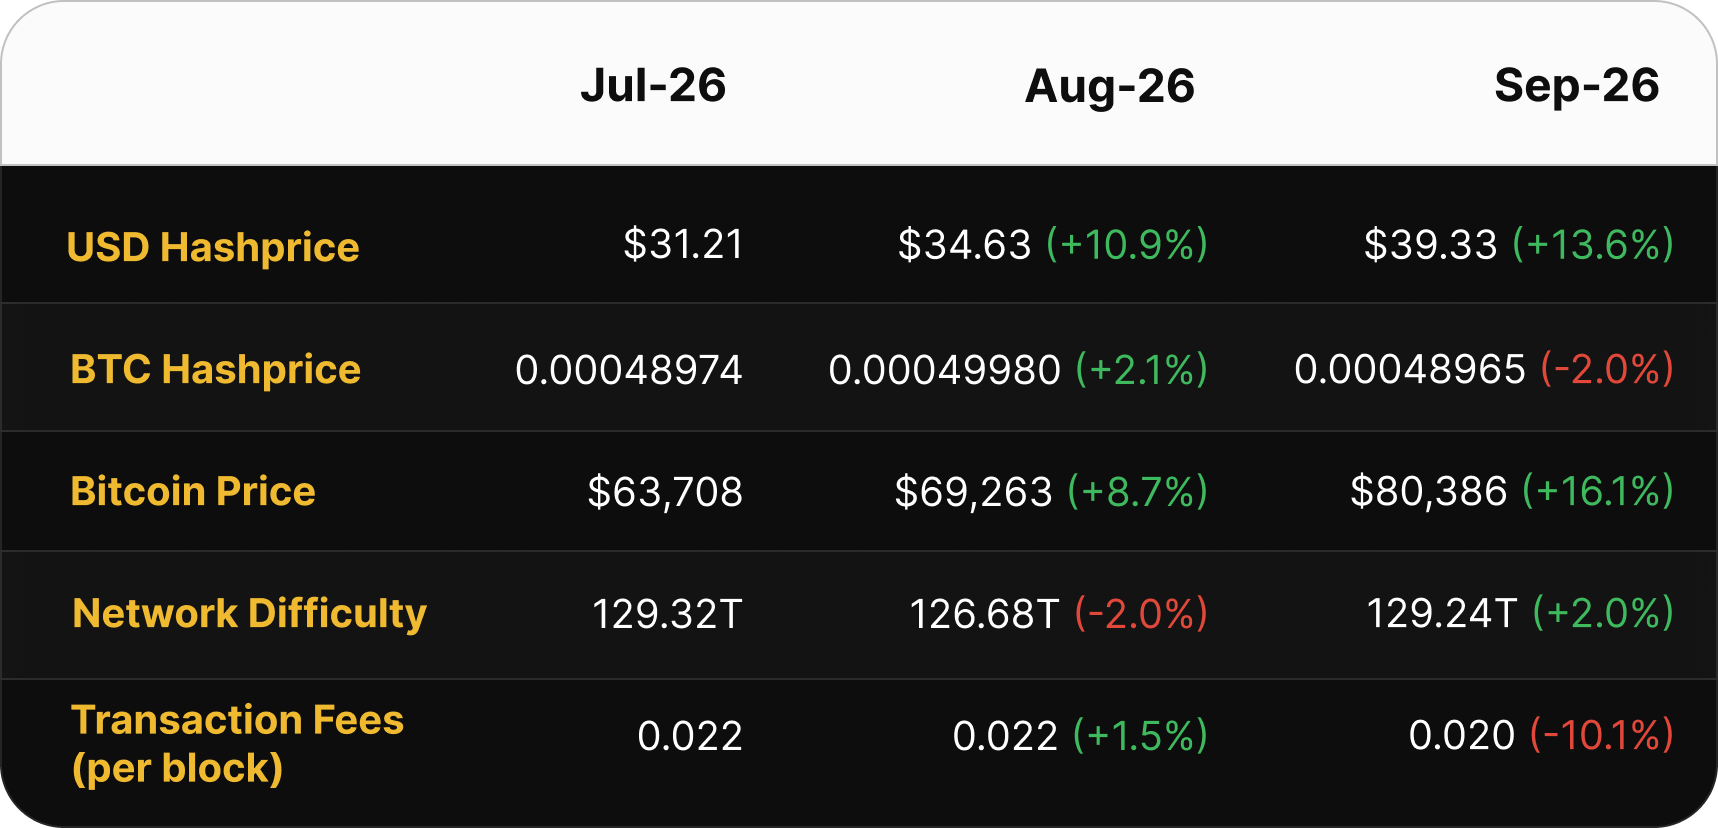
September 2026 Spot Hashprice and Its Constituents
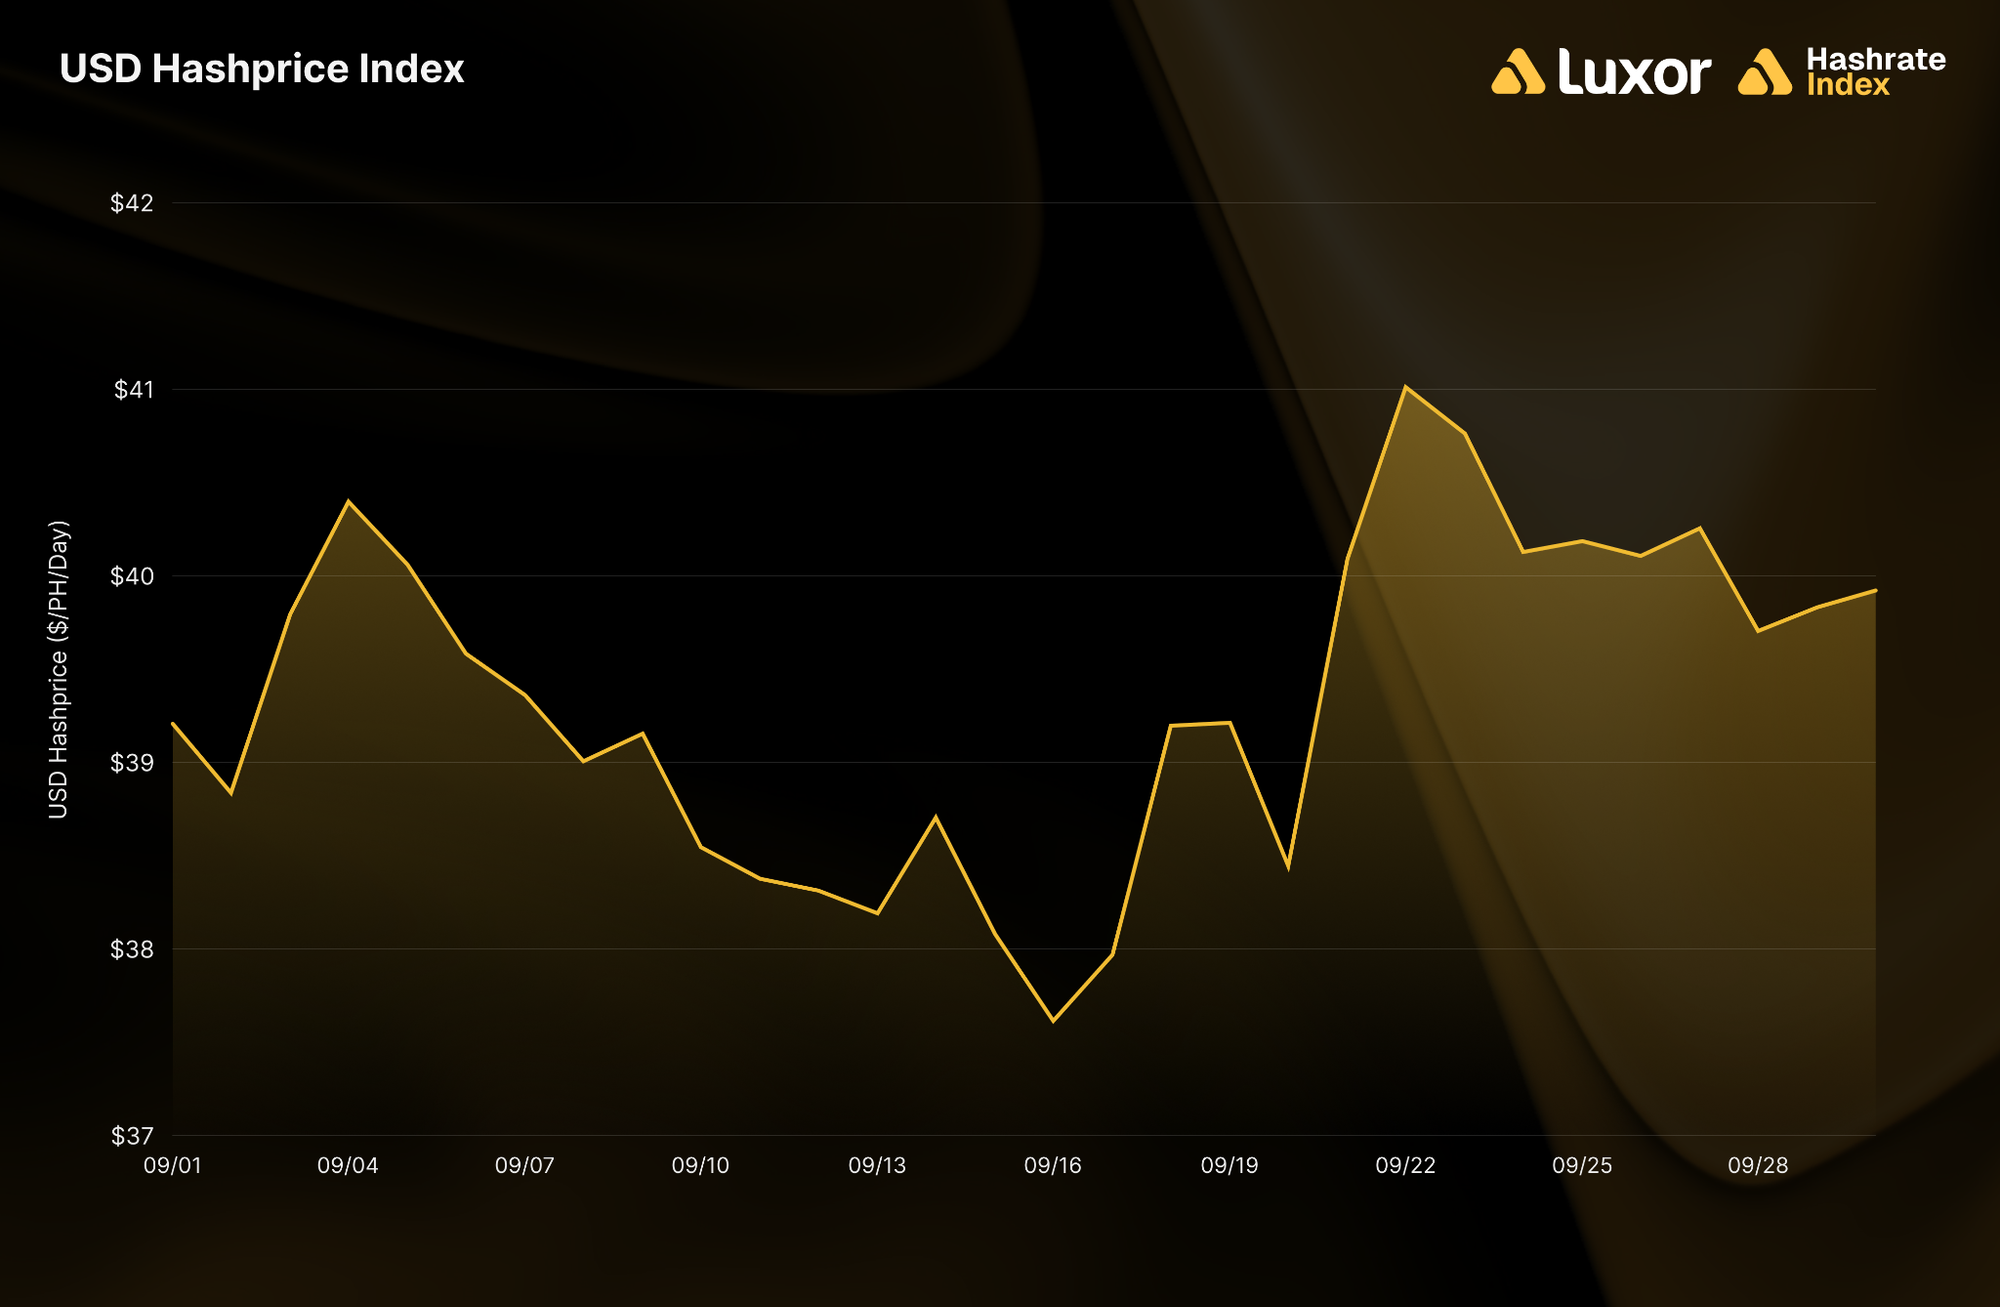
The broader economic backdrop for Bitcoin miners in September was defined by a steady resilience in USD hashprice, which managed to hold onto the substantial ground captured during August. Opening the month at $39.21 per PH/s/day, USD hashprice drifted upward by 1.8% to close at $39.92. Over the course of the month, the metric averaged $39.33, marking the highest monthly average recorded since January. Furthermore, miners experienced nine individual days where hashprice settled above the $40 threshold—the highest frequency of days above that level since November 2025, contrasting sharply with just a single day above $40 observed throughout August.
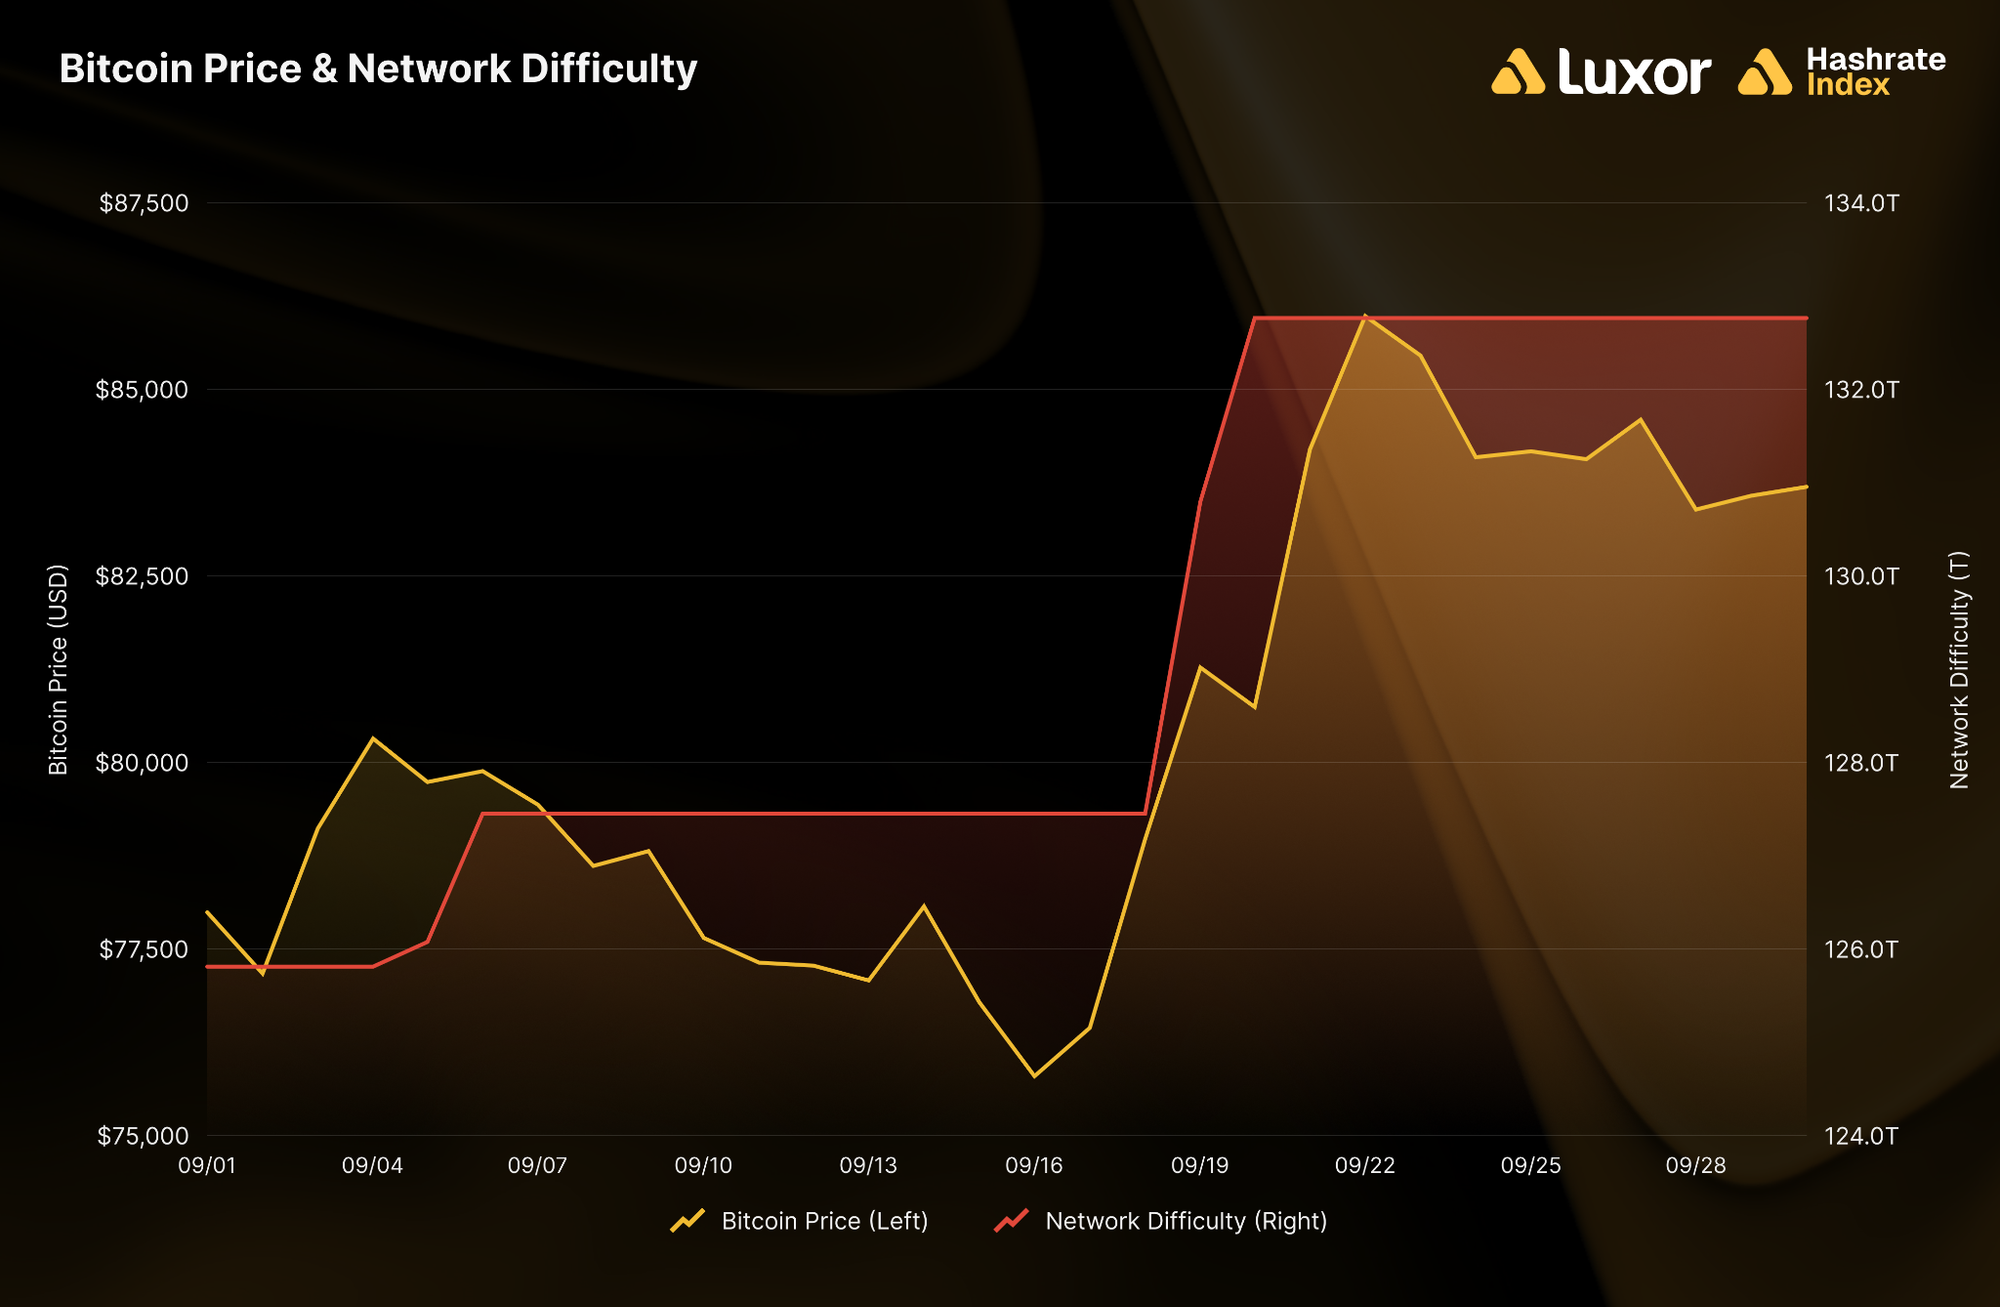
Trading ranges remained relatively narrow by historical standards. The lowest point of the month was registered on September 16 at $37.61, while the monthly high reached $41.01 six days later on September 22. Beneath these headline figures, the underlying mechanics of hashprice demonstrated a balanced push and pull: appreciation in the price of Bitcoin exerted upward pressure, while concurrent jumps in network difficulty pulled returns back down in nearly equal measure.
Bitcoin Price Performance: Regulatory Setbacks Followed by Institutional Surges
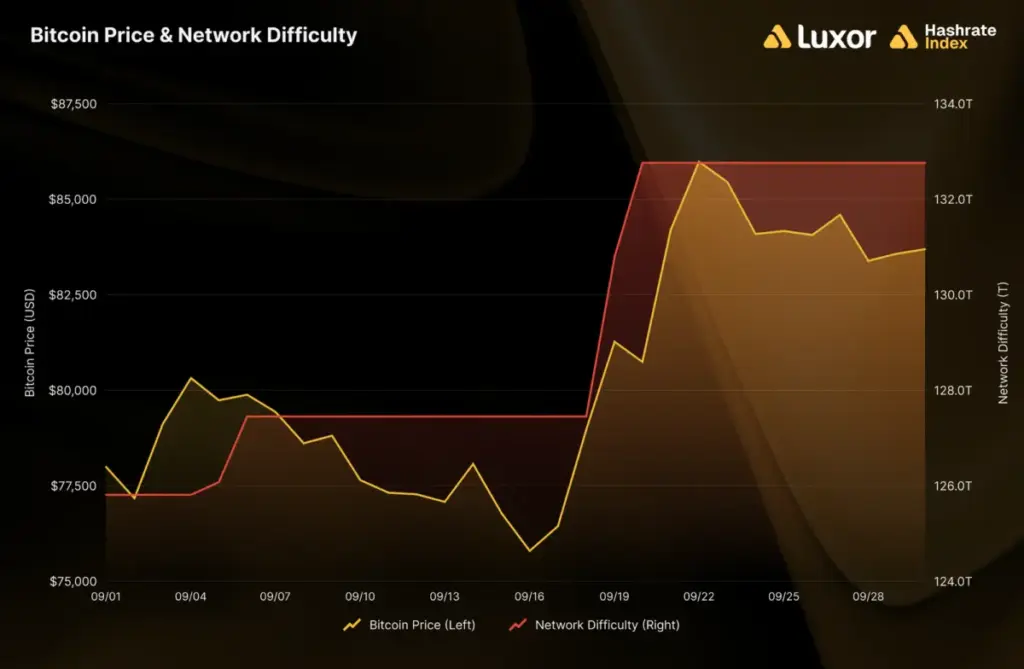
Bitcoin itself charted a volatile path through September, opening the month at $77,984 and ultimately closing at $83,687 for a 7.3% gain. On a month-over-month basis, the average price of Bitcoin rose 16.1% to $80,386, hitting a monthly high of $85,973 on September 22.
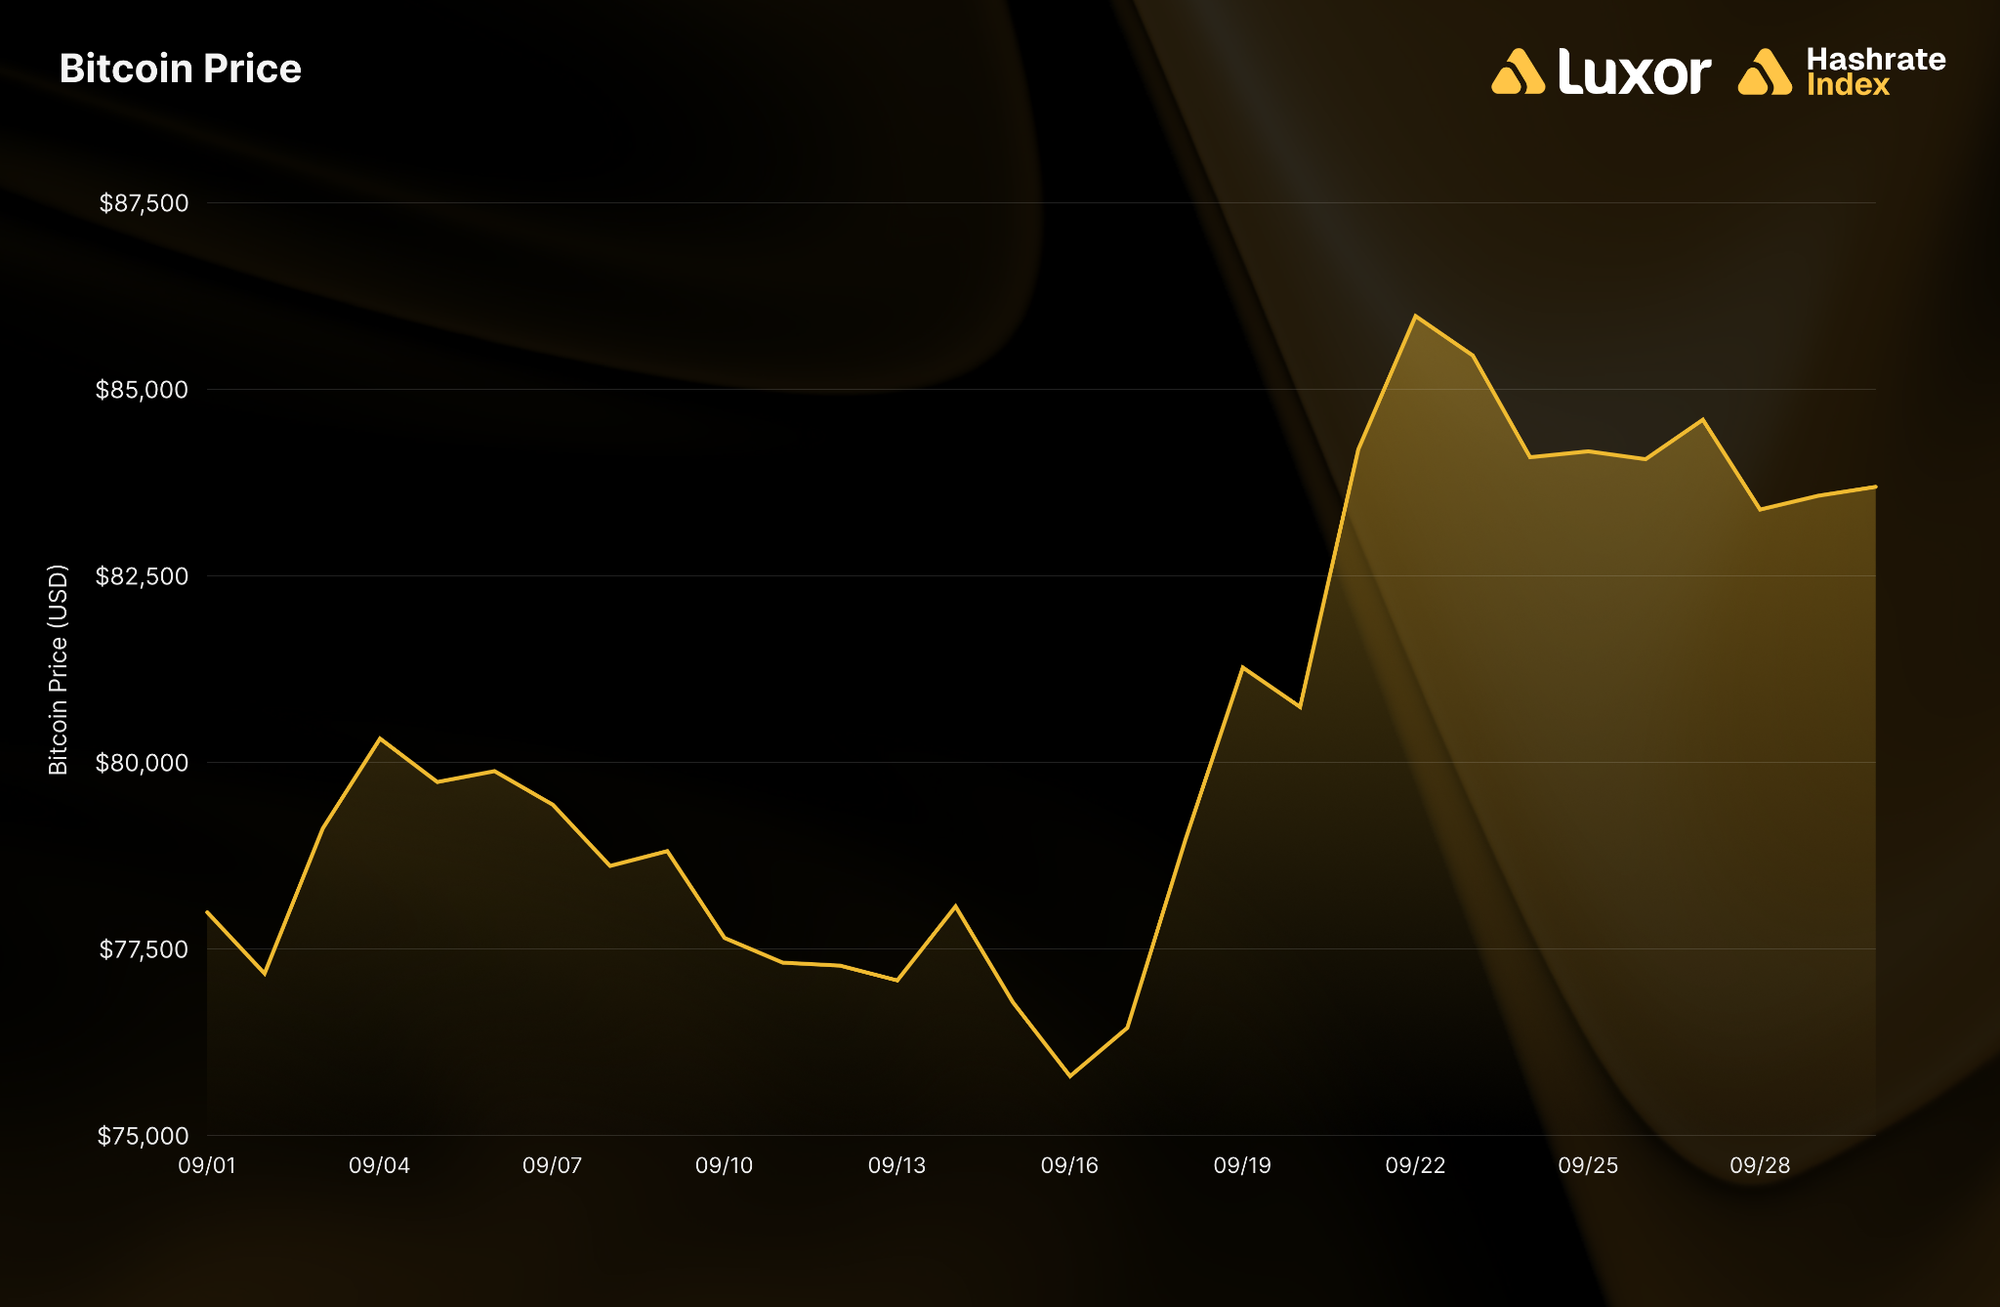
The month was punctuated by two significant scheduled risks that landed within a 24-hour window mid-month. On September 15, the United States Senate failed to invoke cloture on the Clarity Act, falling short with 41 votes against the measure and effectively stalling the legislation for the remainder of 2026. The following day, the Federal Open Market Committee (FOMC) unanimously voted to raise interest rates by 25 basis points to a range of 3.75% to 4.00%, marking the central bank’s first rate hike since July 2023. These back-to-back developments coincided with Bitcoin’s monthly low of $75,791 on September 16.
Despite this pressure, the market rebounded sharply. Between September 16 and September 22, Bitcoin surged 13.4% to reach $85,973, marking its largest six-day advance since the August breakout. This rally was fueled by massive institutional inflows into US spot exchange-traded funds, which absorbed $999 million on September 21 alone—the largest single-day inflow of the year and the highest since October 2025. Total net inflows for the month reached $2.65 billion, pushing 2026 net flows back into positive territory and lifting the average US spot-ETF holder back into profitability for the first time since January, according to Bloomberg Intelligence estimates.
At its closing price of $83,687, Bitcoin stood 32.8% below its all-time high of $124,485 recorded on October 6, 2025, an improvement from the 37.1% discount observed at the end of August. It remained 13.1% below its 2026 peak of $96,278 achieved on January 15. For the third quarter as a whole, Bitcoin posted a 41.8% gain, representing its strongest quarterly performance since the final quarter of 2024.
Network Difficulty and Hashrate Growth
Network difficulty mirrored Bitcoin’s underlying expansion, averaging 129.24T for a 2.0% increase and closing the month at 132.76T. Two upward adjustments took place during the month: a 1.31% increase on September 5, followed by a 4.16% surge on September 19, which marked the largest single retarget adjustment since late June. With a cumulative net gain of 5.52% across both adjustments, September witnessed the most substantial month of difficulty growth since October 2025.
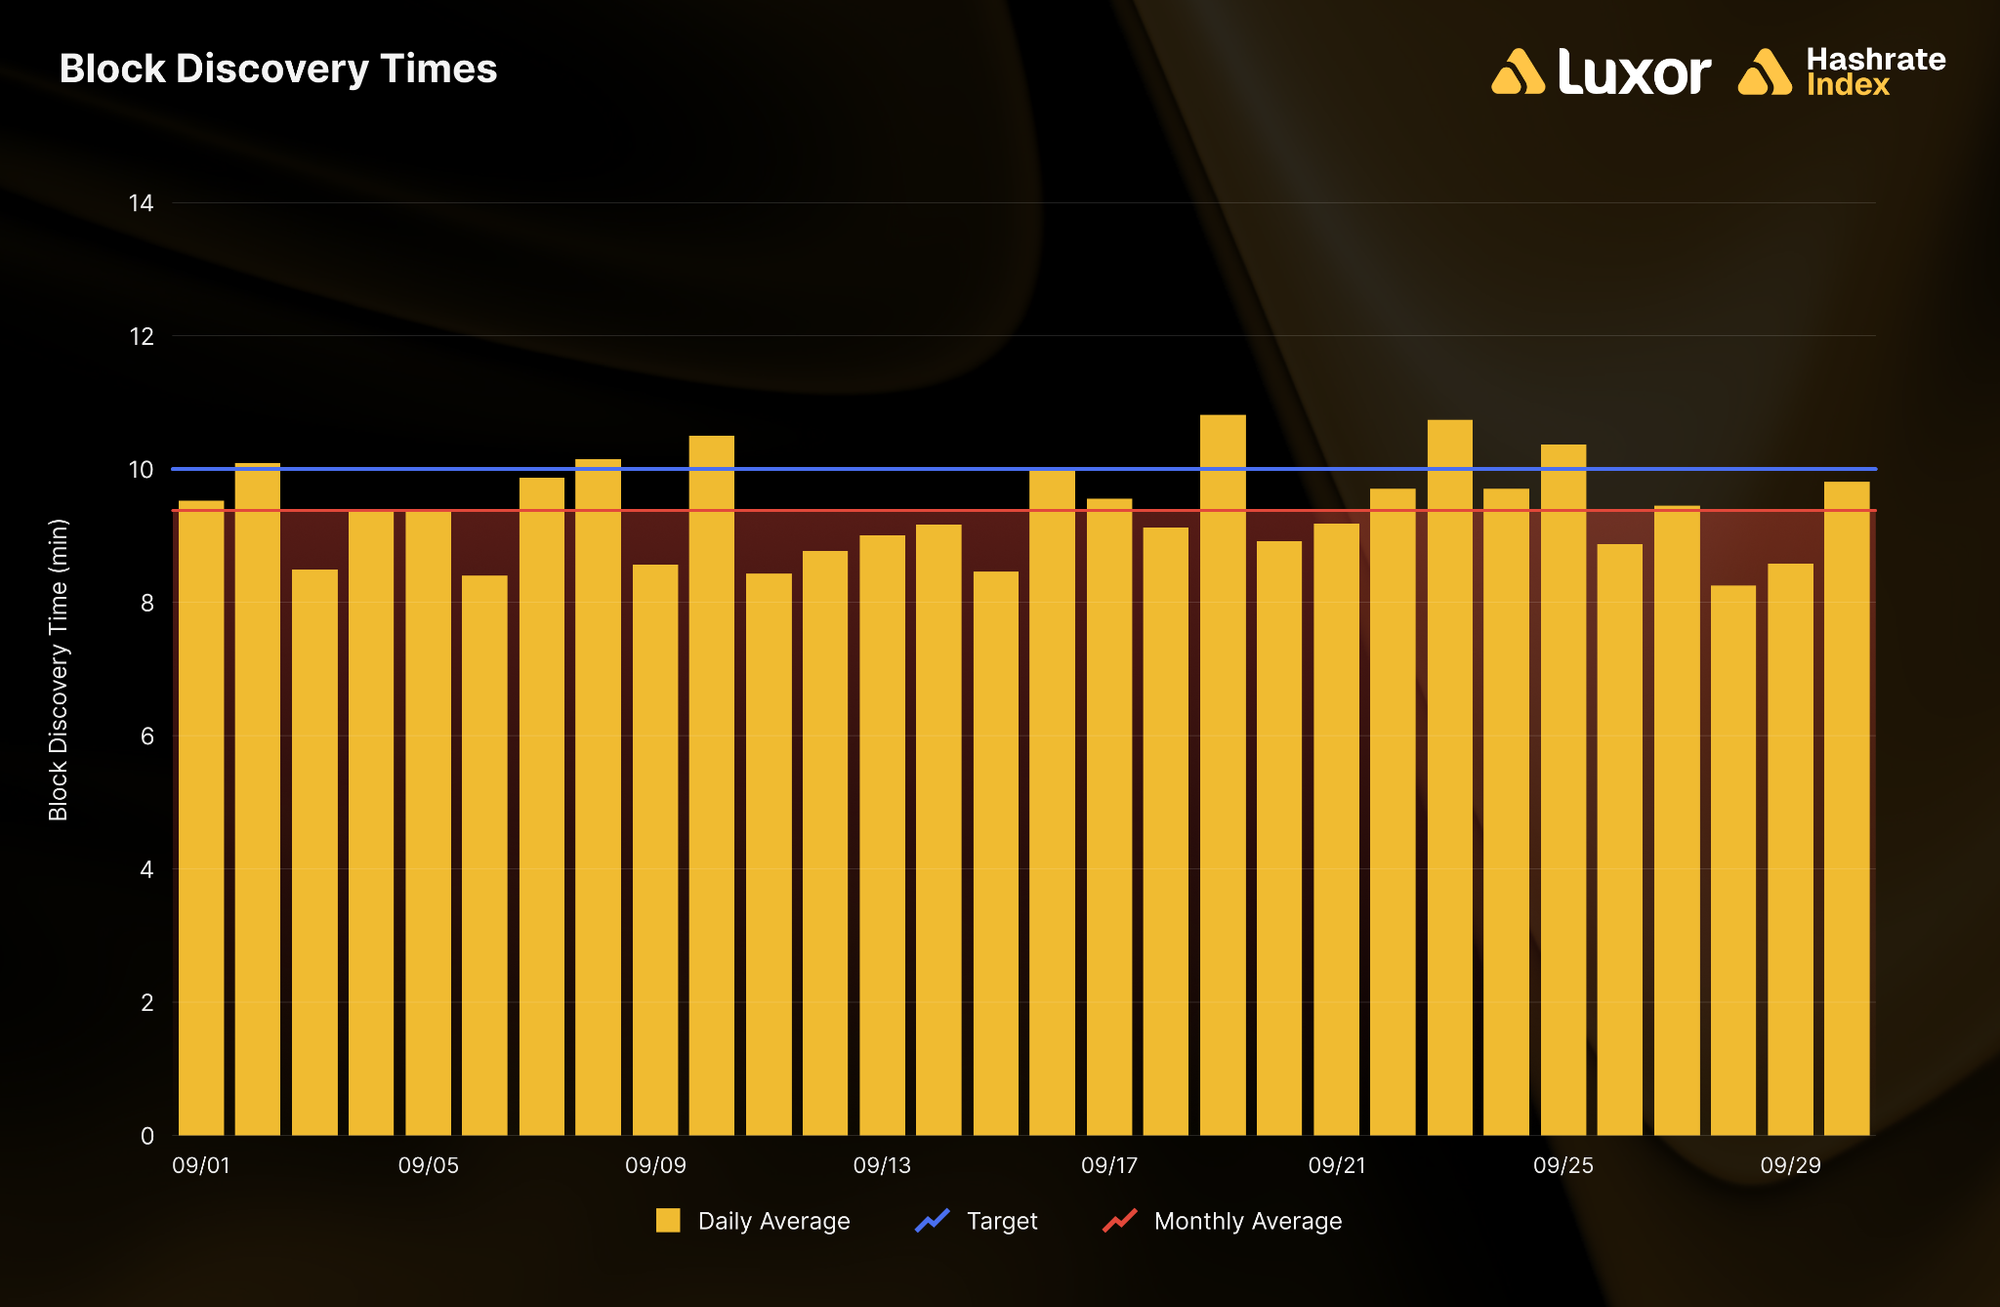
Block times averaged 9 minutes and 23 seconds, making it the fastest month for block generation since February, with 23 out of 30 days falling below the 10-minute target. This accelerated pace was driven largely by the return of curtailed mining capacity as the Texas summer drew to a close. As the seasonal demand response period ended, the 7-day network hashrate average climbed from 926 EH/s to 975 EH/s over the course of the month.
Historical data shows that ERCOT’s four coincident peaks for the season landed on June 18, July 22, August 24, and September 12. While July set the seasonal peak load at 90.96 GW, September’s final peak reached 86.49 GW at 4:30 PM Central Time. Flexible-load clients utilizing energy management services successfully curtailed operations across all four intervals, logging substantial downtime to avoid peak transmission charges. Under prevailing transmission rates, the financial benefit of avoiding these charges significantly outweighed the mining revenue foregone during curtailment, highlighting the growing sophistication of energy-aware mining operations.
Transaction Fees and Energy Hashprice Tiers
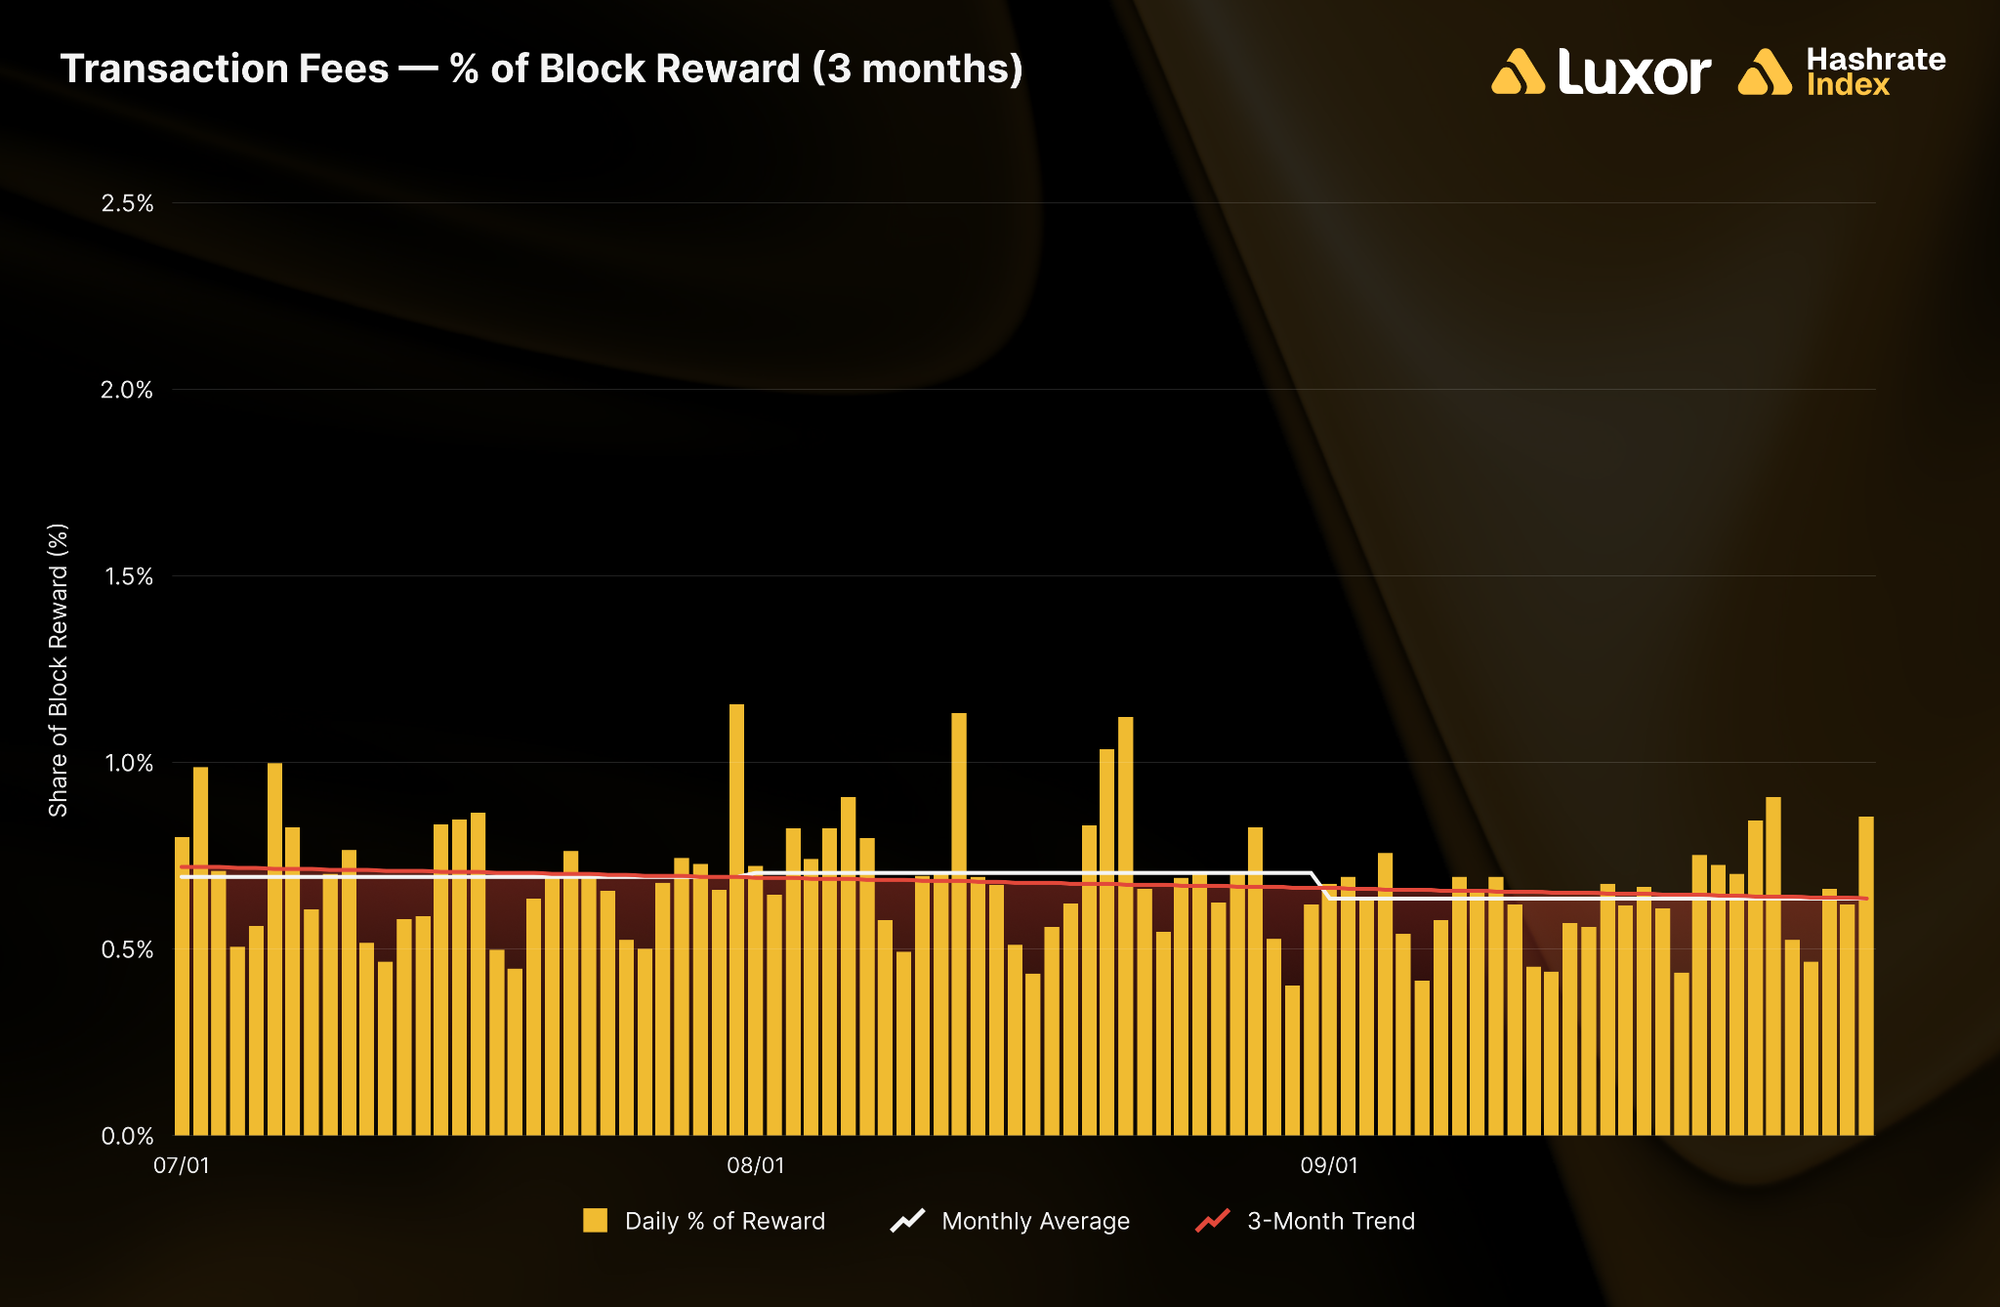
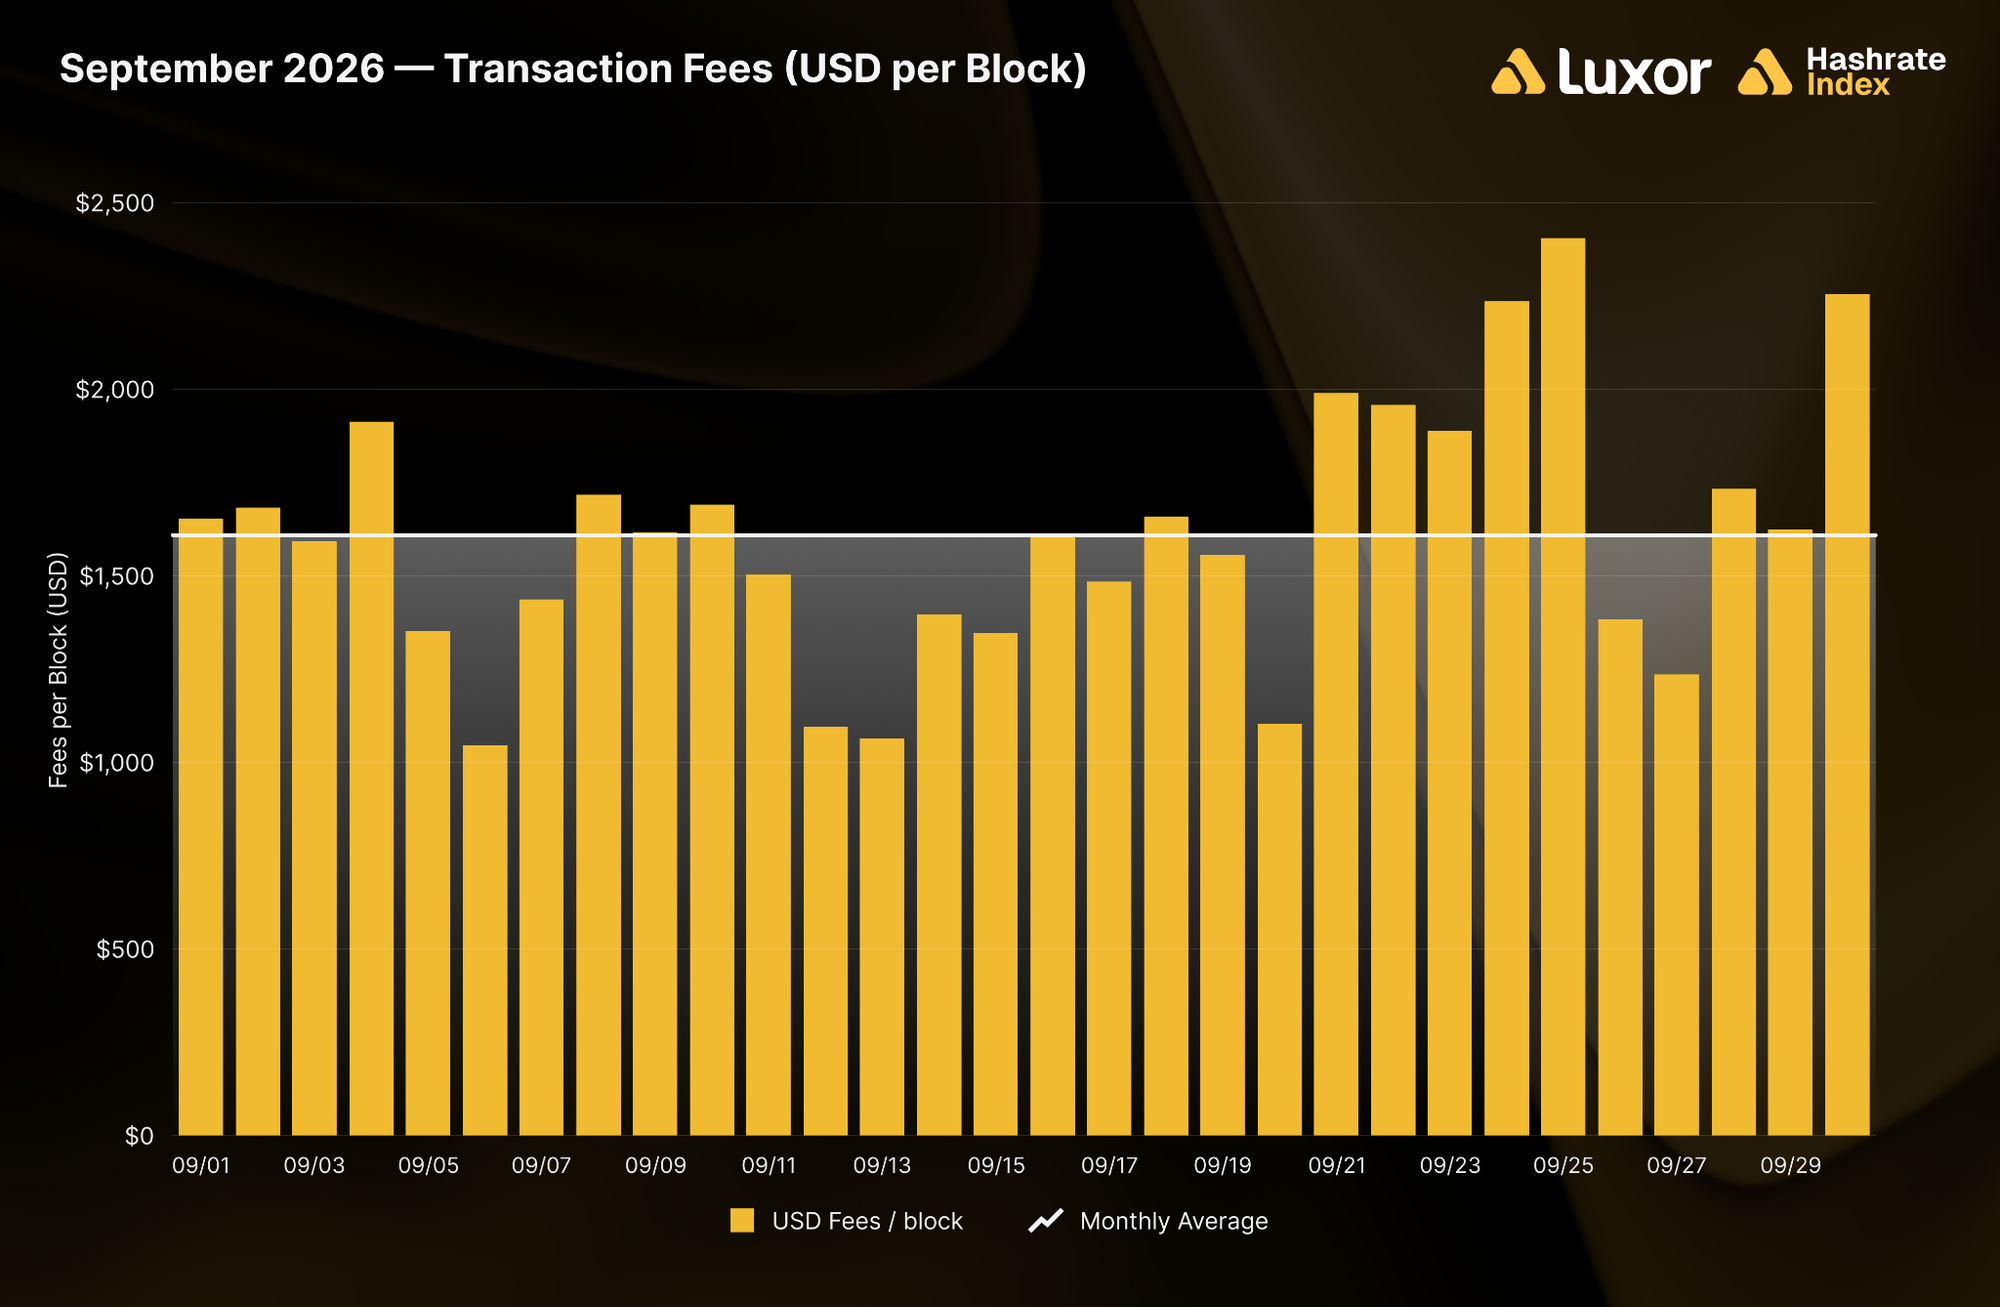
Transaction fee collection declined across the board, falling 10.1% to average 0.0199 BTC per block, the lowest level recorded since May. Fees accounted for just 0.63% of total block rewards, marking the fifteenth consecutive month that fee contributions remained below 1%. Daily fee collections ranged between 0.013 and 0.029 BTC per block, devoid of any significant outlier blocks. In US dollar terms, however, the average block earned approximately $1,607 in fees, representing a 4.8% increase entirely driven by the higher fiat price of Bitcoin.
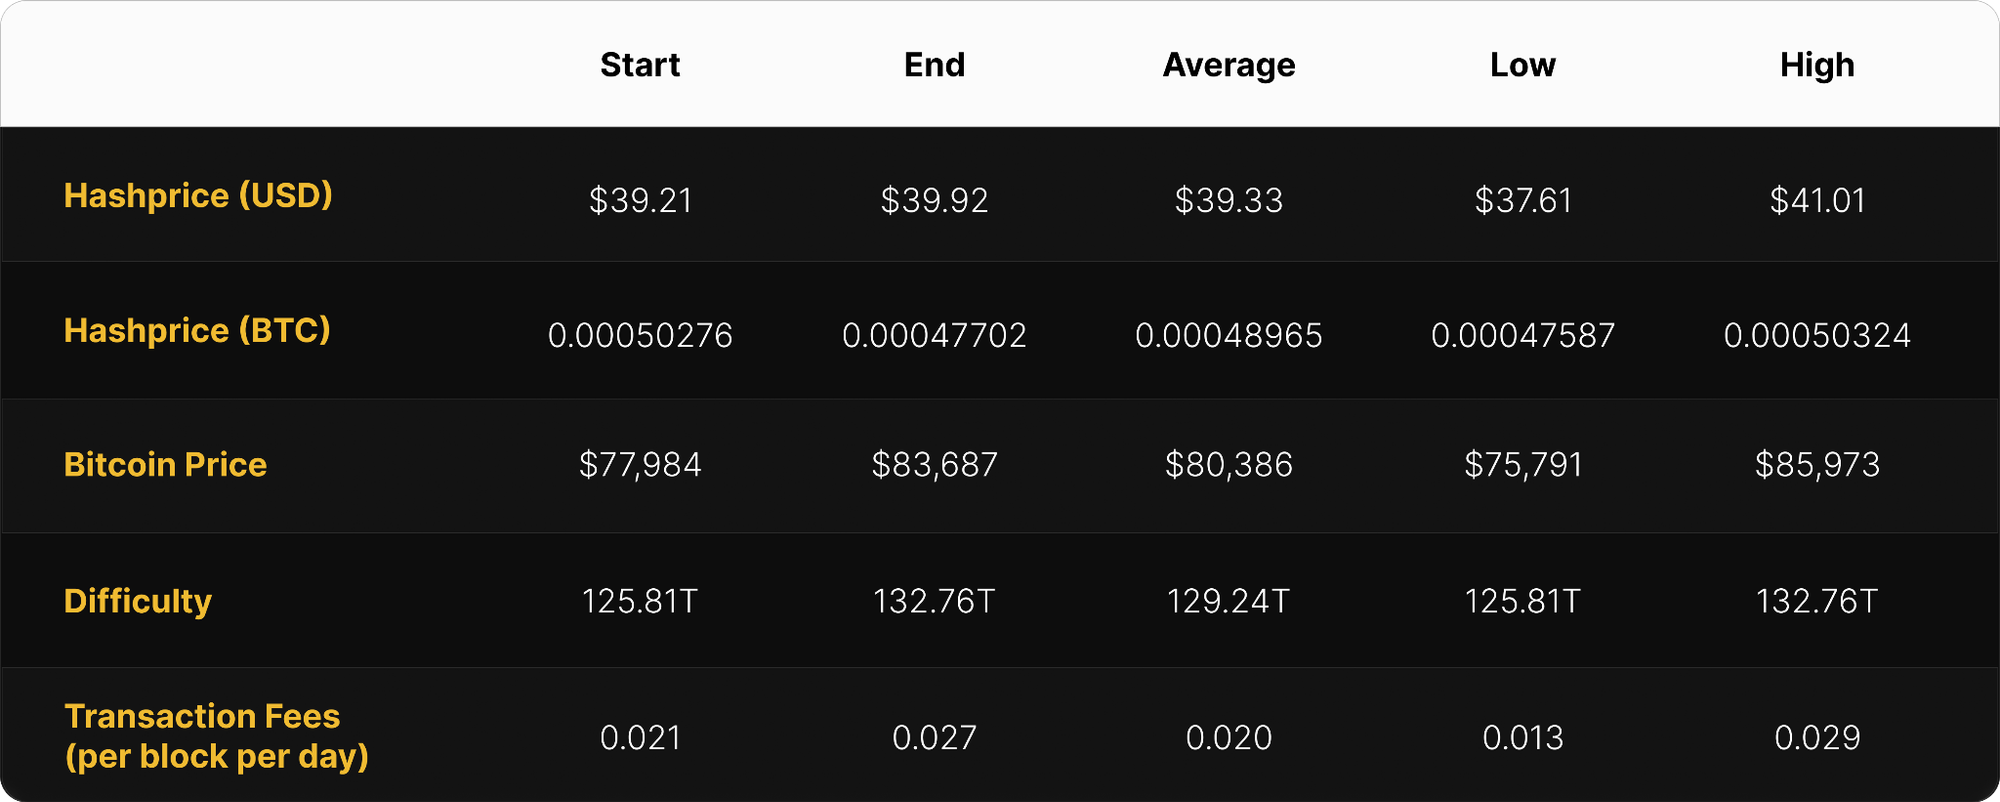
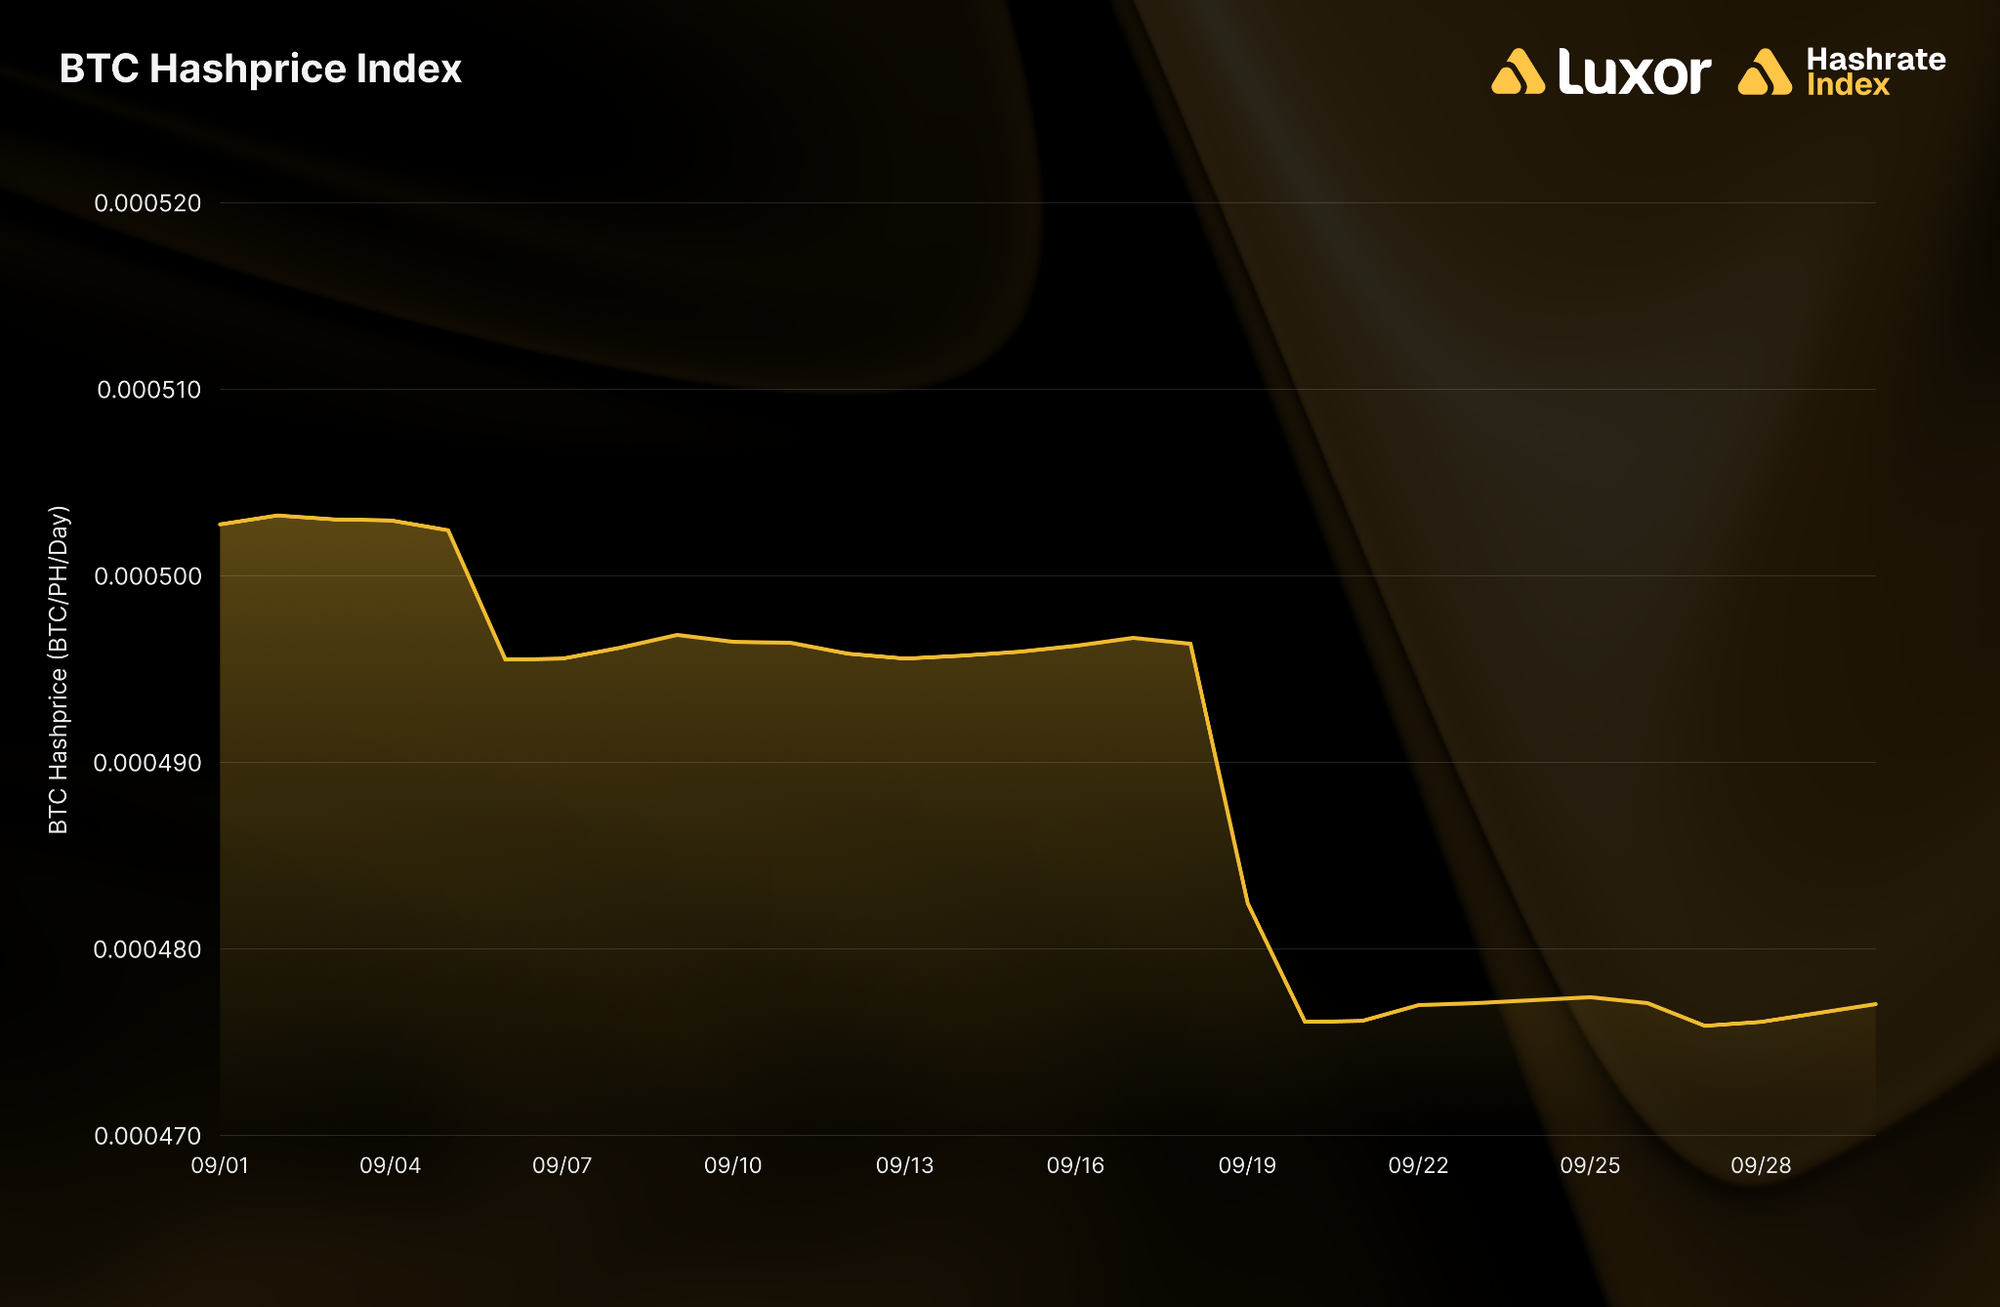
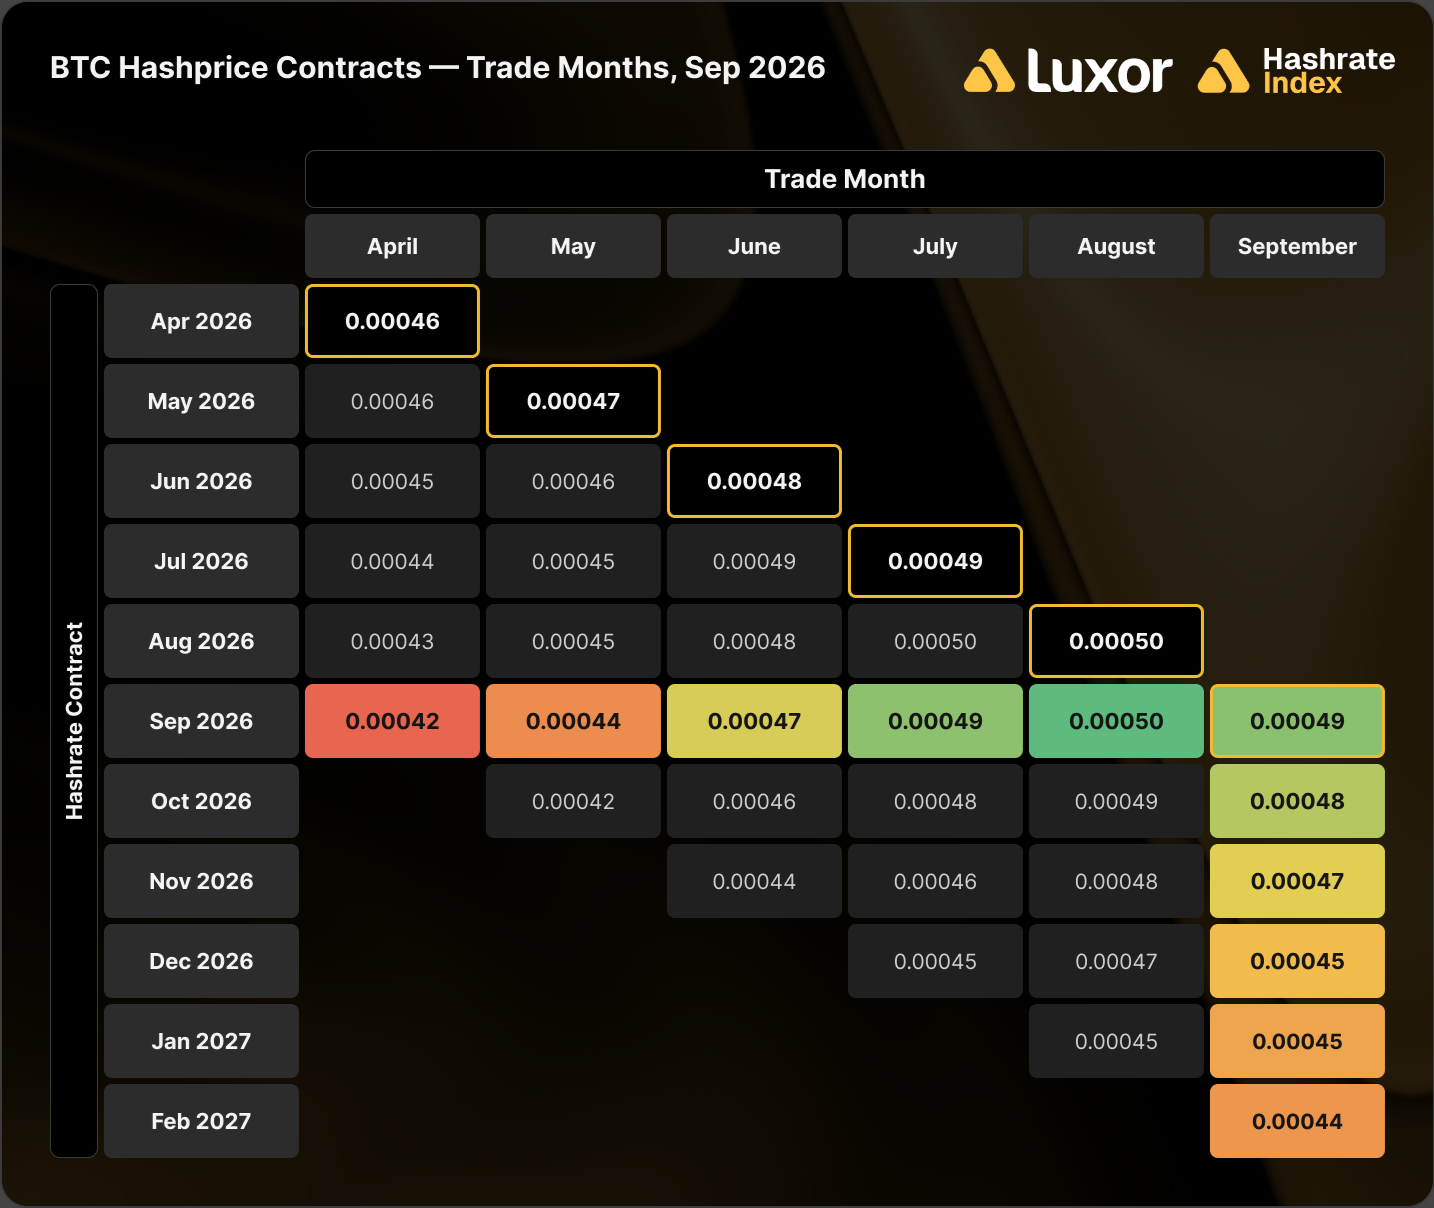
On a per-coin basis, monthly average BTC hashprice declined 2.0% to 0.00048965 BTC per PH/s/day, opening the month at 0.00050276 BTC and closing at 0.00047702 BTC. Each step down in BTC hashprice coincided directly with network difficulty retarget dates, illustrating the inverse relationship between network hashrate expansion and per-coin profitability.
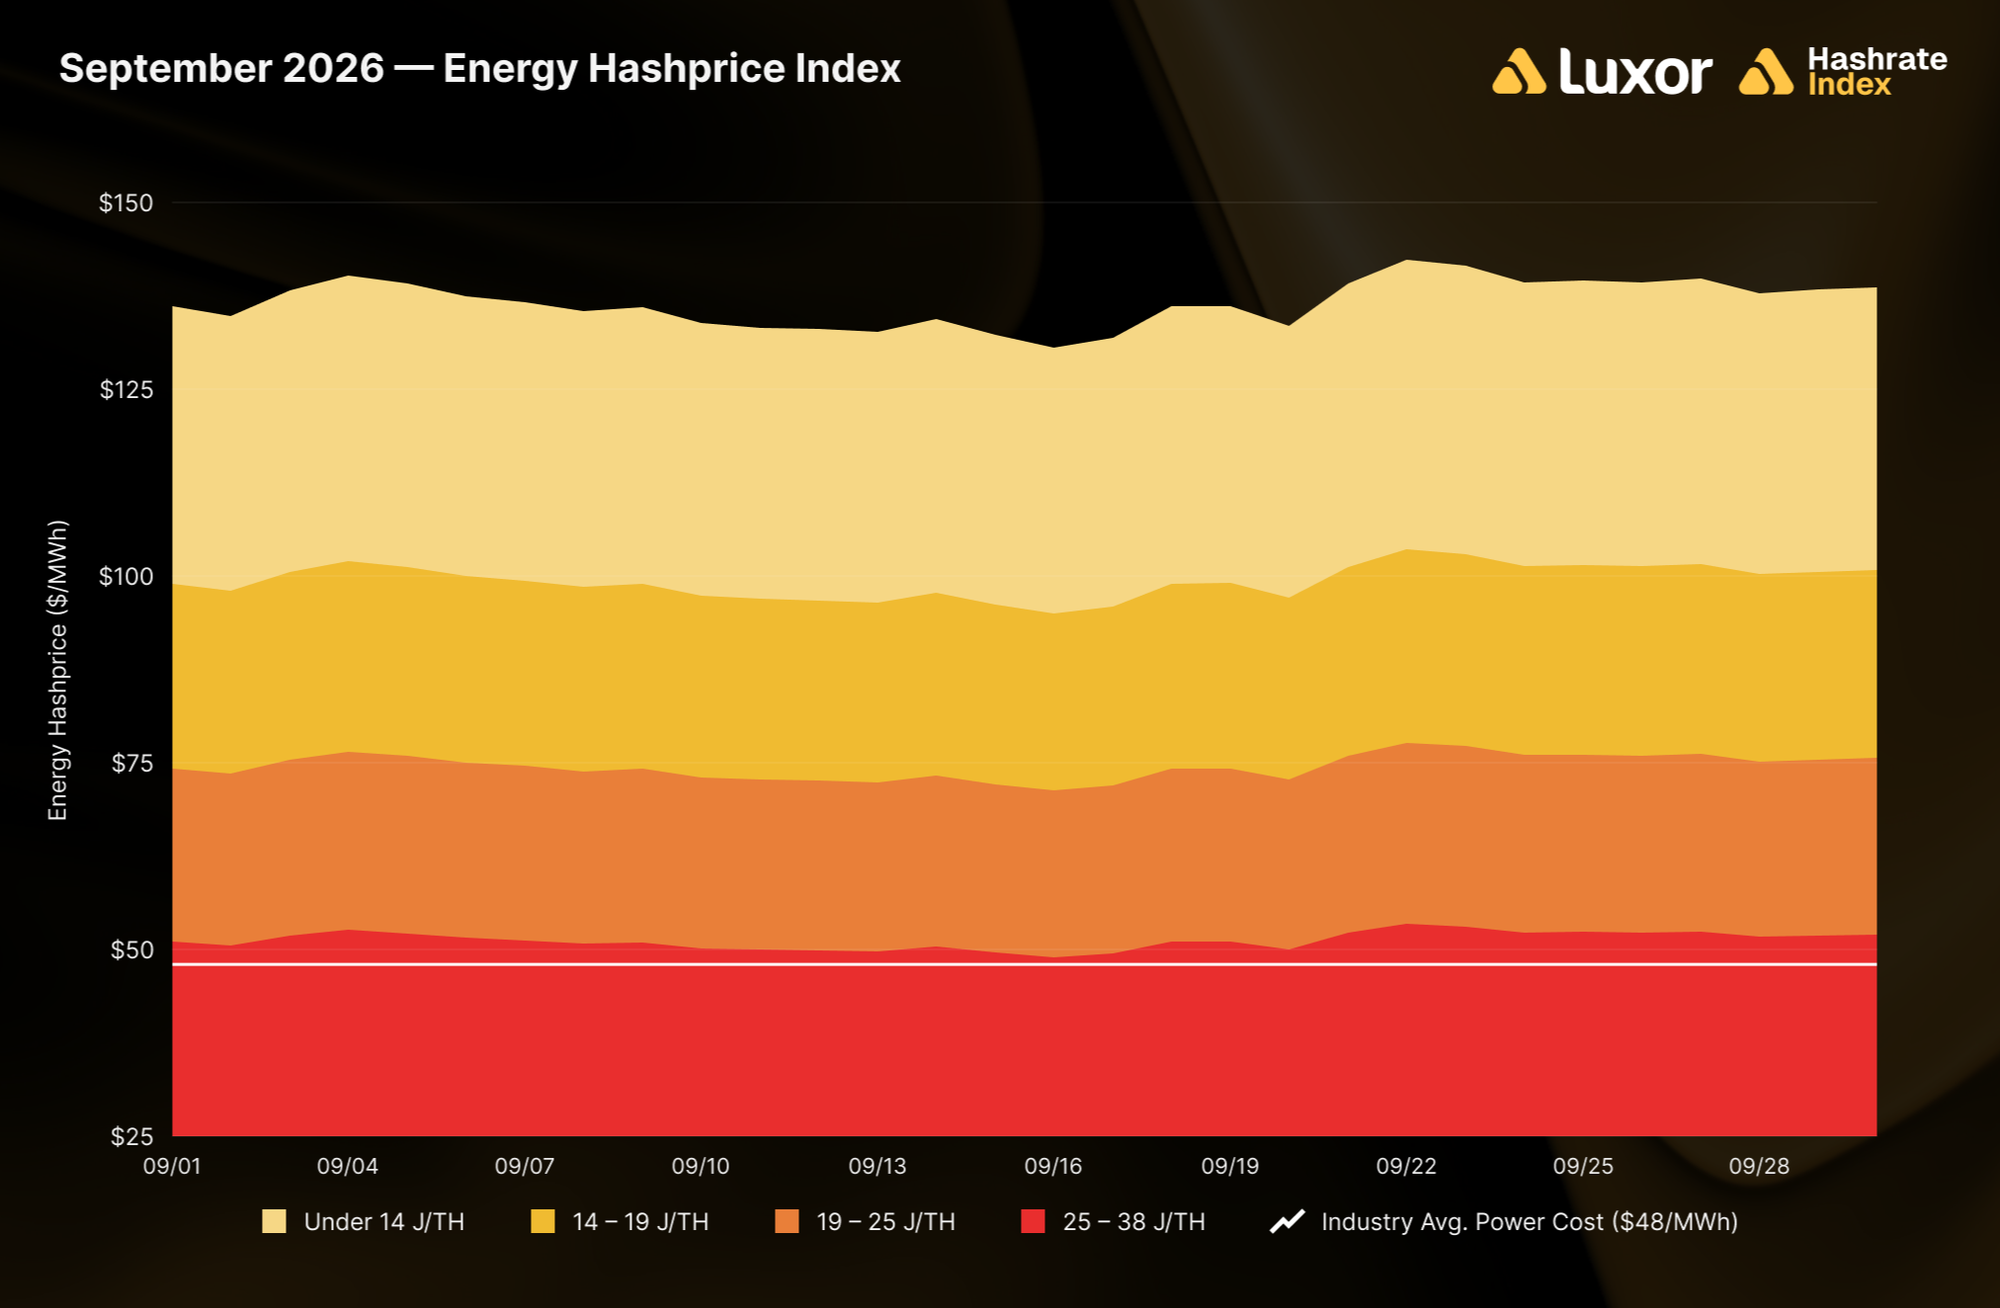
Meanwhile, energy hashprice rose uniformly across all fleet efficiency tiers. Driven by overall hashprice appreciation, every tier saw its monthly average increase by approximately 13.6%. When evaluated against an average industrial Bitcoin mining power cost of $48 per MWh, the marginal fleet efficiency bucket covering devices operating between 25 and 38 J/TH finished September above $51 per MWh on every single day of the final week, providing a healthier operational margin for modern hardware.
Hashrate Market Activity and Forward Trading
Analysis of the hashrate derivatives market highlights evolving strategies among participants utilizing Luxor’s deliverable and non-deliverable hashrate forward contracts. Throughout September, institutional lenders remained active on the buy side of deliverable contracts, while both public and private mining enterprises utilized forward sales to secure non-dilutive financing, manage capital expenditure, and fund fleet upgrades and expansions.
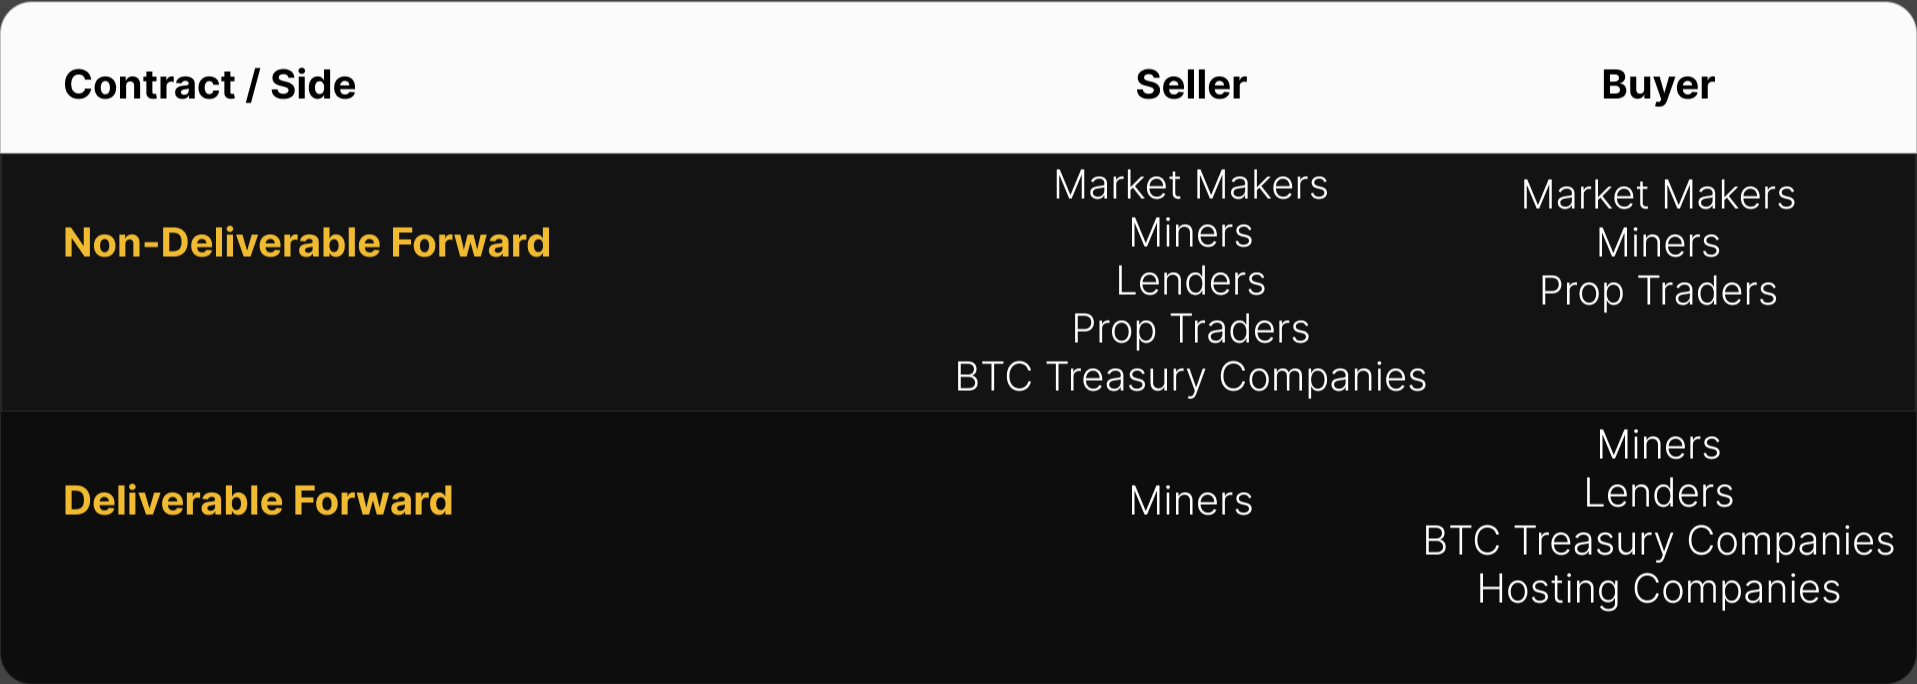
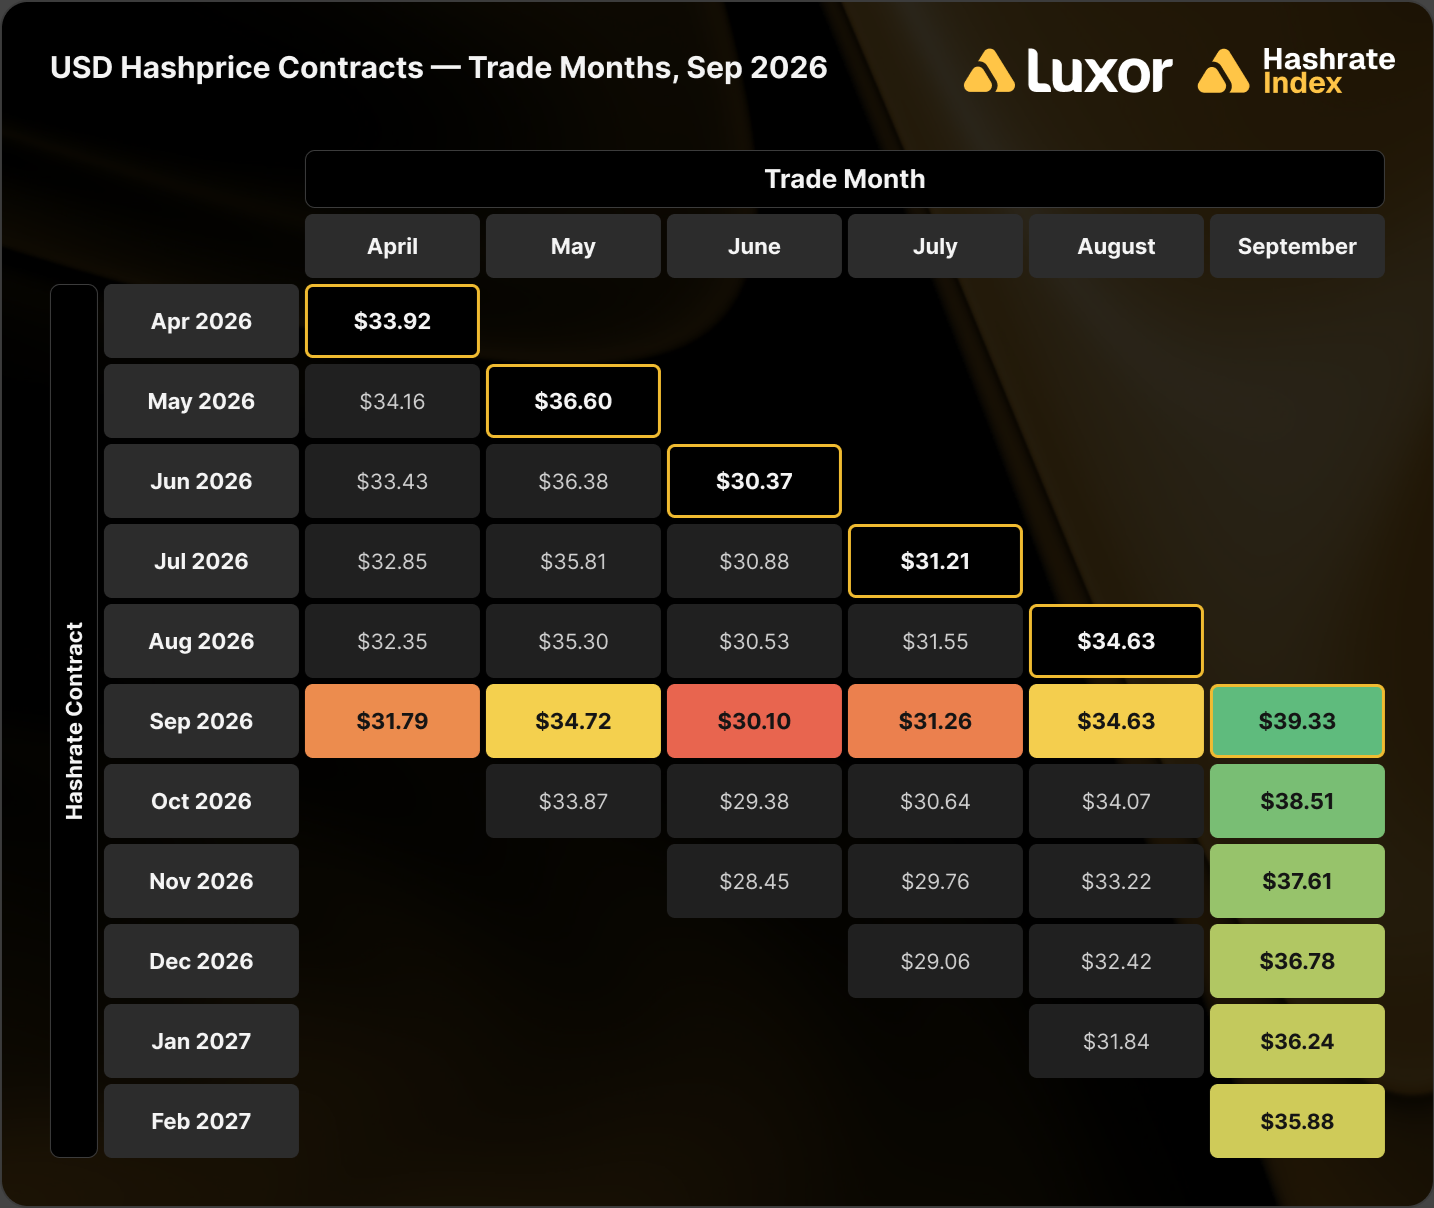
Because deliverable forwards are prepaid, they typically trade at a discount to non-deliverable forwards to compensate buyers for credit risk and the cost of capital. Pairing a deliverable forward with an offsetting non-deliverable contract allows market participants to lock in that spread as a fixed yield. In September 2026, this implied cost of capital ranged between 6% and 13% annualized, serving as an effective financial instrument for lenders and Bitcoin treasury companies seeking predictable yields alongside miners seeking capital liquidity.
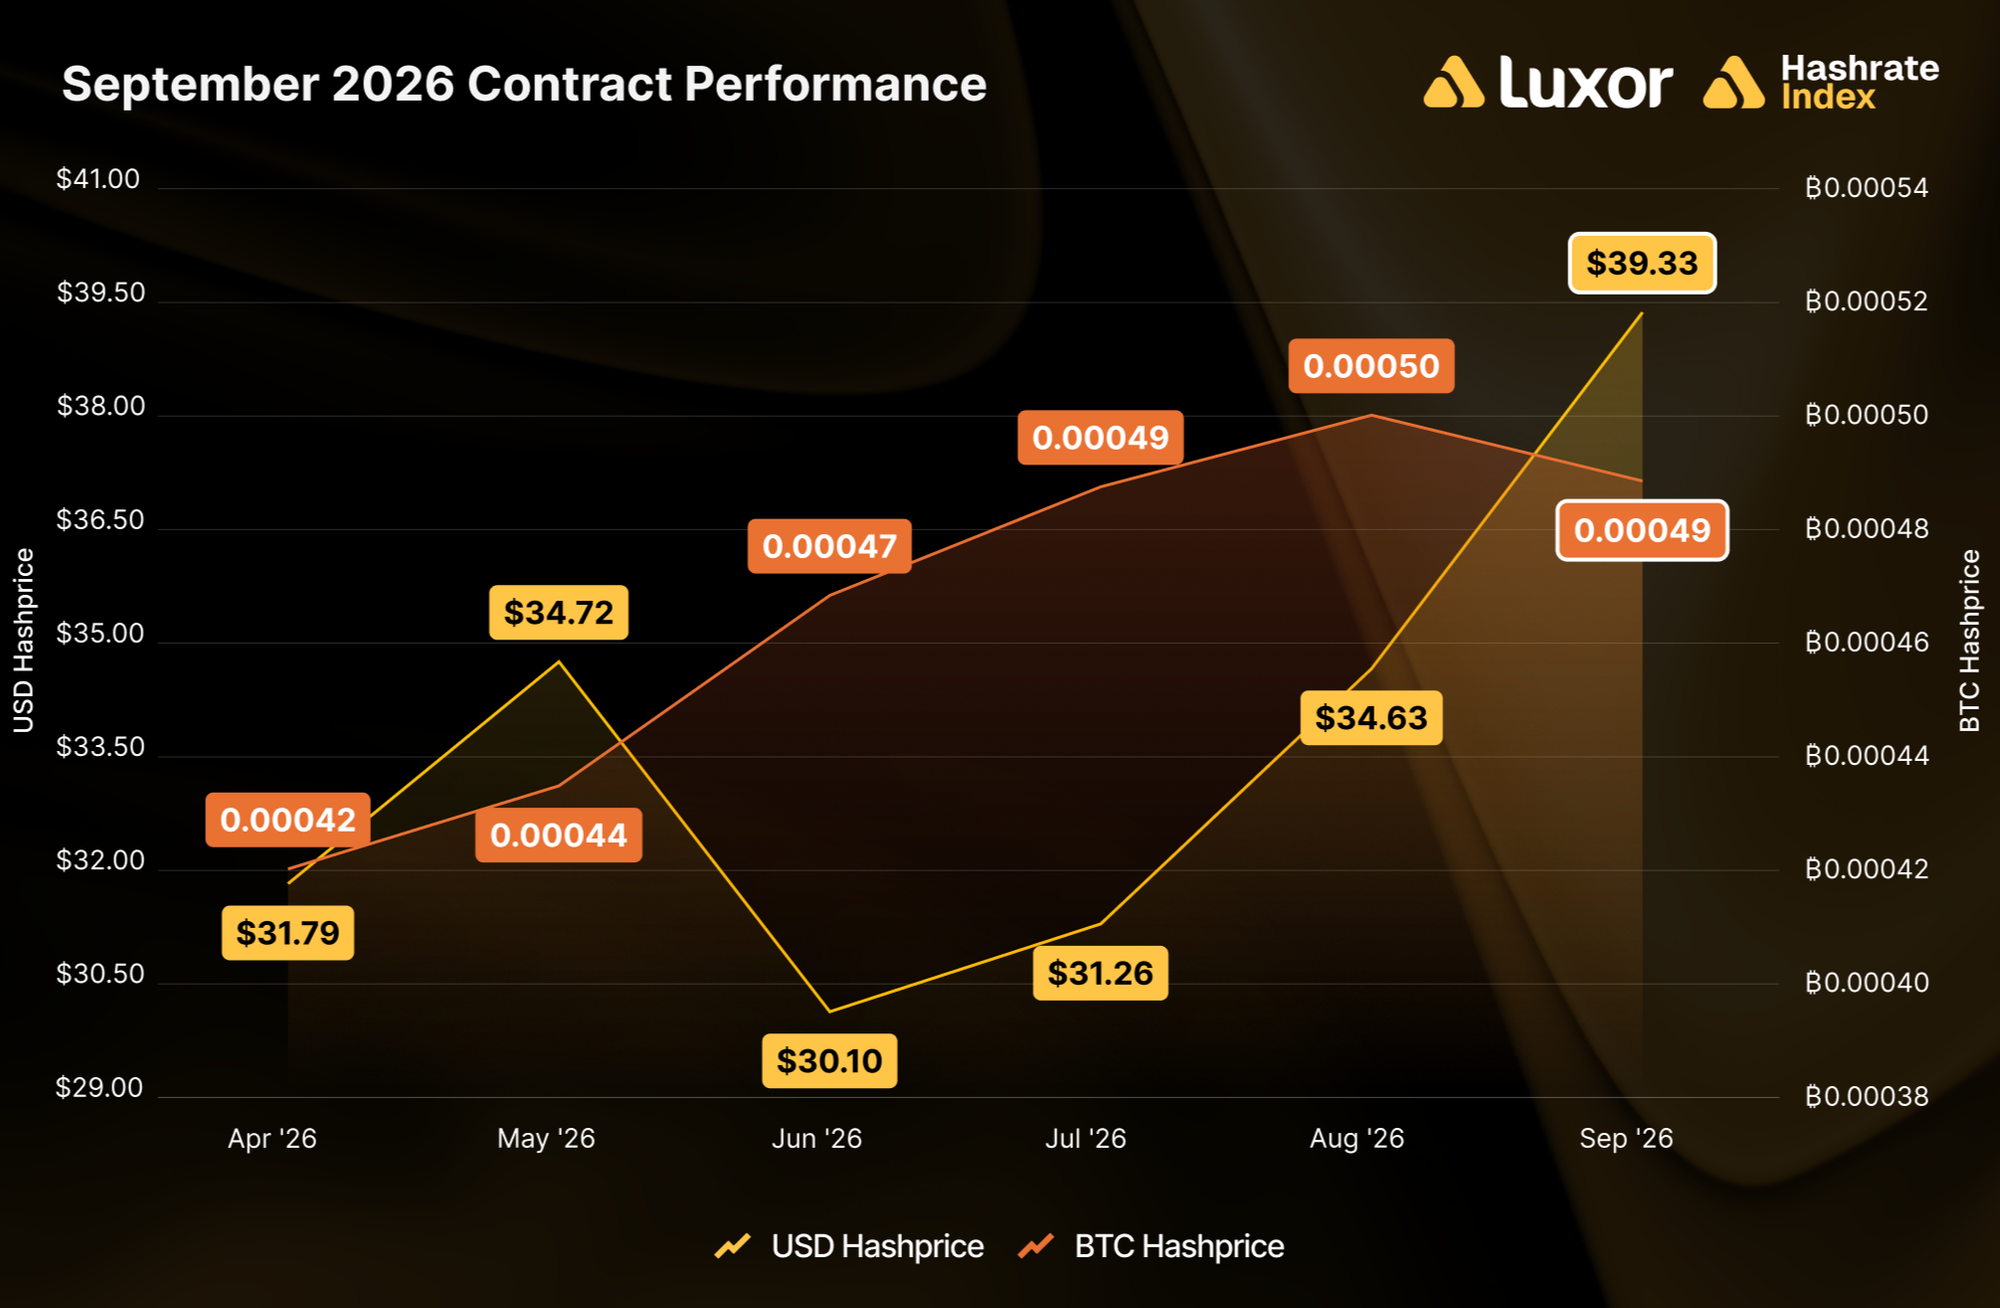
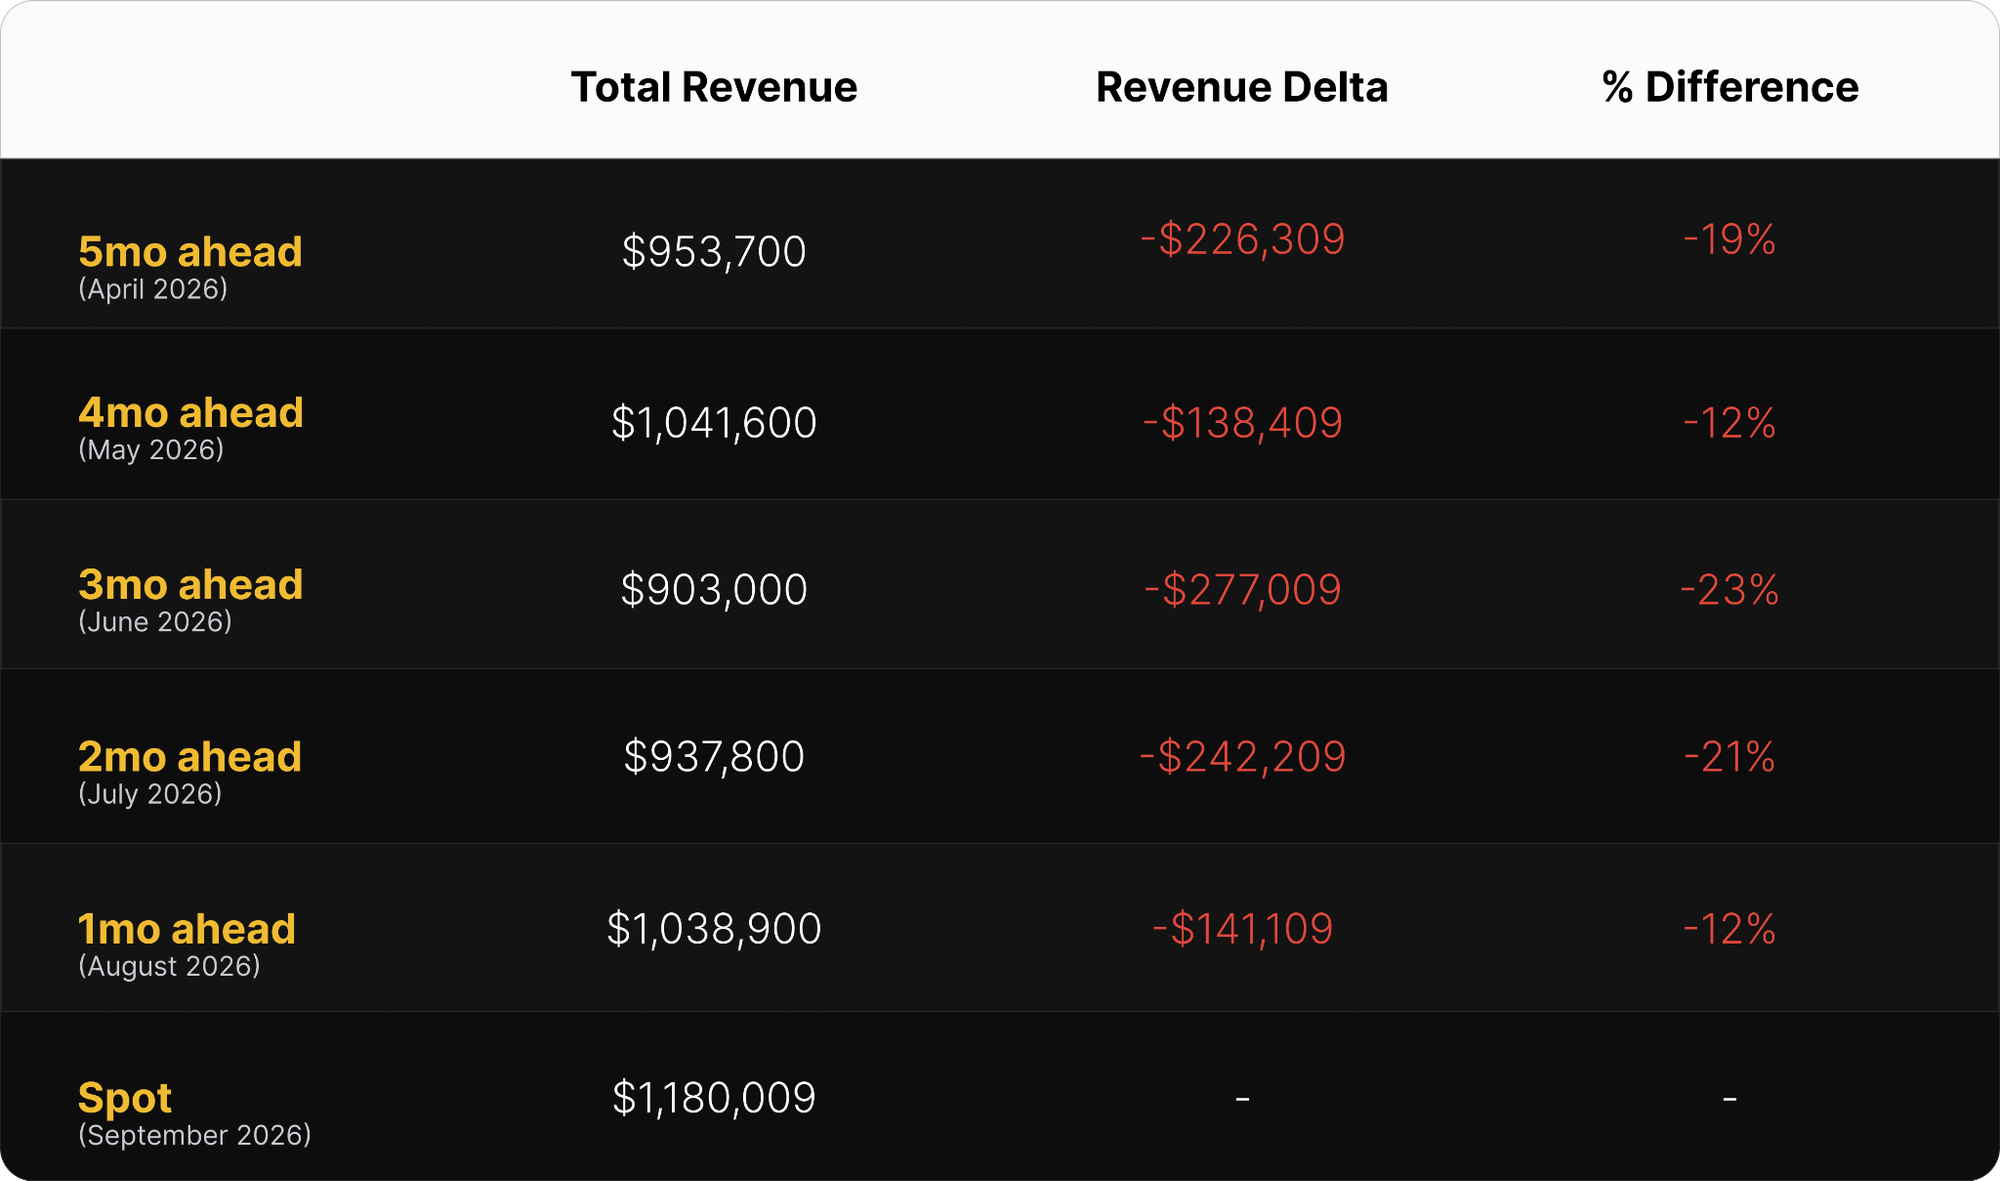
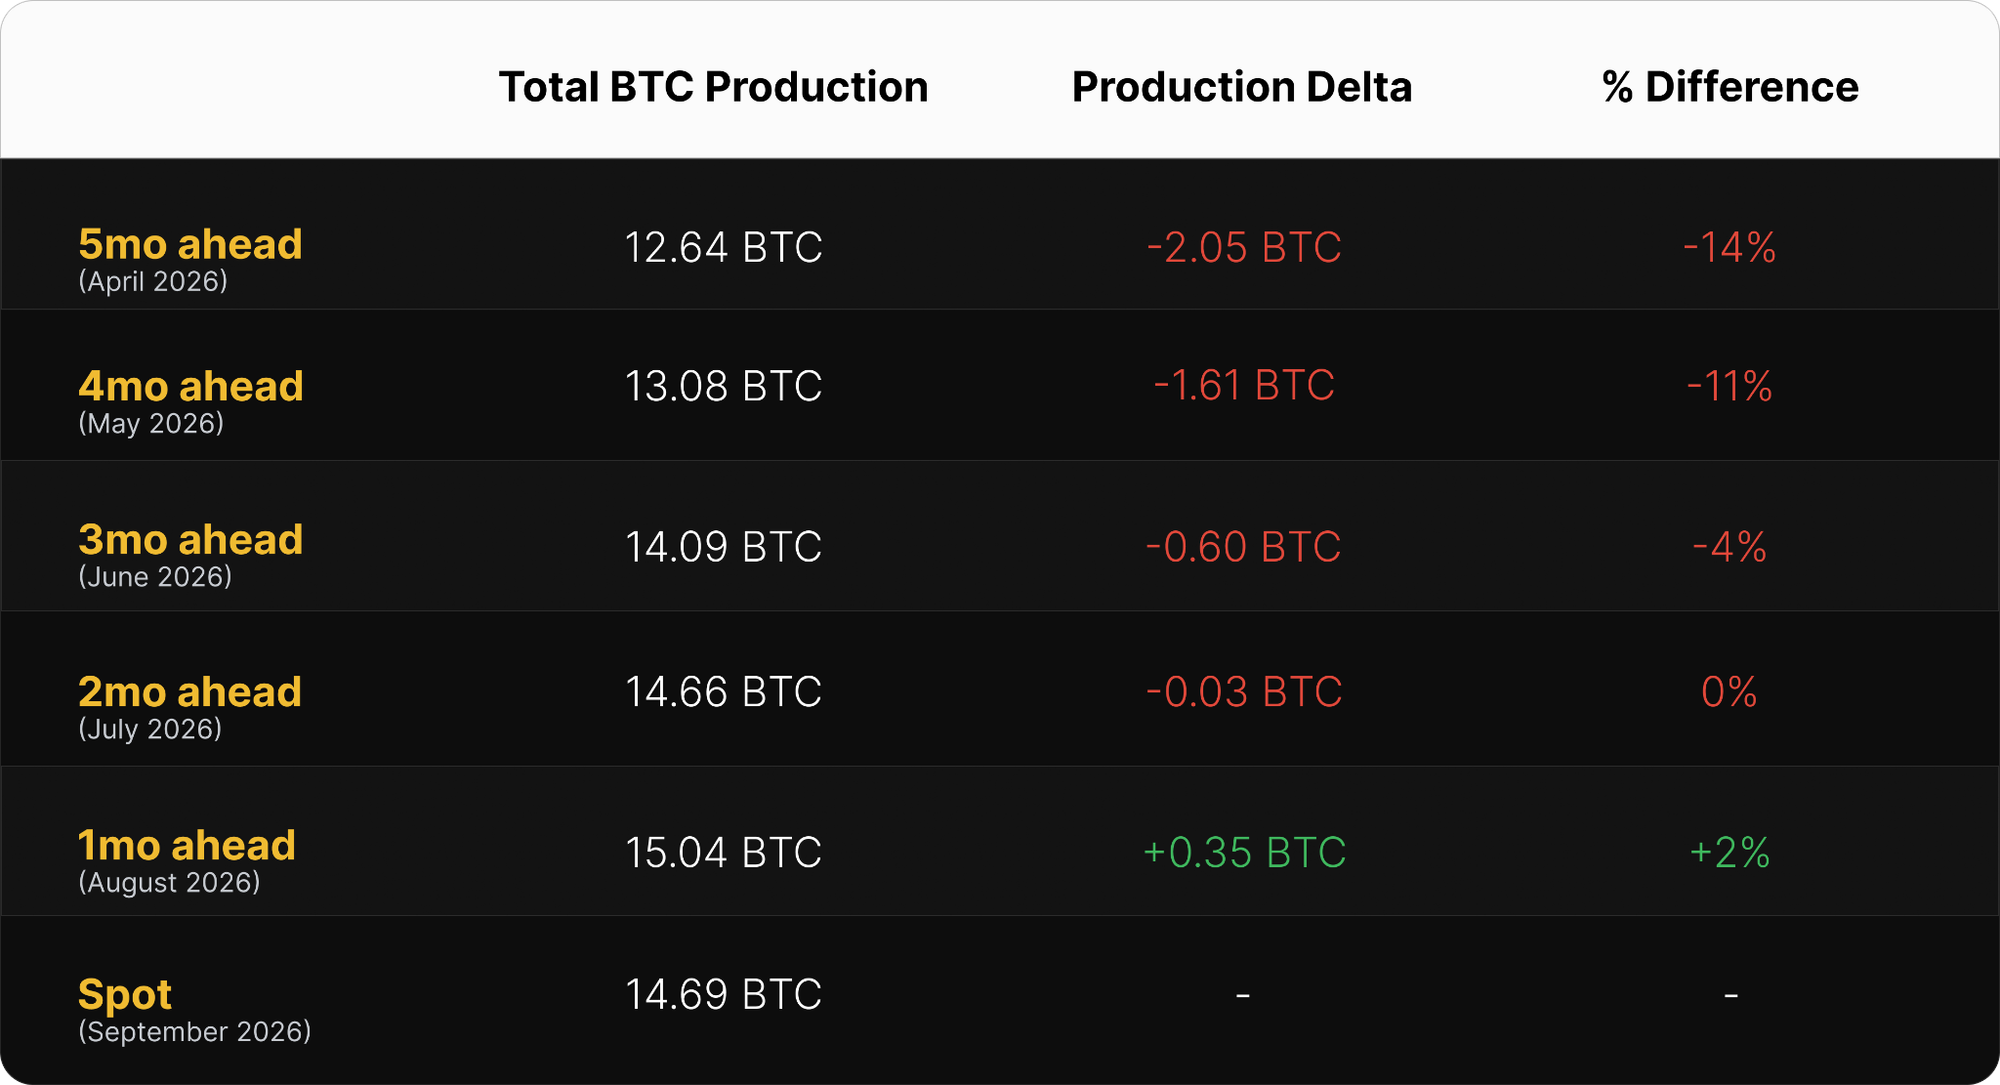
September marked the first month since July 2025 in which every dollar-denominated hashprice hedge resulted in a loss relative to spot settlement. Sellers of the September USD contract locked in rates between $30.10 and $34.72 per PH/s/day, whereas spot hashprice ultimately settled at a higher monthly average of $39.33. Conversely, in Bitcoin-denominated terms, a five-month losing streak for forward hedges was broken. While hedges executed two to five months prior continued to lag spot settlement, August’s one-month forward sale executed at 0.00050 BTC per PH/s/day outperformed the September spot settlement of 0.00049 BTC by 2.4%.
Looking Ahead to October and Beyond
As the industry transitions into October, early data indicates a continuation of elevated network activity. Hashprice through the first week of October averaged $40.37, supported by a stable Bitcoin price averaging $84,655. With the Texas 4CP summer season officially concluded, historical seasonal patterns suggest that October typically brings substantial difficulty growth, averaging over 4% per adjustment epoch and roughly 10% across the month as a whole.
The forward market has already begun pricing in this anticipated expansion, with implied network hashrate projected to surpass the 1 Zettawatt milestone in early 2027 by reaching approximately 1,029 EH/s in January. As miners bring offline capacity back online and new hardware deployments continue, the central question for the remainder of the year remains whether Bitcoin’s price appreciation can outpace the relentless upward pressure of network difficulty growth.
 Cryptocurrency Mining
 Cryptocurrency Mining
 Cryptocurrency Mining