Luxor’s Monthly Lookback Series offers a comprehensive examination of Bitcoin hashrate market activity, tracking the delicate balance between network security, asset pricing, and derivative performance. The September 2026 report highlights a month where macroeconomic pressures and structural shifts in the mining sector collided. While Bitcoin’s spot price rallied to recover ground lost during previous market pullbacks, a concurrent rise in network difficulty effectively capped revenue gains for miners worldwide.
September 2026 Spot Hashprice and Its Constituents
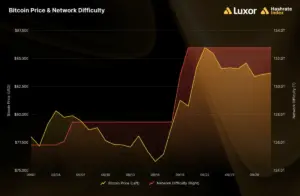
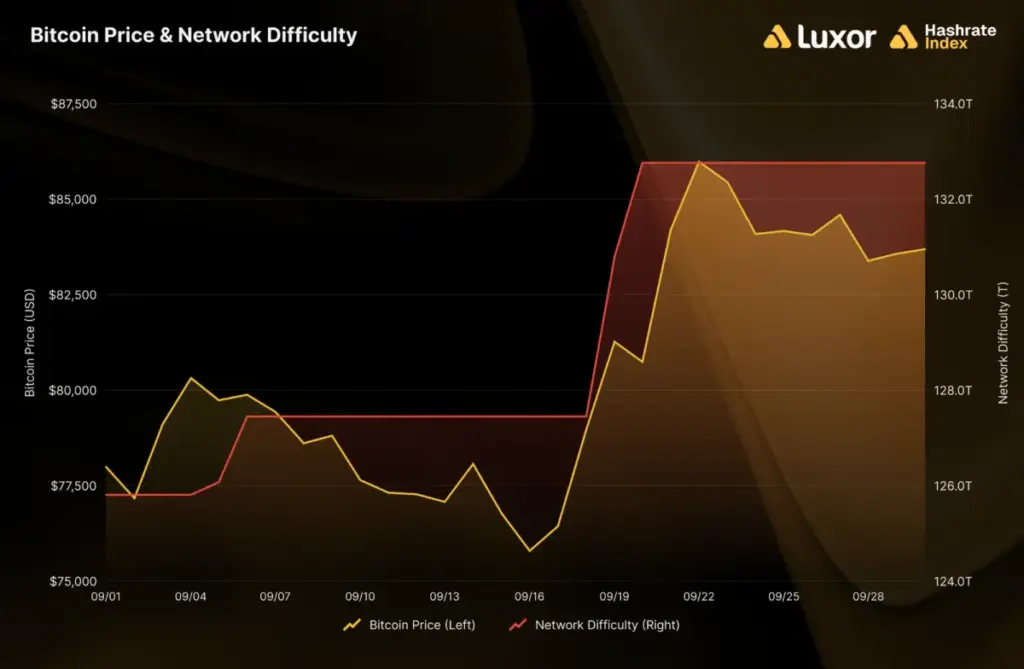
August’s strong Bitcoin rally added significant momentum to hashprice over a compressed twelve-day window, concluding with an open question: would Bitcoin maintain its upward trajectory, or would network difficulty neutralize those revenue gains? September delivered an intriguing mixture of both forces. Bitcoin climbed roughly 7.3% from its monthly open to its close, while network difficulty expanded by 5.5% across two upward difficulty retargets. Consequently, spot hashprice finished the month within a razor-thin margin of where it began.
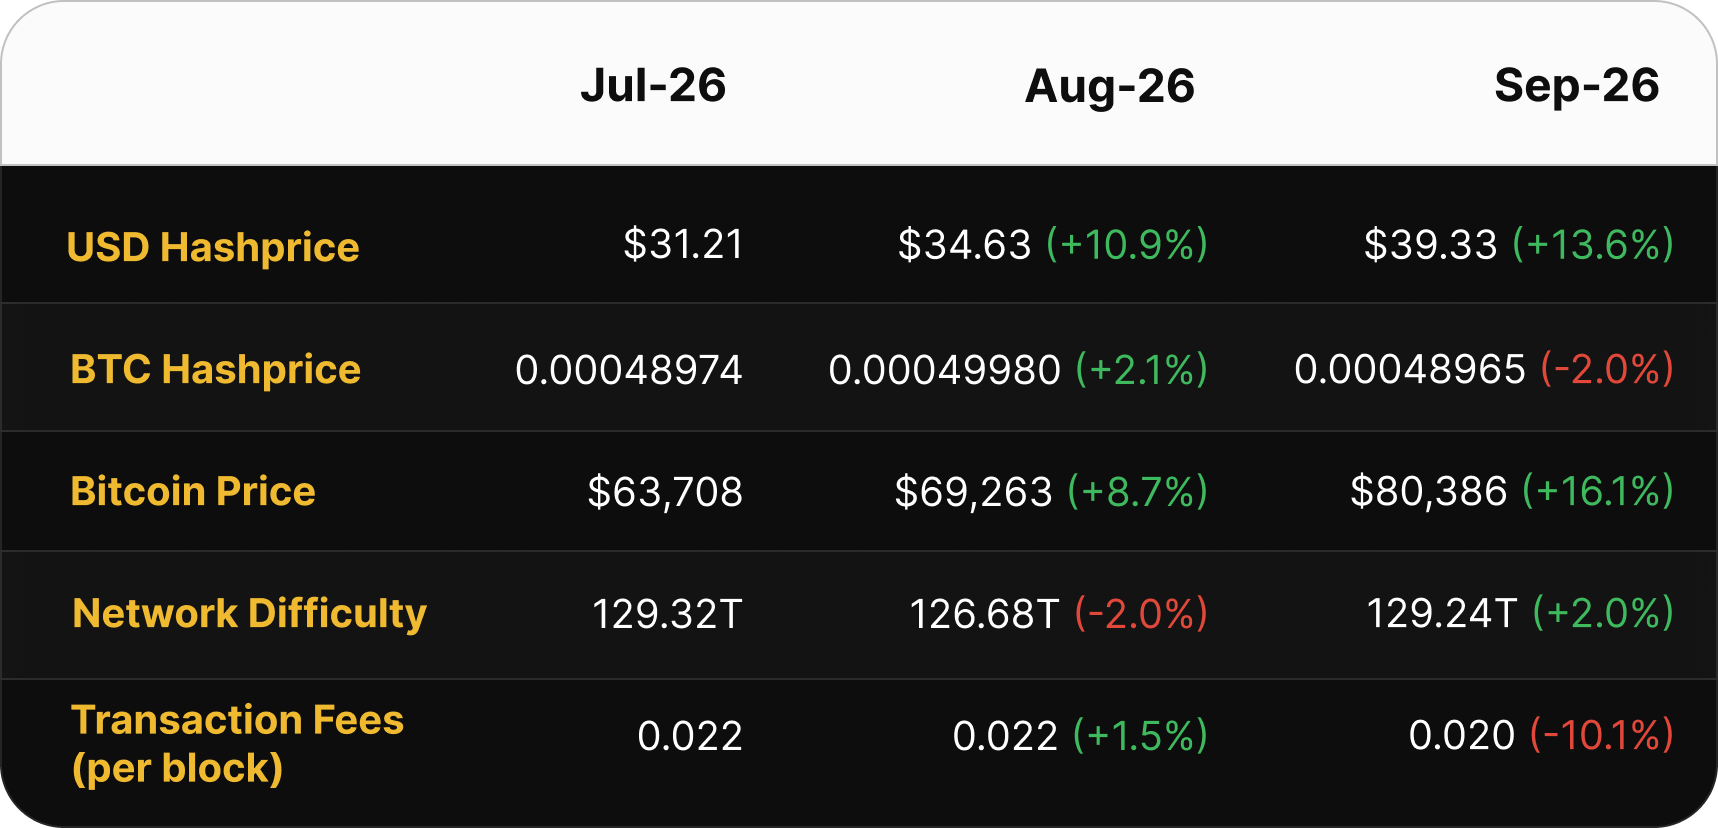
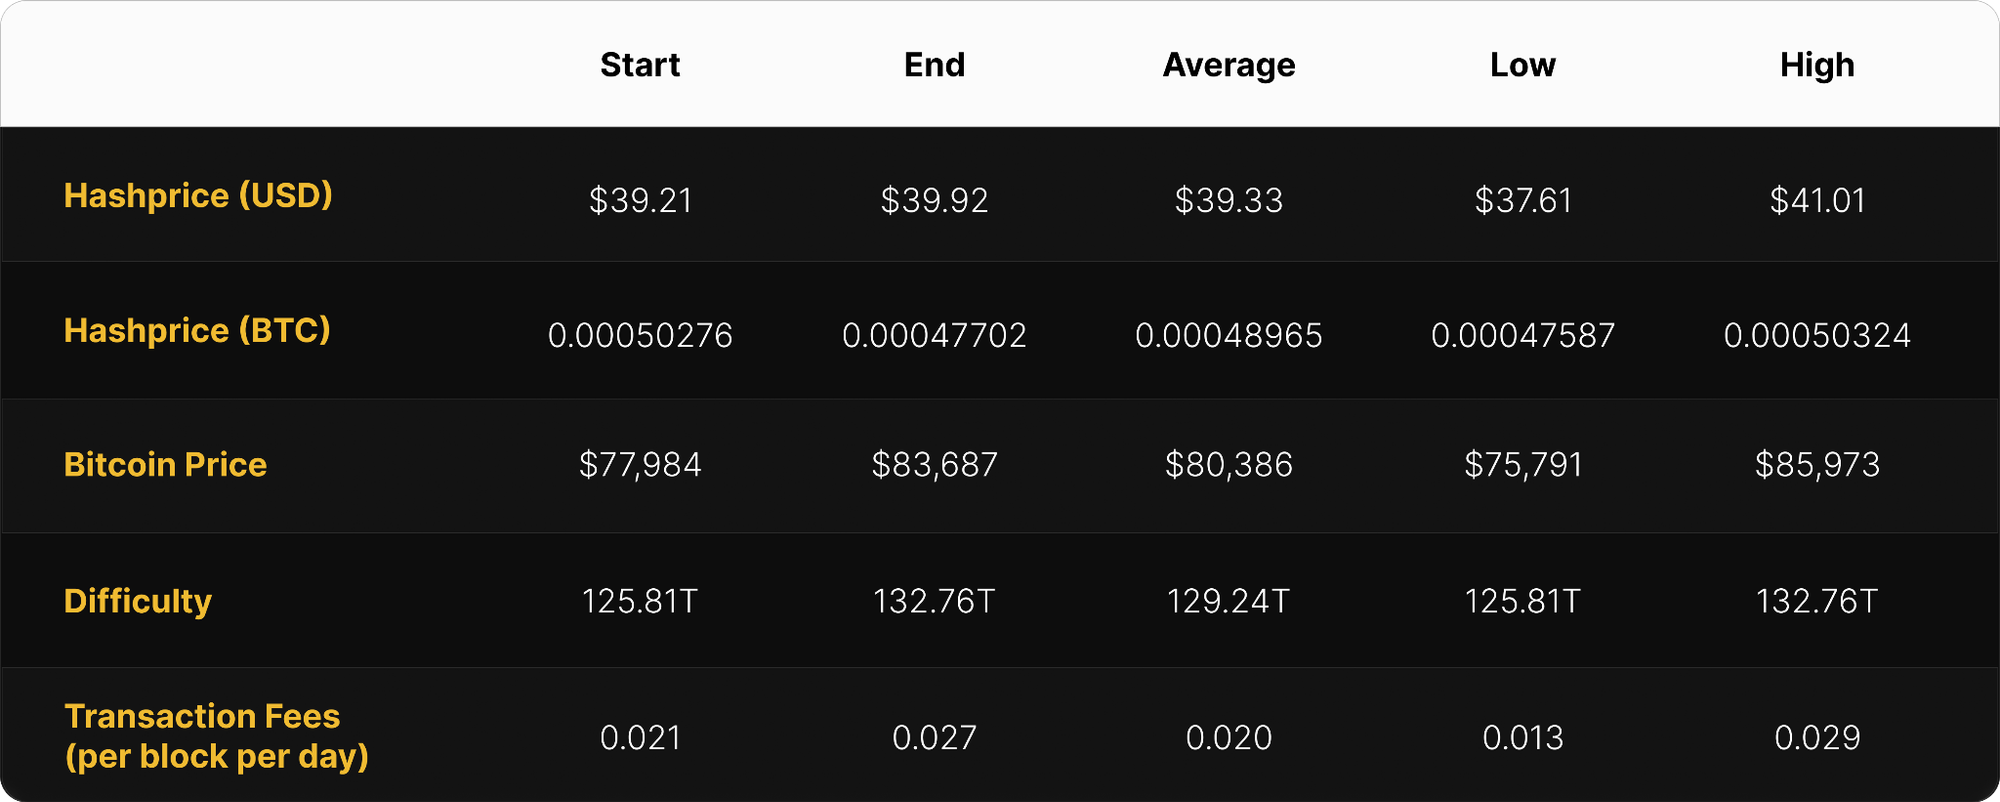
USD hashprice successfully defended the ground won during August while capturing modest additional gains. The month commenced at $39.21 per PH/s/day, edged up 1.8% to close at $39.92, and registered a monthly average of $39.33—marking the highest monthly average recorded since January. A total of nine days settled above the $40 threshold, representing the highest frequency of days above that mark since November 2025, compared to just a single day in August.
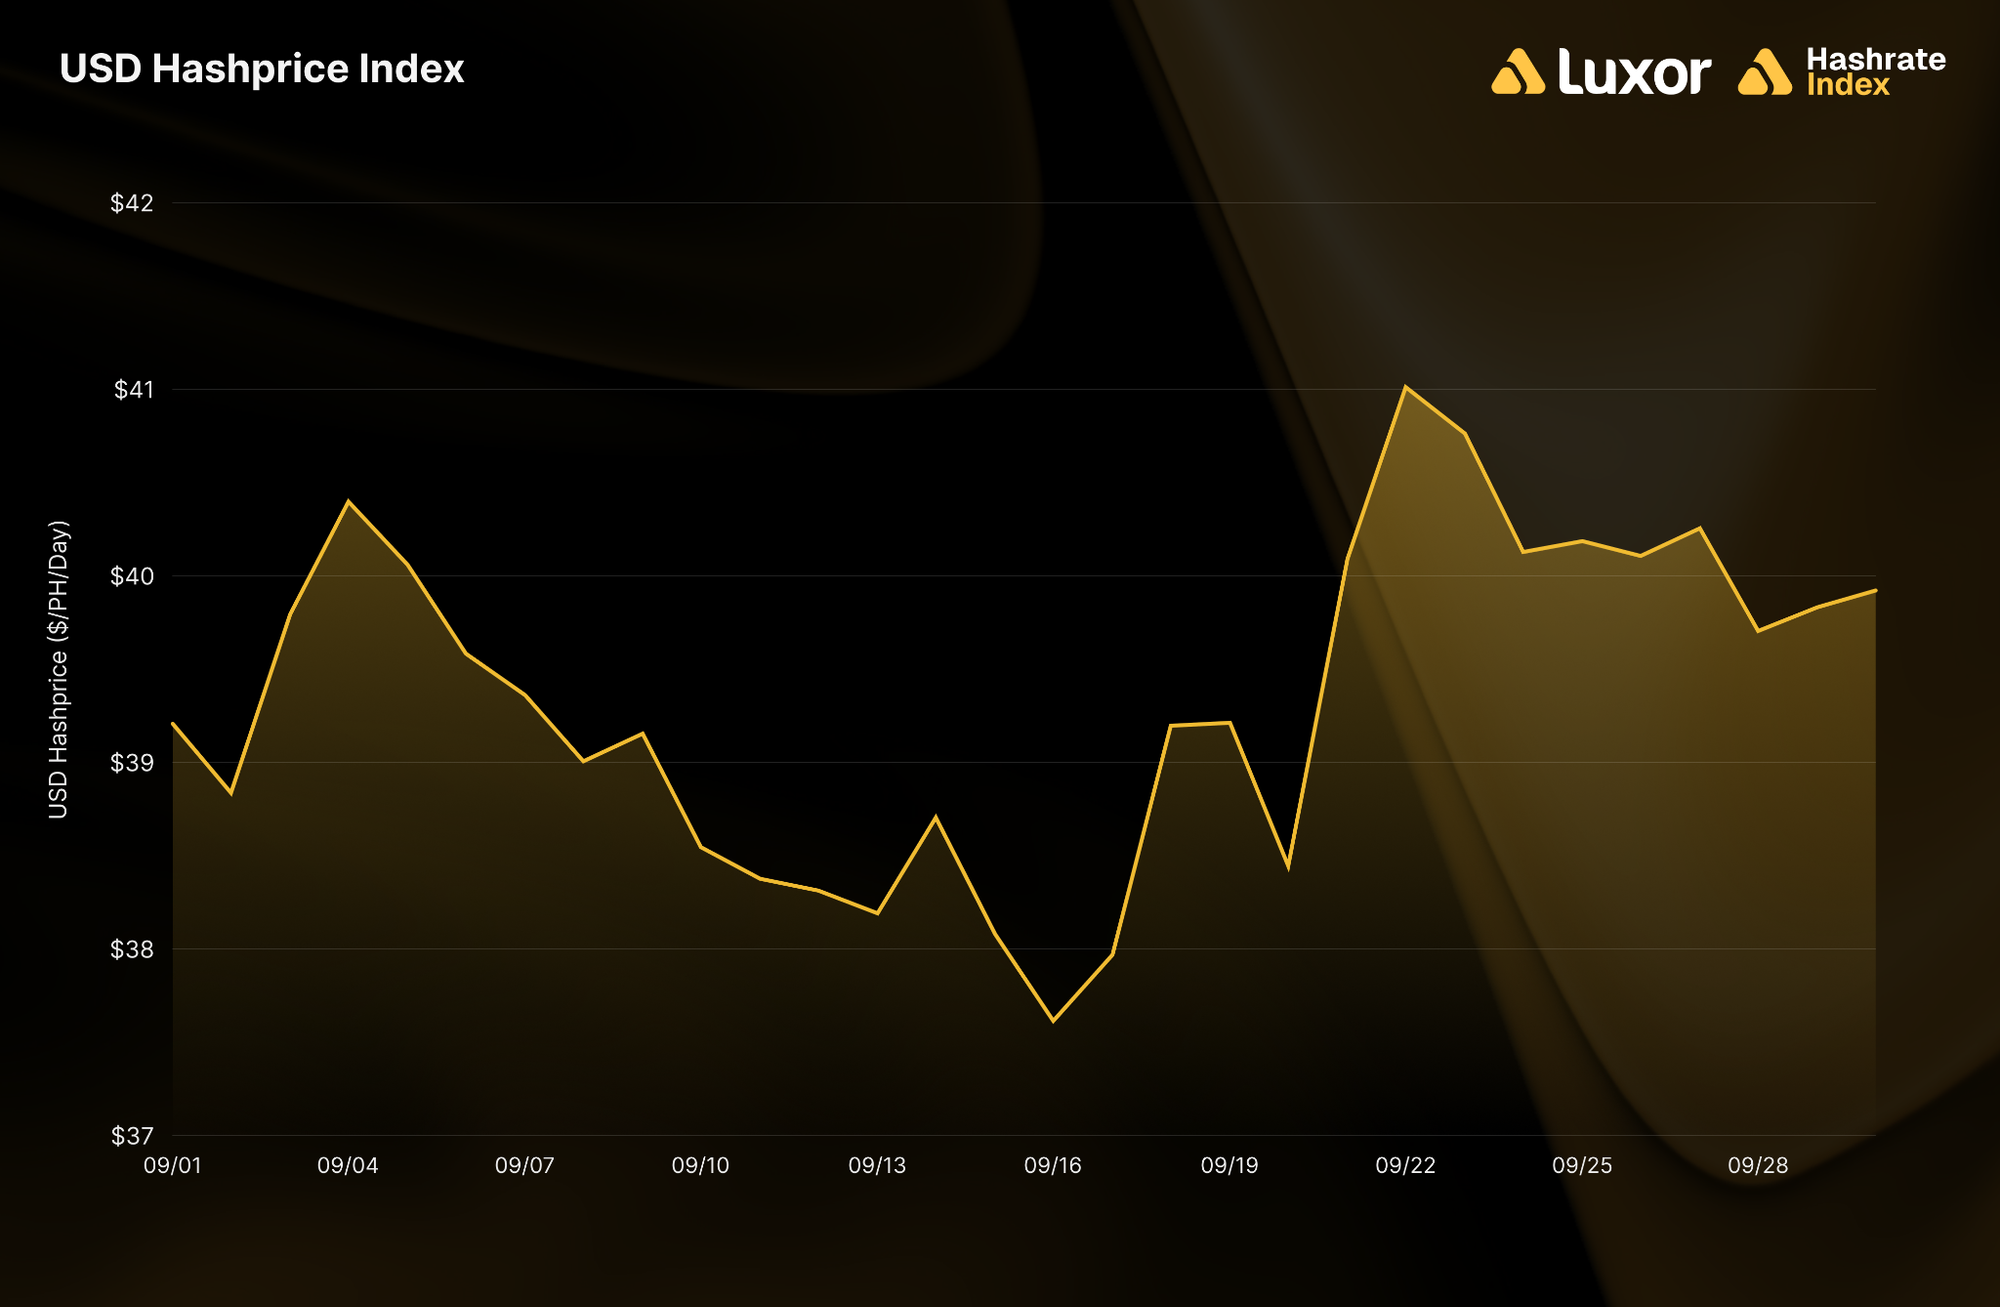
The trading range remained relatively narrow by the volatile standards of 2026. Hashprice dipped to a monthly low of $37.61 on September 16 before climbing to a high of $41.01 six days later. Beneath these headline figures, Bitcoin’s spot price appreciation pushed hashprice upward, while rising network difficulty exerted an opposing downward pressure of nearly equal magnitude.
Bitcoin Price Performance and Macroeconomic Headwinds
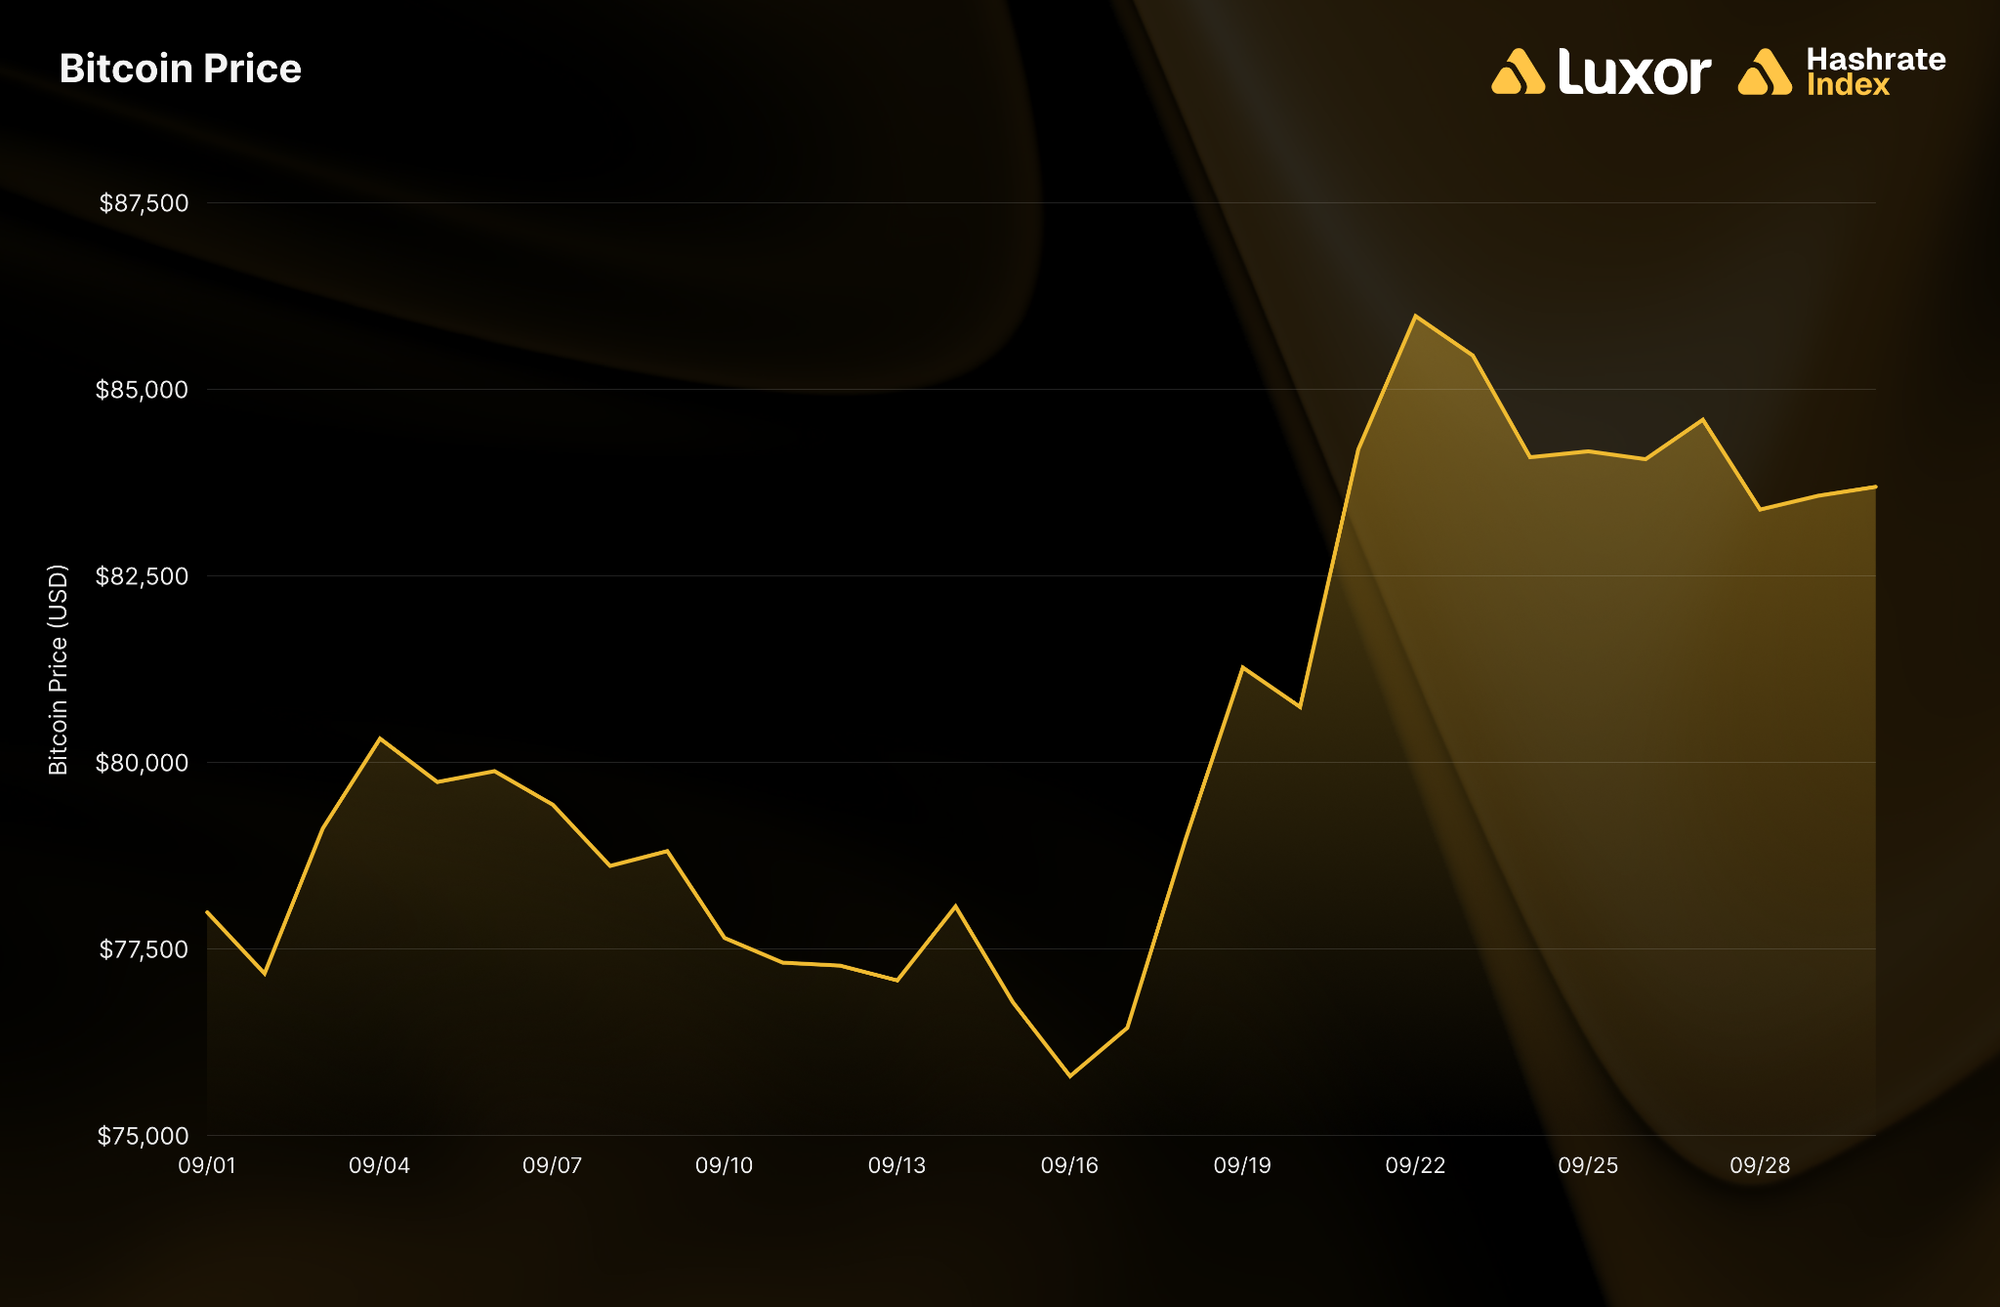
Bitcoin opened September trading at $77,984 and concluded the month at $83,687, notching a 7.3% gain while posting a 16.1% month-over-month increase in its average price to $80,386. The asset reached a monthly peak of $85,973 on September 22.
The market weathered two major scheduled risk events within a turbulent 24-hour window, both of which exerted downward pressure on digital assets. On September 15, the United States Senate failed to invoke cloture on the Clarity Act with 41 votes against the motion, effectively shelving the legislation for the remainder of 2026. The following day, the Federal Open Market Committee (FOMC) unanimously raised interest rates by 25 basis points to a target range of 3.75% to 4.00%, marking the central bank’s first rate hike since July 2023. Bitcoin plummeted to its monthly low of $75,791 on the day of the rate announcement.
Despite these headwinds, the market rebounded swiftly. Between September 16 and September 22, Bitcoin surged 13.4% to reach $85,973, marking its largest six-day rally since the August breakout. Spot exchange-traded funds played a pivotal role in this recovery, pulling in $999 million on September 21—the largest single-day inflow of the year and the highest since October 2025. Total monthly ETF inflows reached $2.65 billion, pushing net flows for 2026 back into positive territory. According to estimates from Bloomberg Intelligence, the average U.S. spot ETF holder returned to a profitable cost basis for the first time since January.
At its closing price of $83,687, Bitcoin finished September down 32.8% from its October 6, 2025 all-time high of $124,485, an improvement from the 37.1% drawdown recorded at the end of August. The asset remained 13.1% below its 2026 high of $96,278 established on January 15. On a quarterly basis, Bitcoin delivered a 41.8% gain, marking its strongest quarterly performance since the final quarter of 2024.
Network Difficulty and Hashrate Expansion
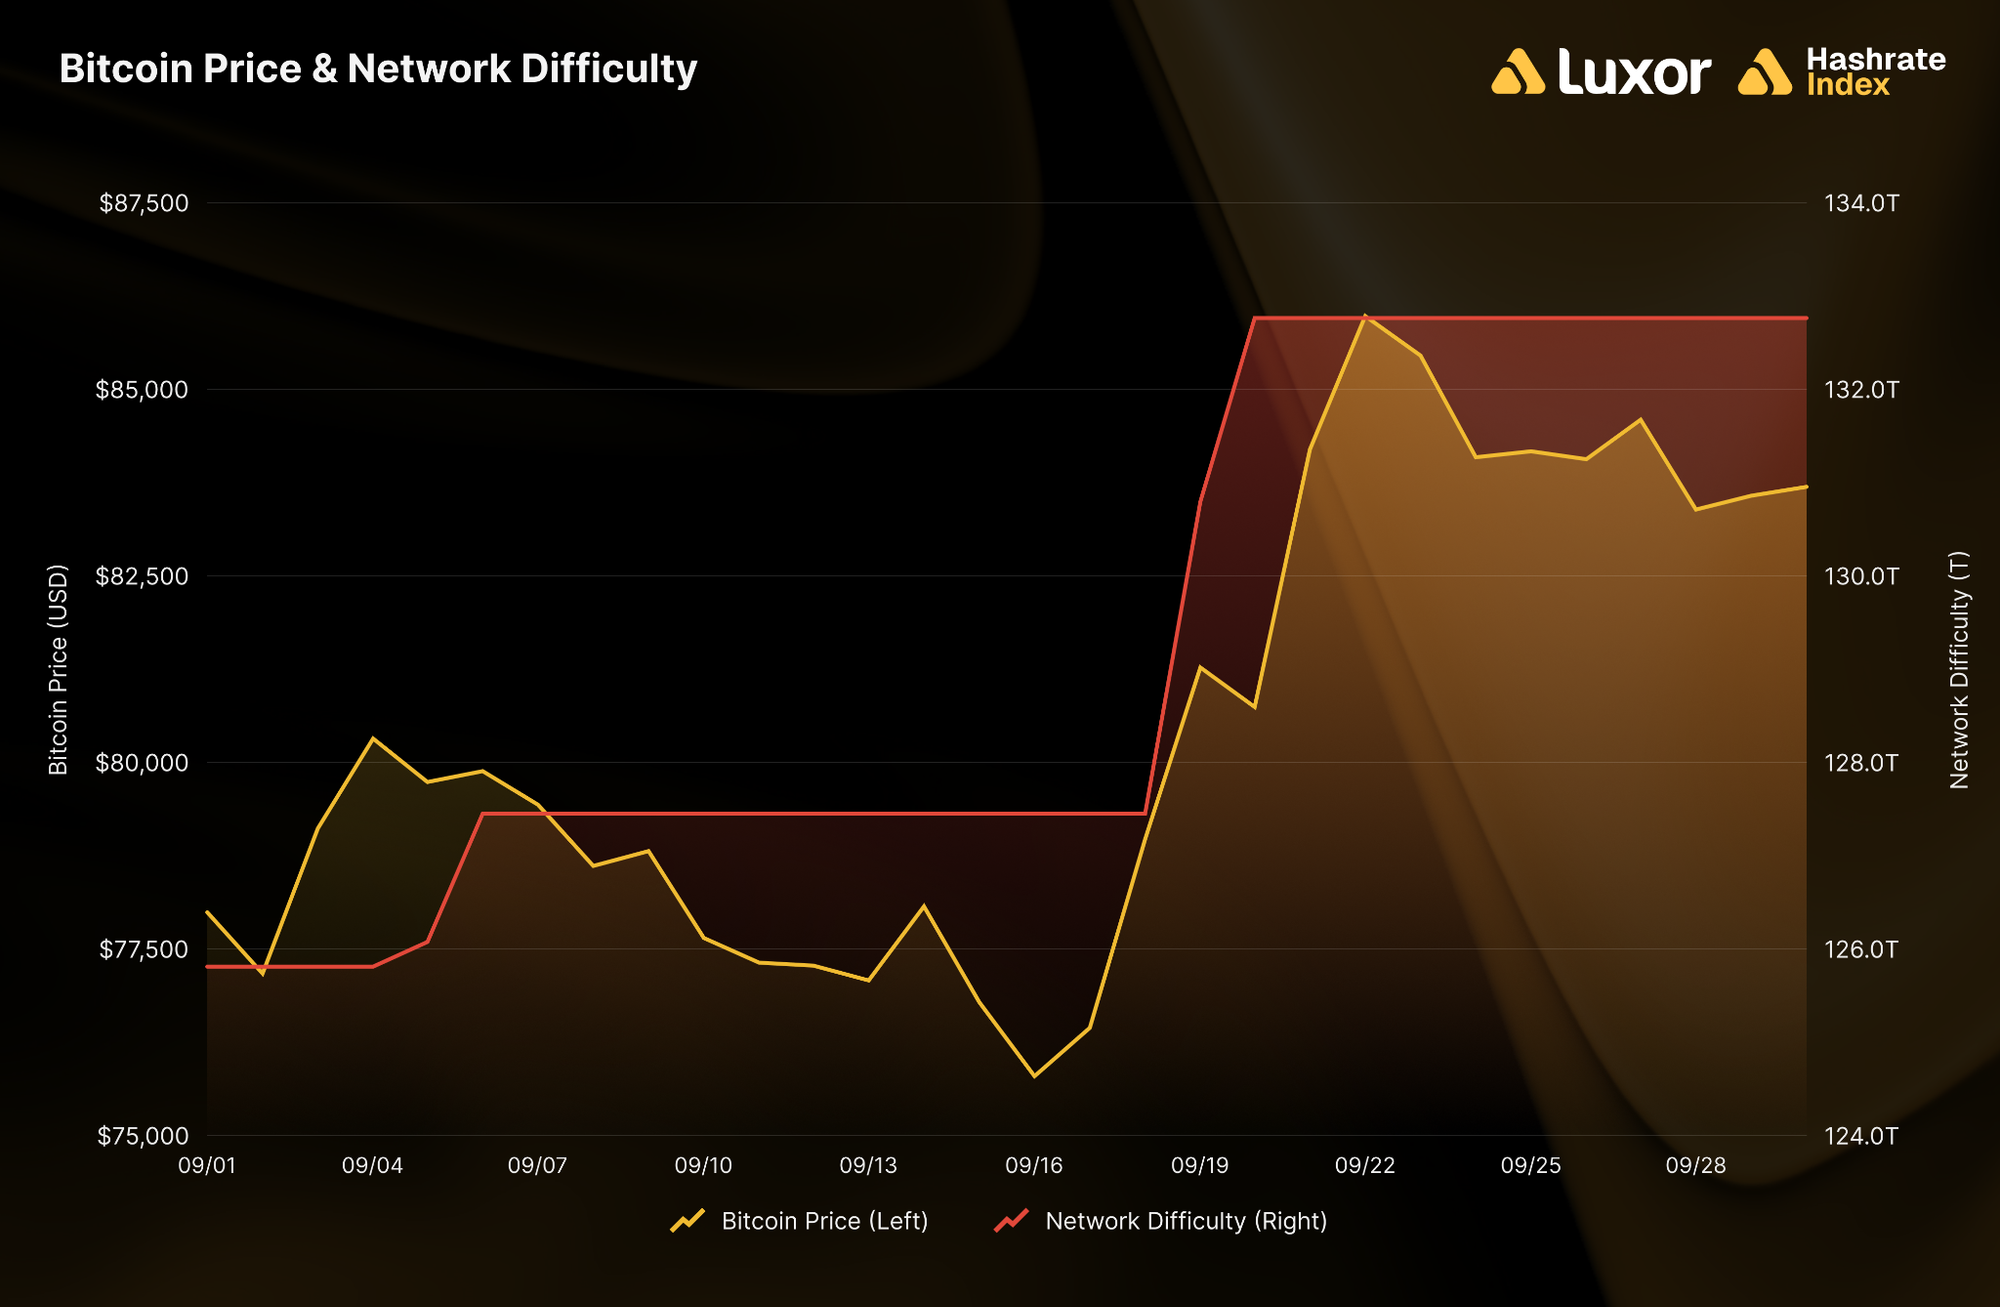
Network difficulty averaged 129.24T, representing a 2.0% increase, and closed the month at 132.76T. Two scheduled adjustments occurred during the period, both resulting in upward revisions: a 1.31% increase on September 5 and a 4.16% hike on September 19, which marked the largest single retarget since late June. With a cumulative net gain of 5.52% across both adjustments, September recorded the steepest month-over-month difficulty growth since October 2025.
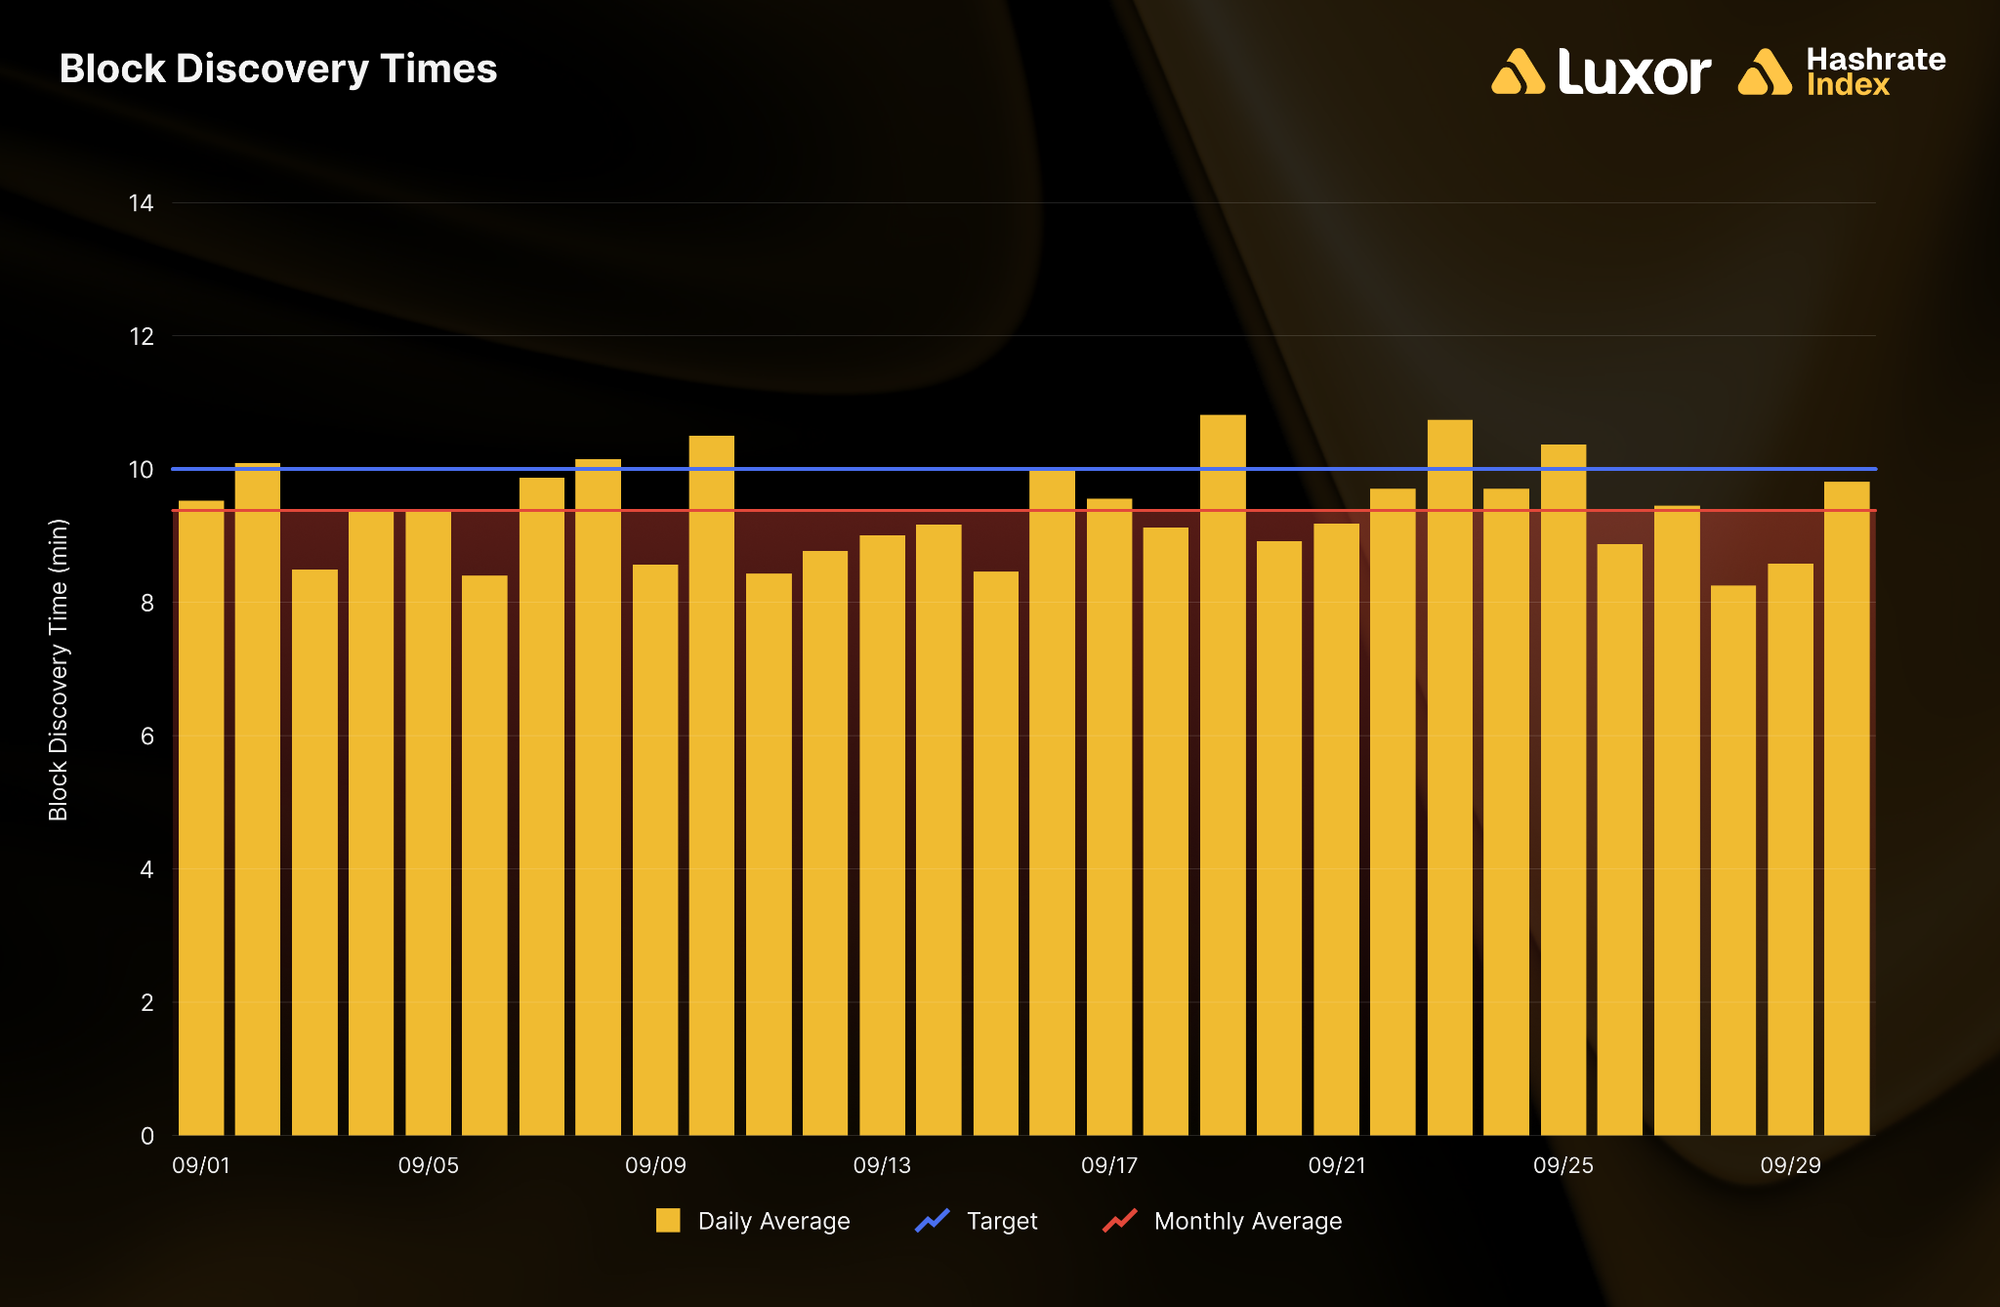
Block times averaged nine minutes and 23 seconds, making it the fastest month for block generation since February, with 23 out of 30 days falling below the standard ten-minute target. As the grueling Texas summer concluded and the seasonal four-coincident-peak (4CP) demand response window closed, hashing power that had previously been curtailed returned to the grid. The seven-day network hashrate average climbed from 926 EH/s to 975 EH/s over the course of the month.
Historical data confirms that ERCOT’s four coincident peaks for the season occurred on June 18, July 22, August 24, and September 12. While July’s peak of 90.96 GW established the seasonal high, September’s peak of 86.49 GW, recorded at 4:30 PM Central Time, served as the final critical interval. Flexible-load clients utilizing energy management services successfully curtailed operations across all four peak intervals, enduring roughly 120 hours of downtime across 47 dispatch days. Given prevailing transmission charges, the financial savings from avoided fees heavily outweighed the mining margins sacrificed during curtailment periods. The 4.16% difficulty adjustment materialized exactly one week after the final grid peak.
Transaction Fees and Revenue Composition
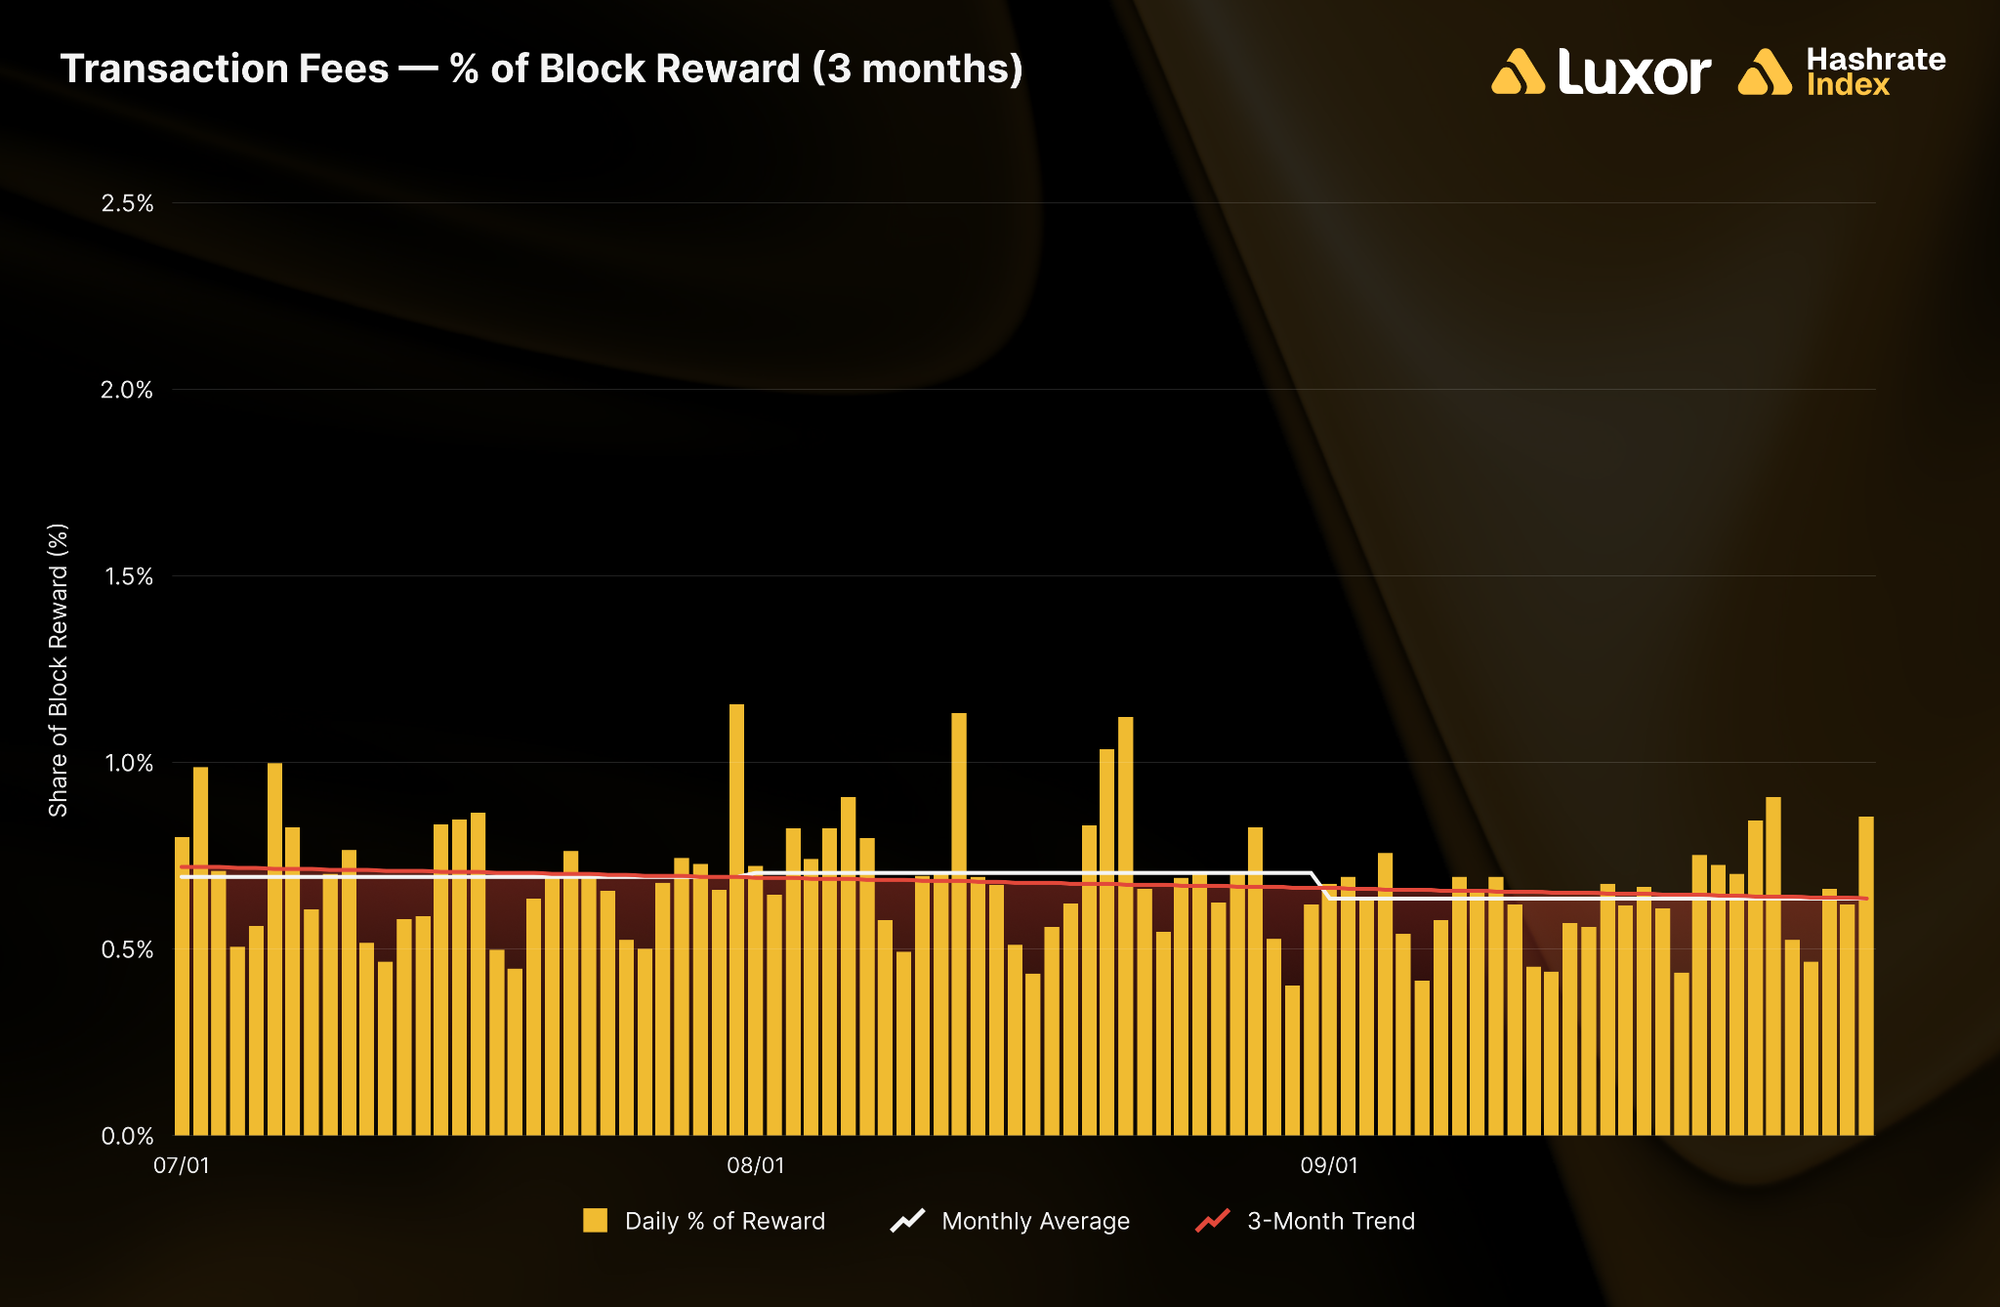
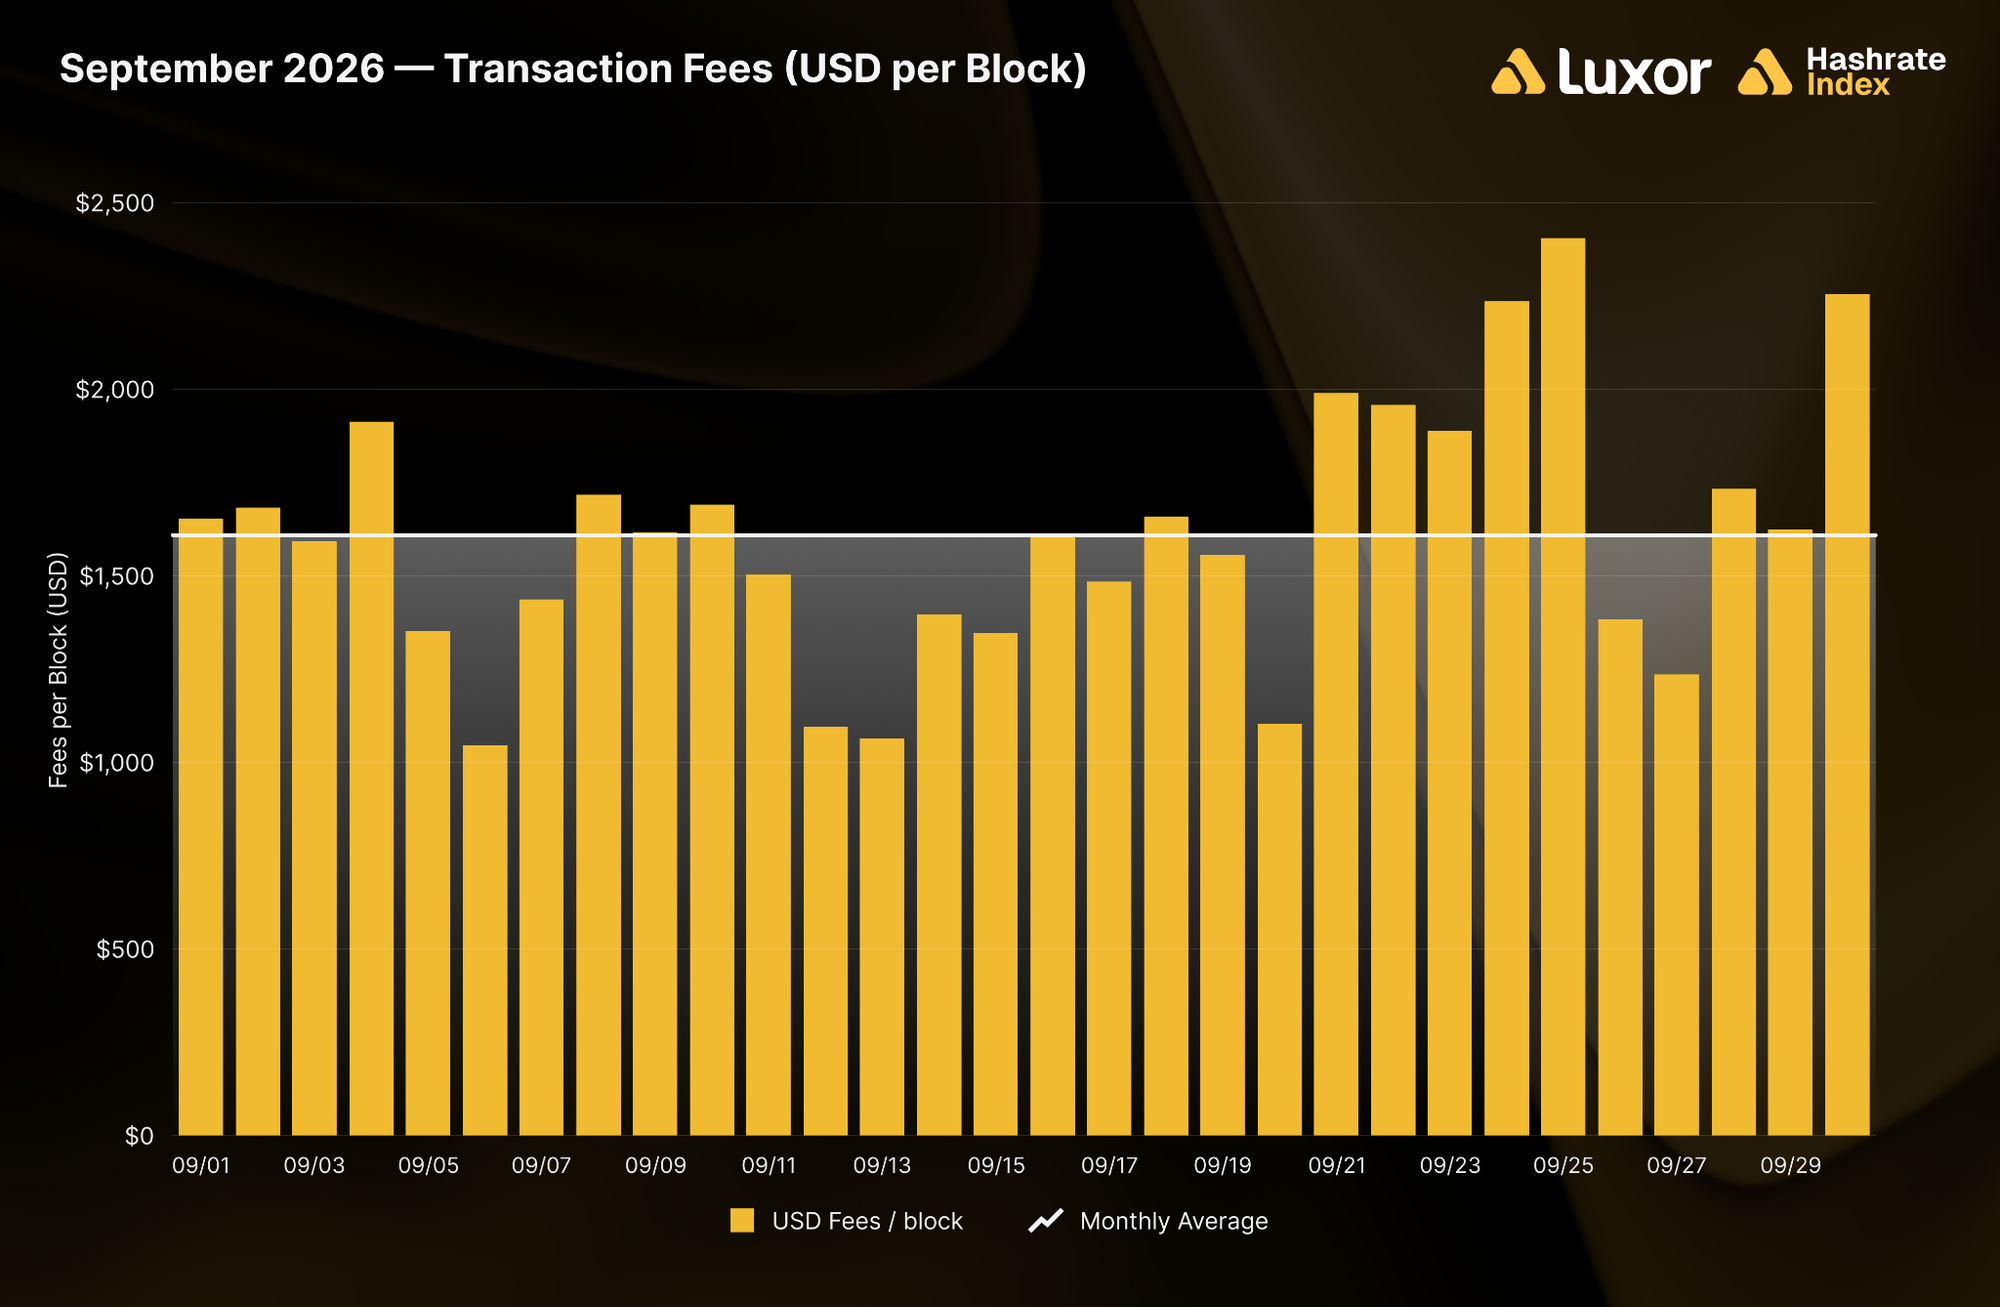
Average transaction fee collections declined by 10.1% to settle at 0.0199 BTC per block, reaching the lowest level observed since May. Fees accounted for a meager 0.63% of total block rewards, marking the fifteenth consecutive month that fee contributions remained below the 1% threshold. Daily fee collections ranged between 0.013 and 0.029 BTC per block, devoid of any significant fee-market outlier blocks. Measured in U.S. dollar terms, the average block generated approximately $1,607 in fees, representing a 4.8% increase driven entirely by Bitcoin’s underlying price appreciation.
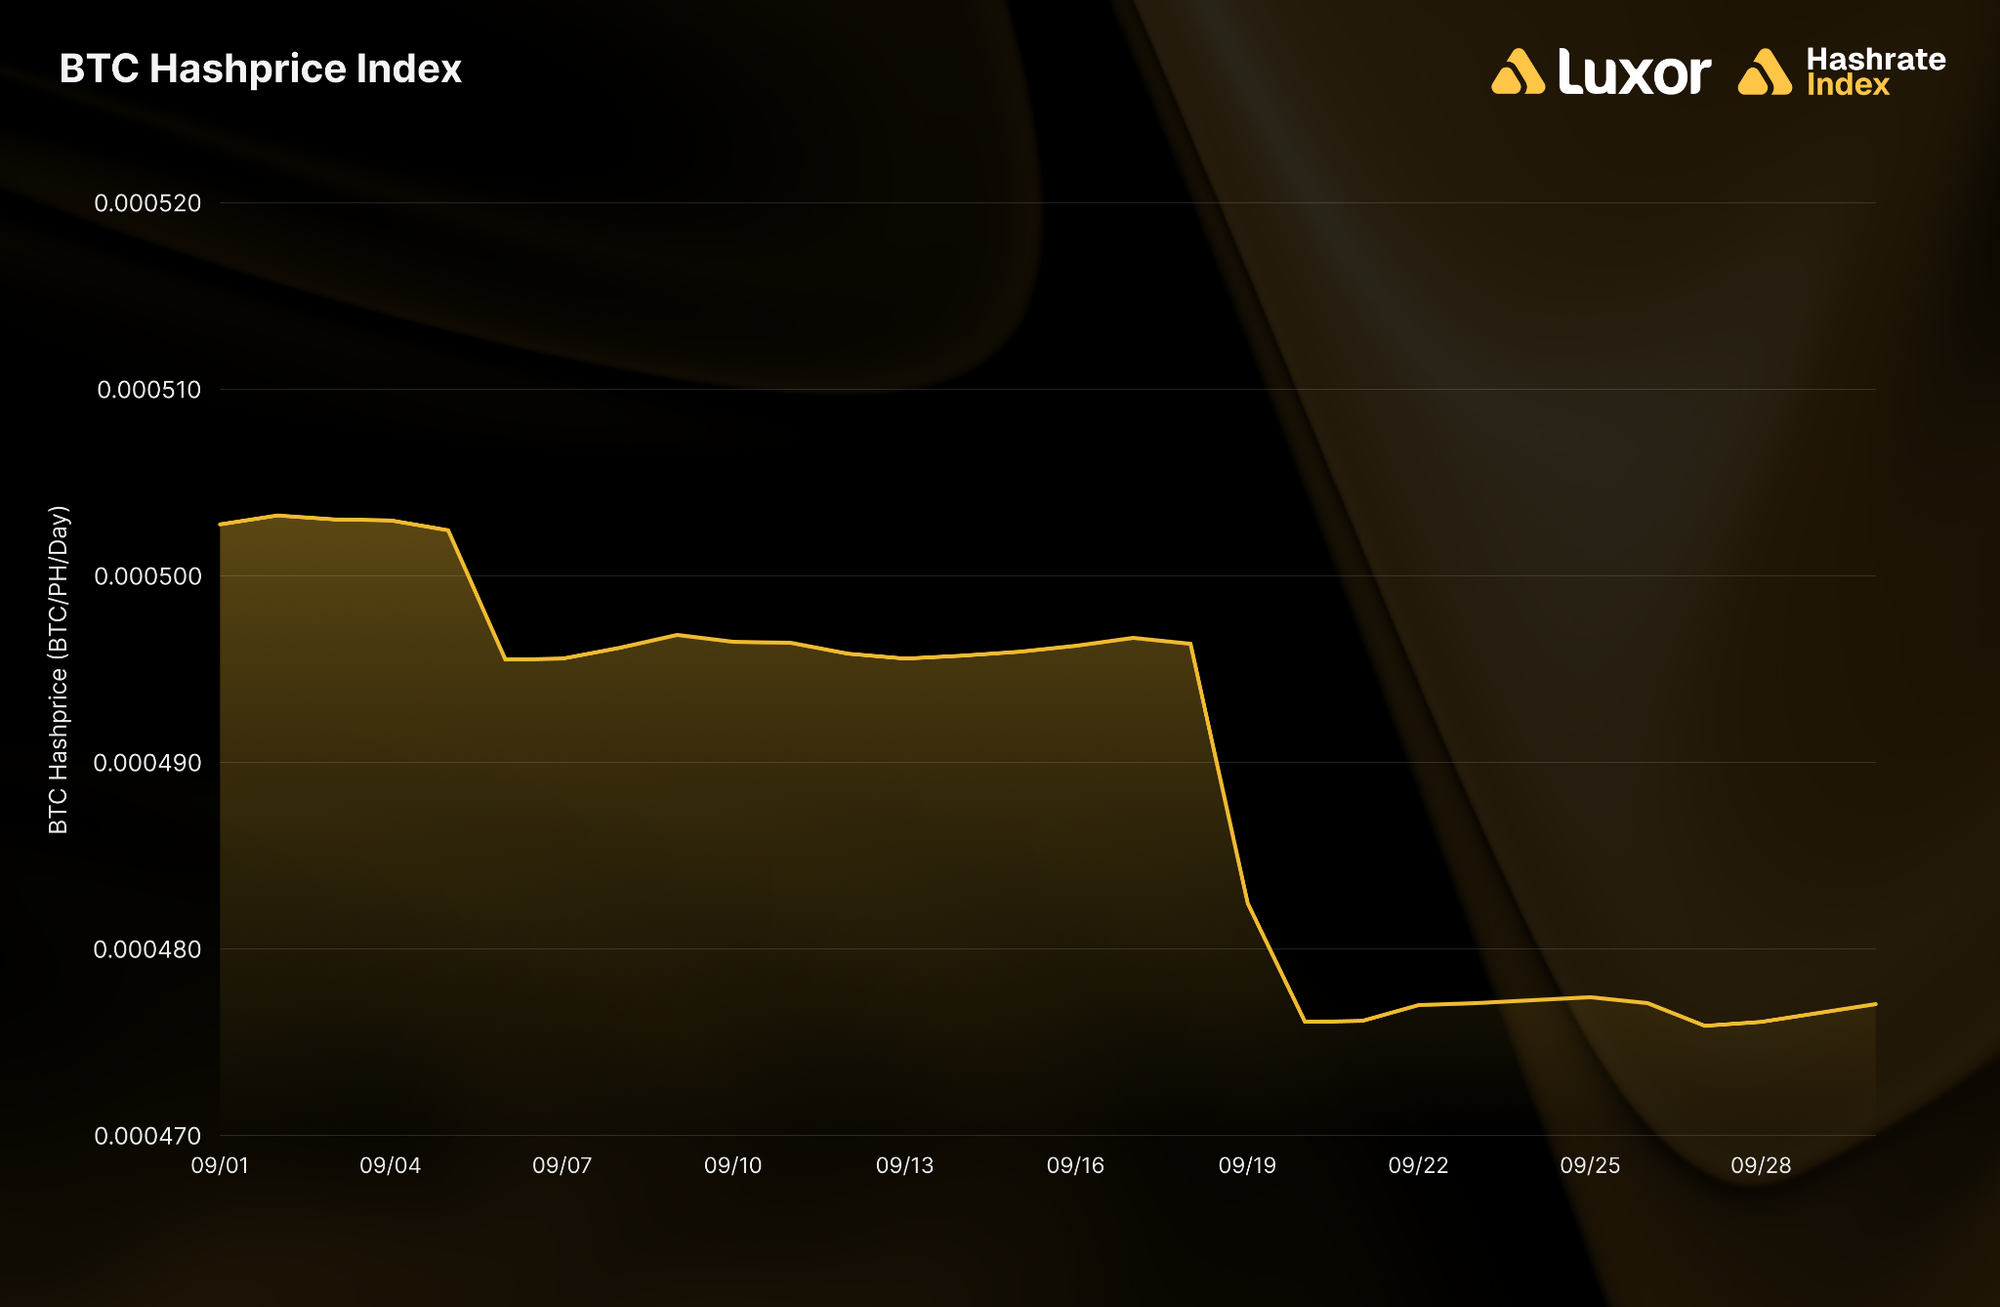
Meanwhile, Bitcoin-denominated hashprice fell 2.0% to average 0.00048965 BTC per PH/s/day. The month opened at 0.00050276 BTC and declined 5.1% to close at 0.00047702 BTC, with each downward step coinciding precisely with a network difficulty retarget. This dynamic mirrored August in reverse, where lower difficulty propelled BTC hashprice to a thirteen-month high before network hashrate expansion reclaimed those gains in September.
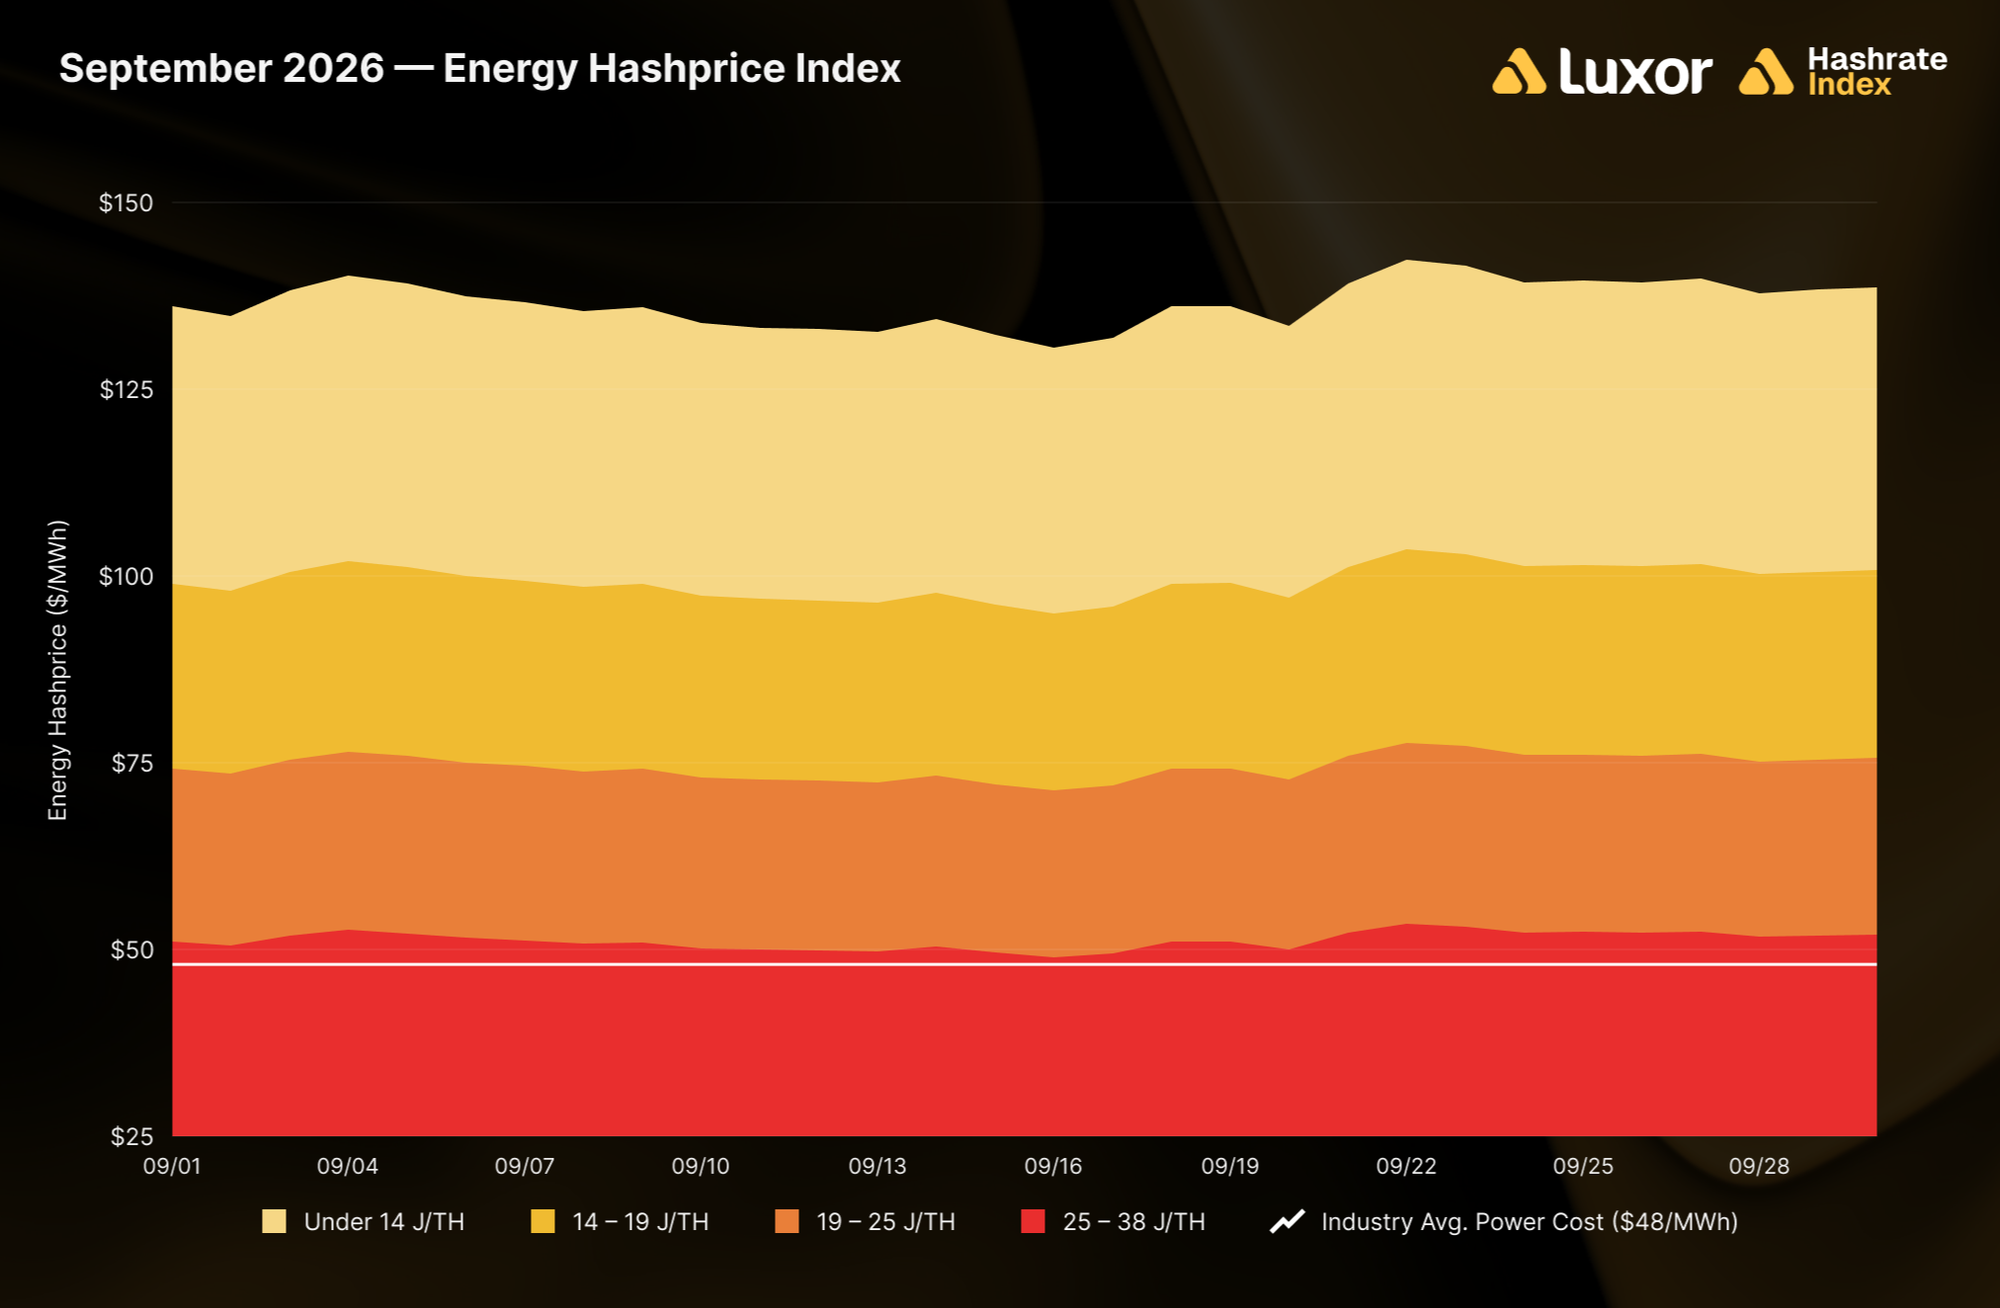
Energy-adjusted hashprice metrics demonstrated uniform growth across all fleet efficiency tiers. Driven by overall hashprice appreciation, each tier’s monthly average rose approximately 13.6%. When evaluated against an average industrial Bitcoin mining power cost of $48 per megawatt-hour, the marginal fleet category consisting of machines operating between 25 and 38 Joules per terahash remained comfortably above $51 per megawatt-hour during every single day of the final week.
Hashrate Market Derivatives and Forward Curve Evolution
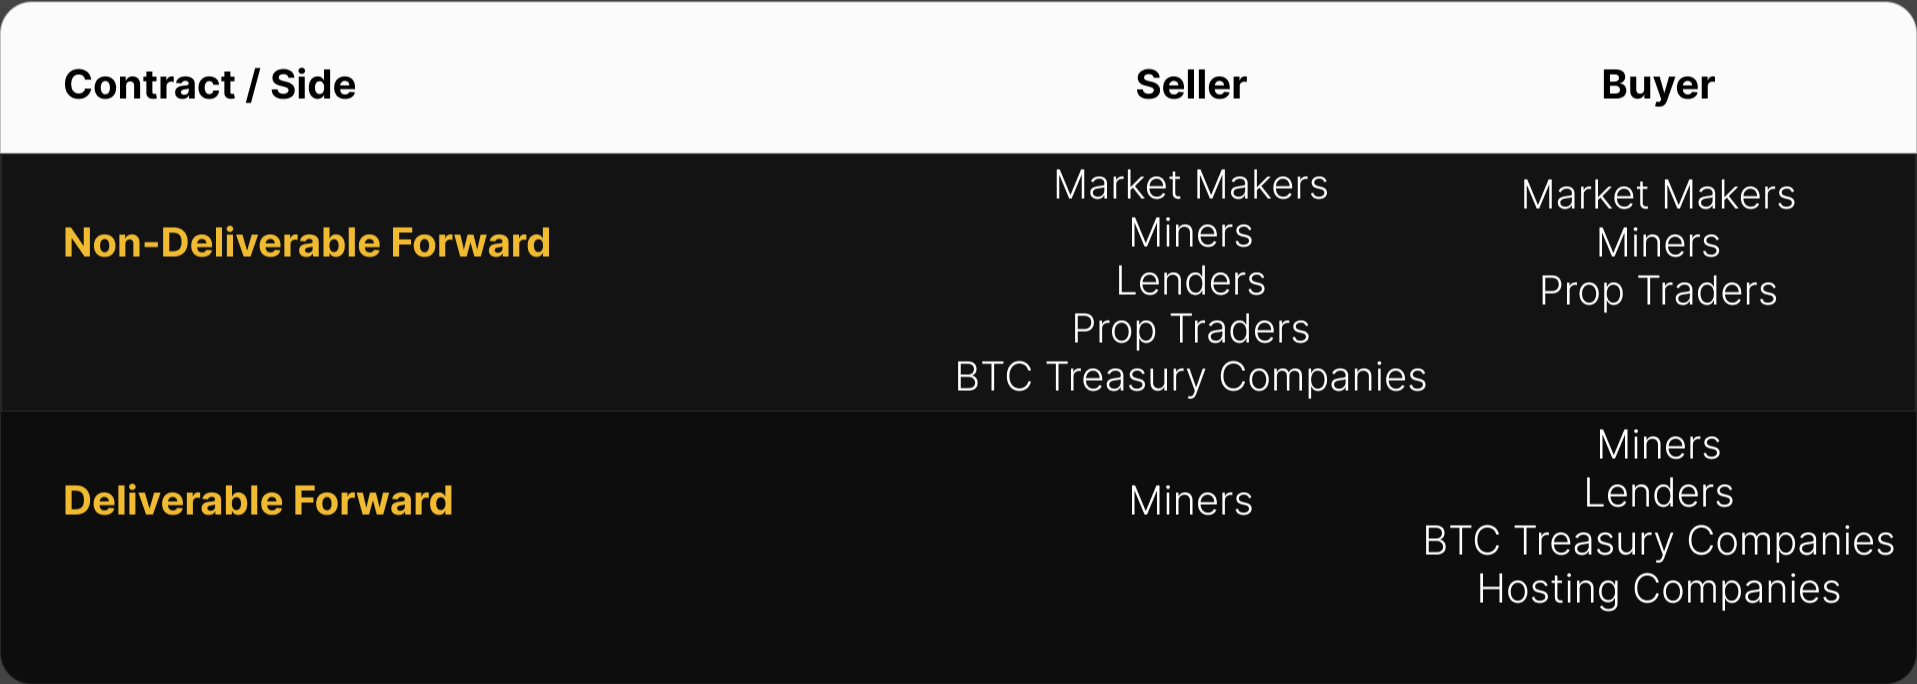
Analysis of the hashrate derivatives market reveals shifting sentiment regarding forward pricing and risk management strategies. Throughout September, lenders actively participated on the buy side of deliverable forward contracts, while public and private mining enterprises utilized the instruments to sell hashrate forward, secure non-dilutive financing, and fund fleet expansion initiatives.
Because deliverable forwards require upfront prepayment, they characteristically trade at a discount to non-deliverable forwards to compensate buyers for credit risk and the cost of capital. Pairing a deliverable forward with an offsetting non-deliverable forward enables institutional lenders and treasury firms to lock in that structural spread as a fixed Bitcoin-denominated yield, while offering miners a predictable cost of capital. In September 2026, this annualized yield ranged between 6% and 13%.
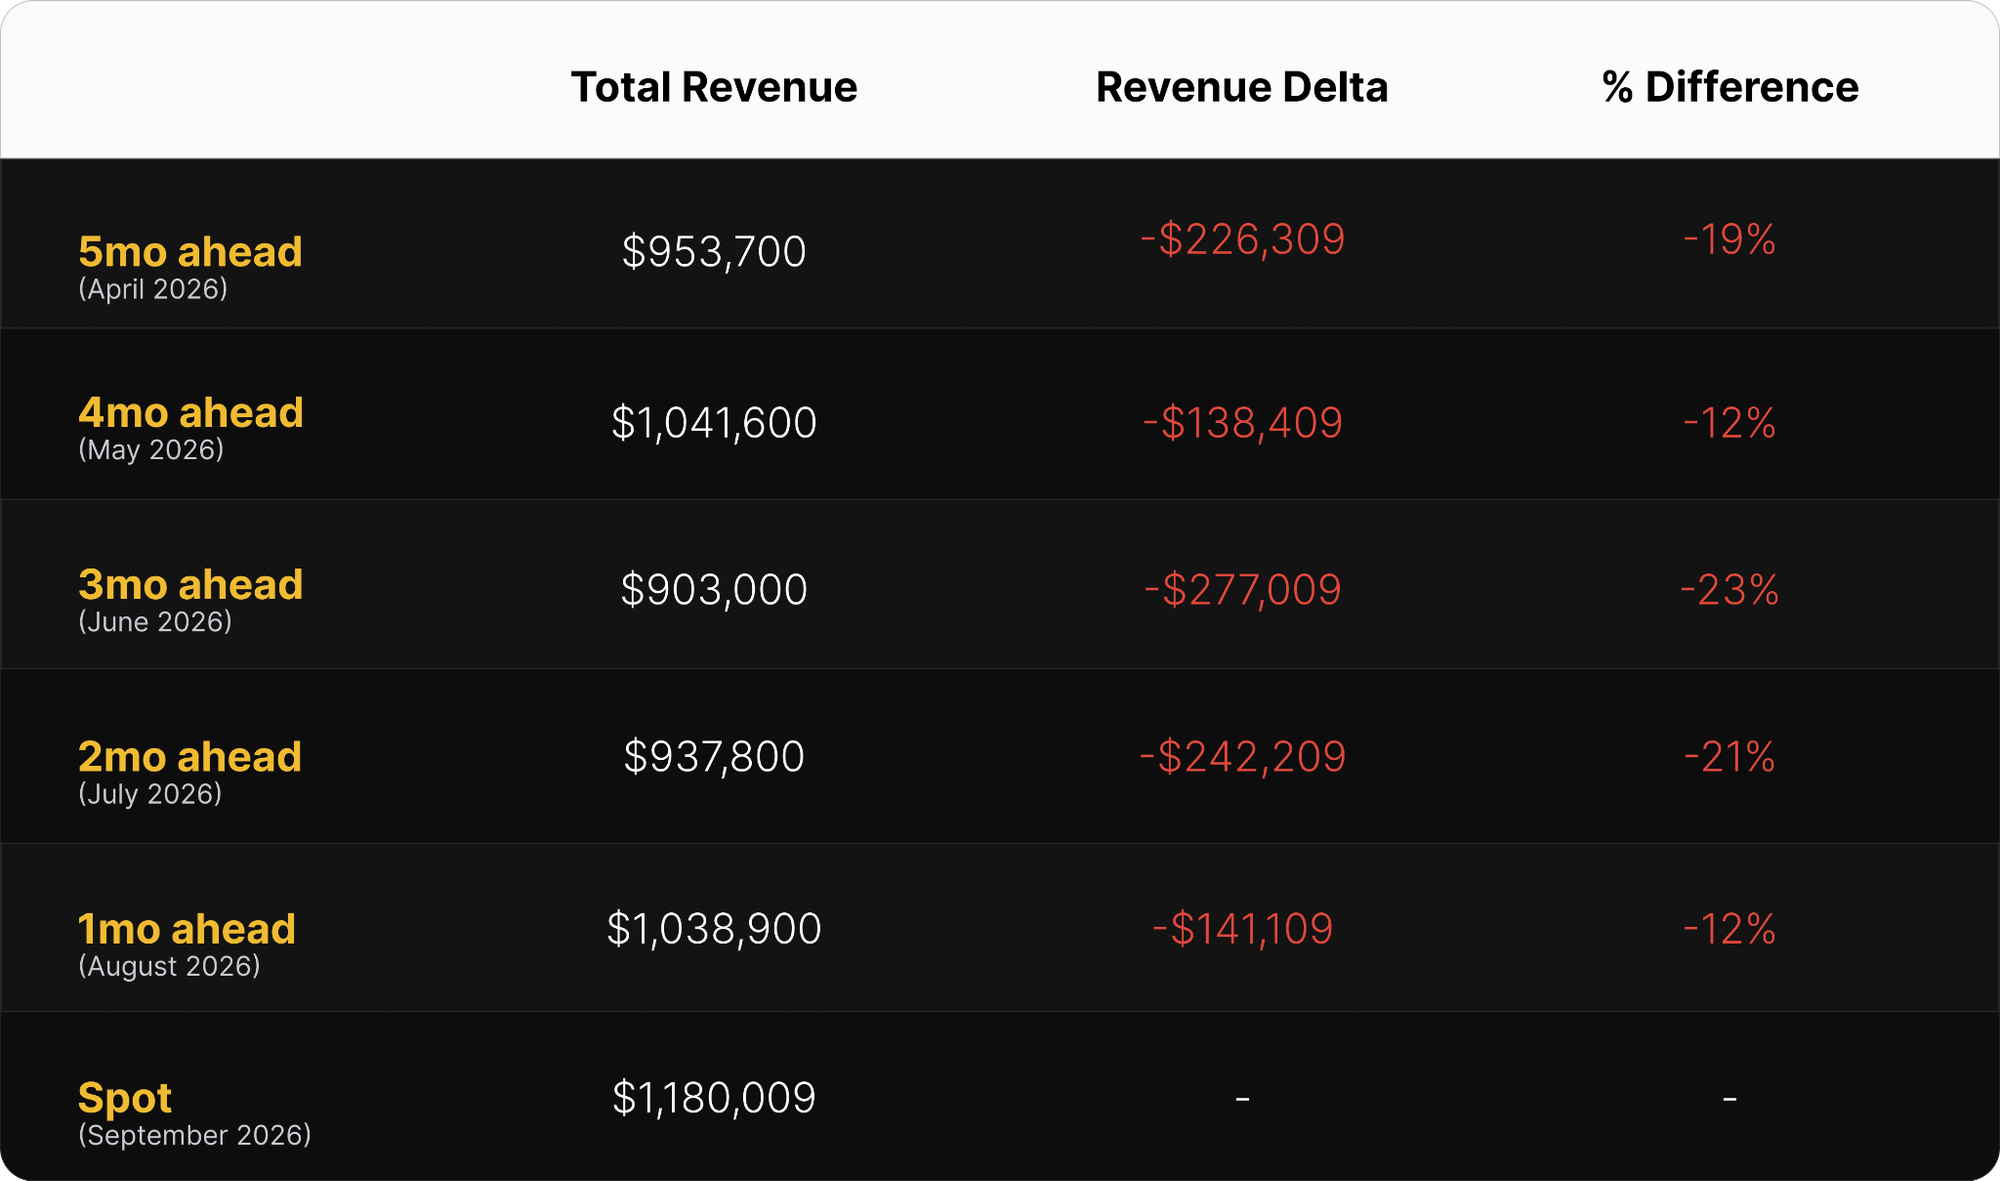
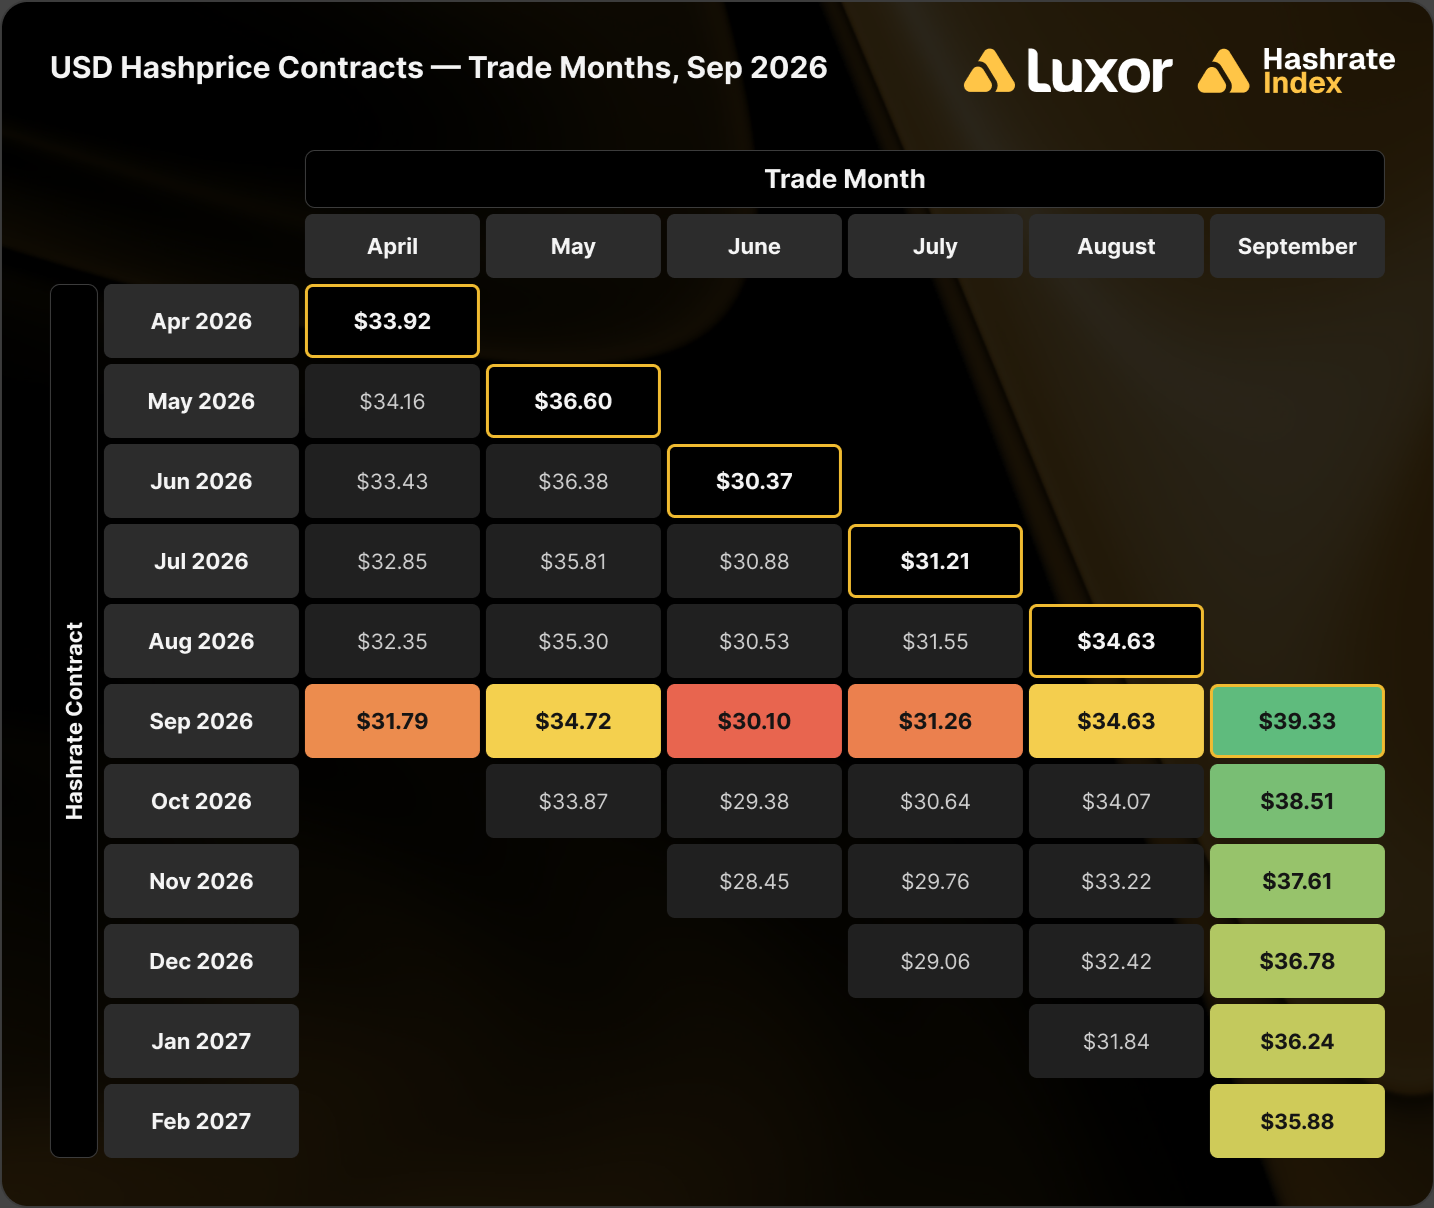
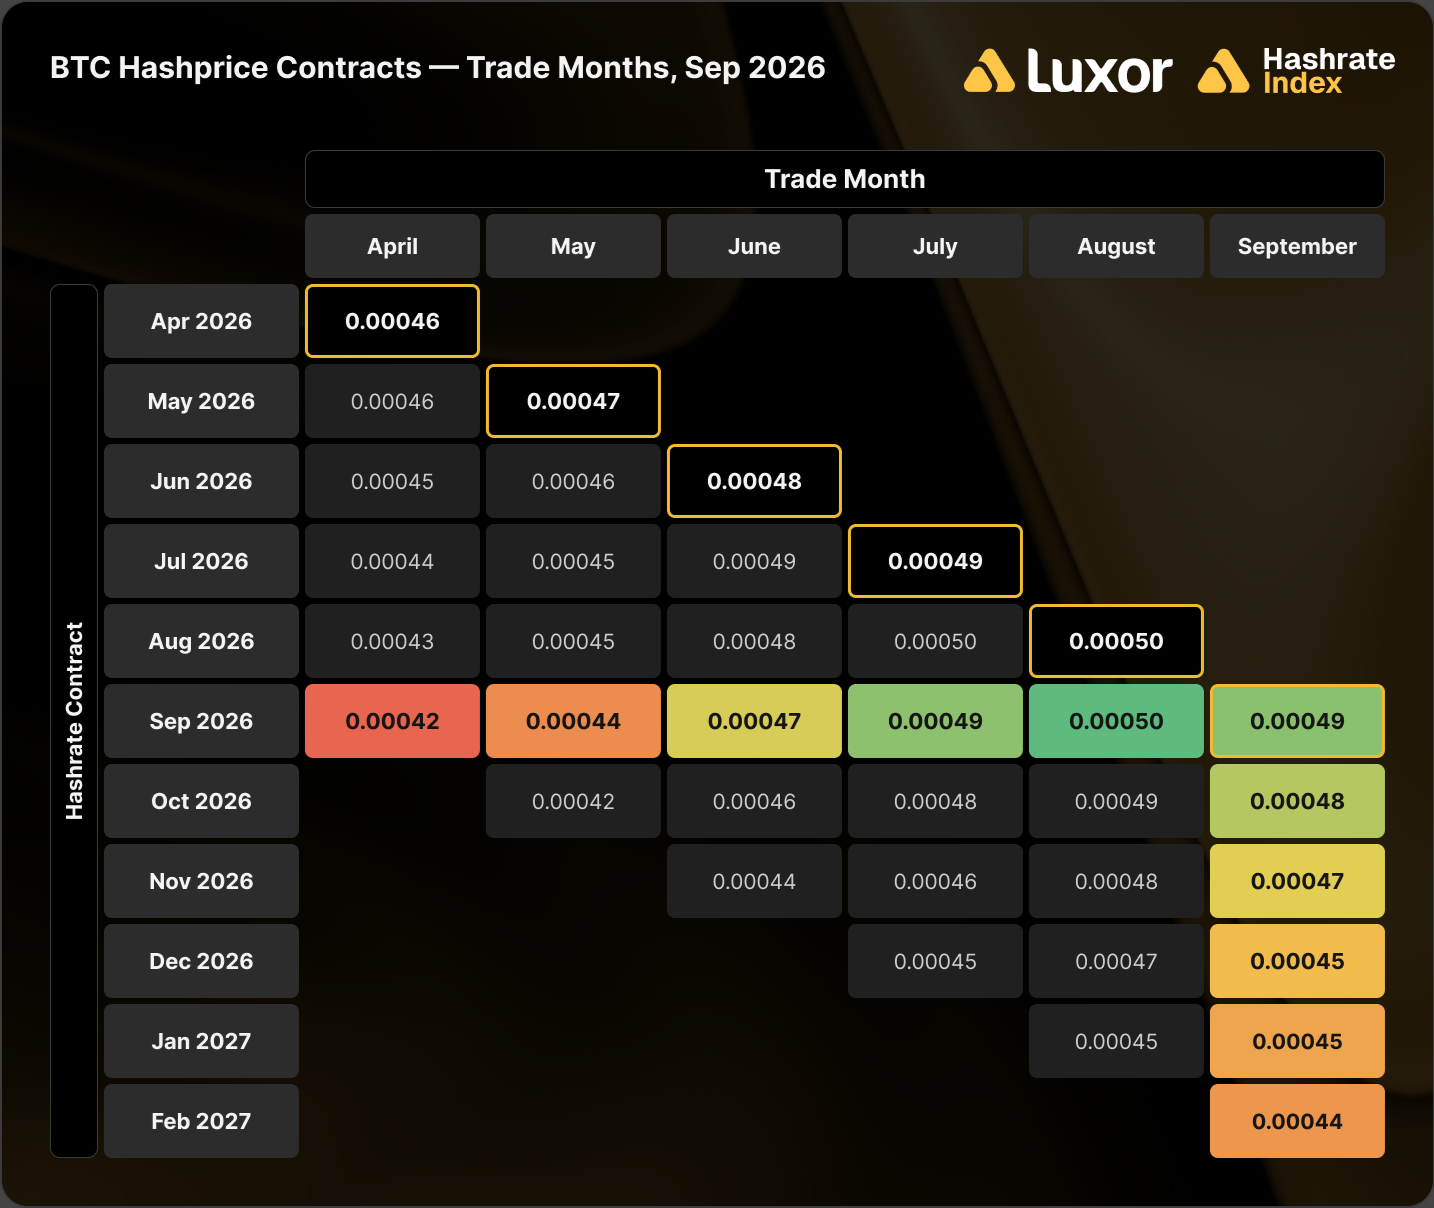
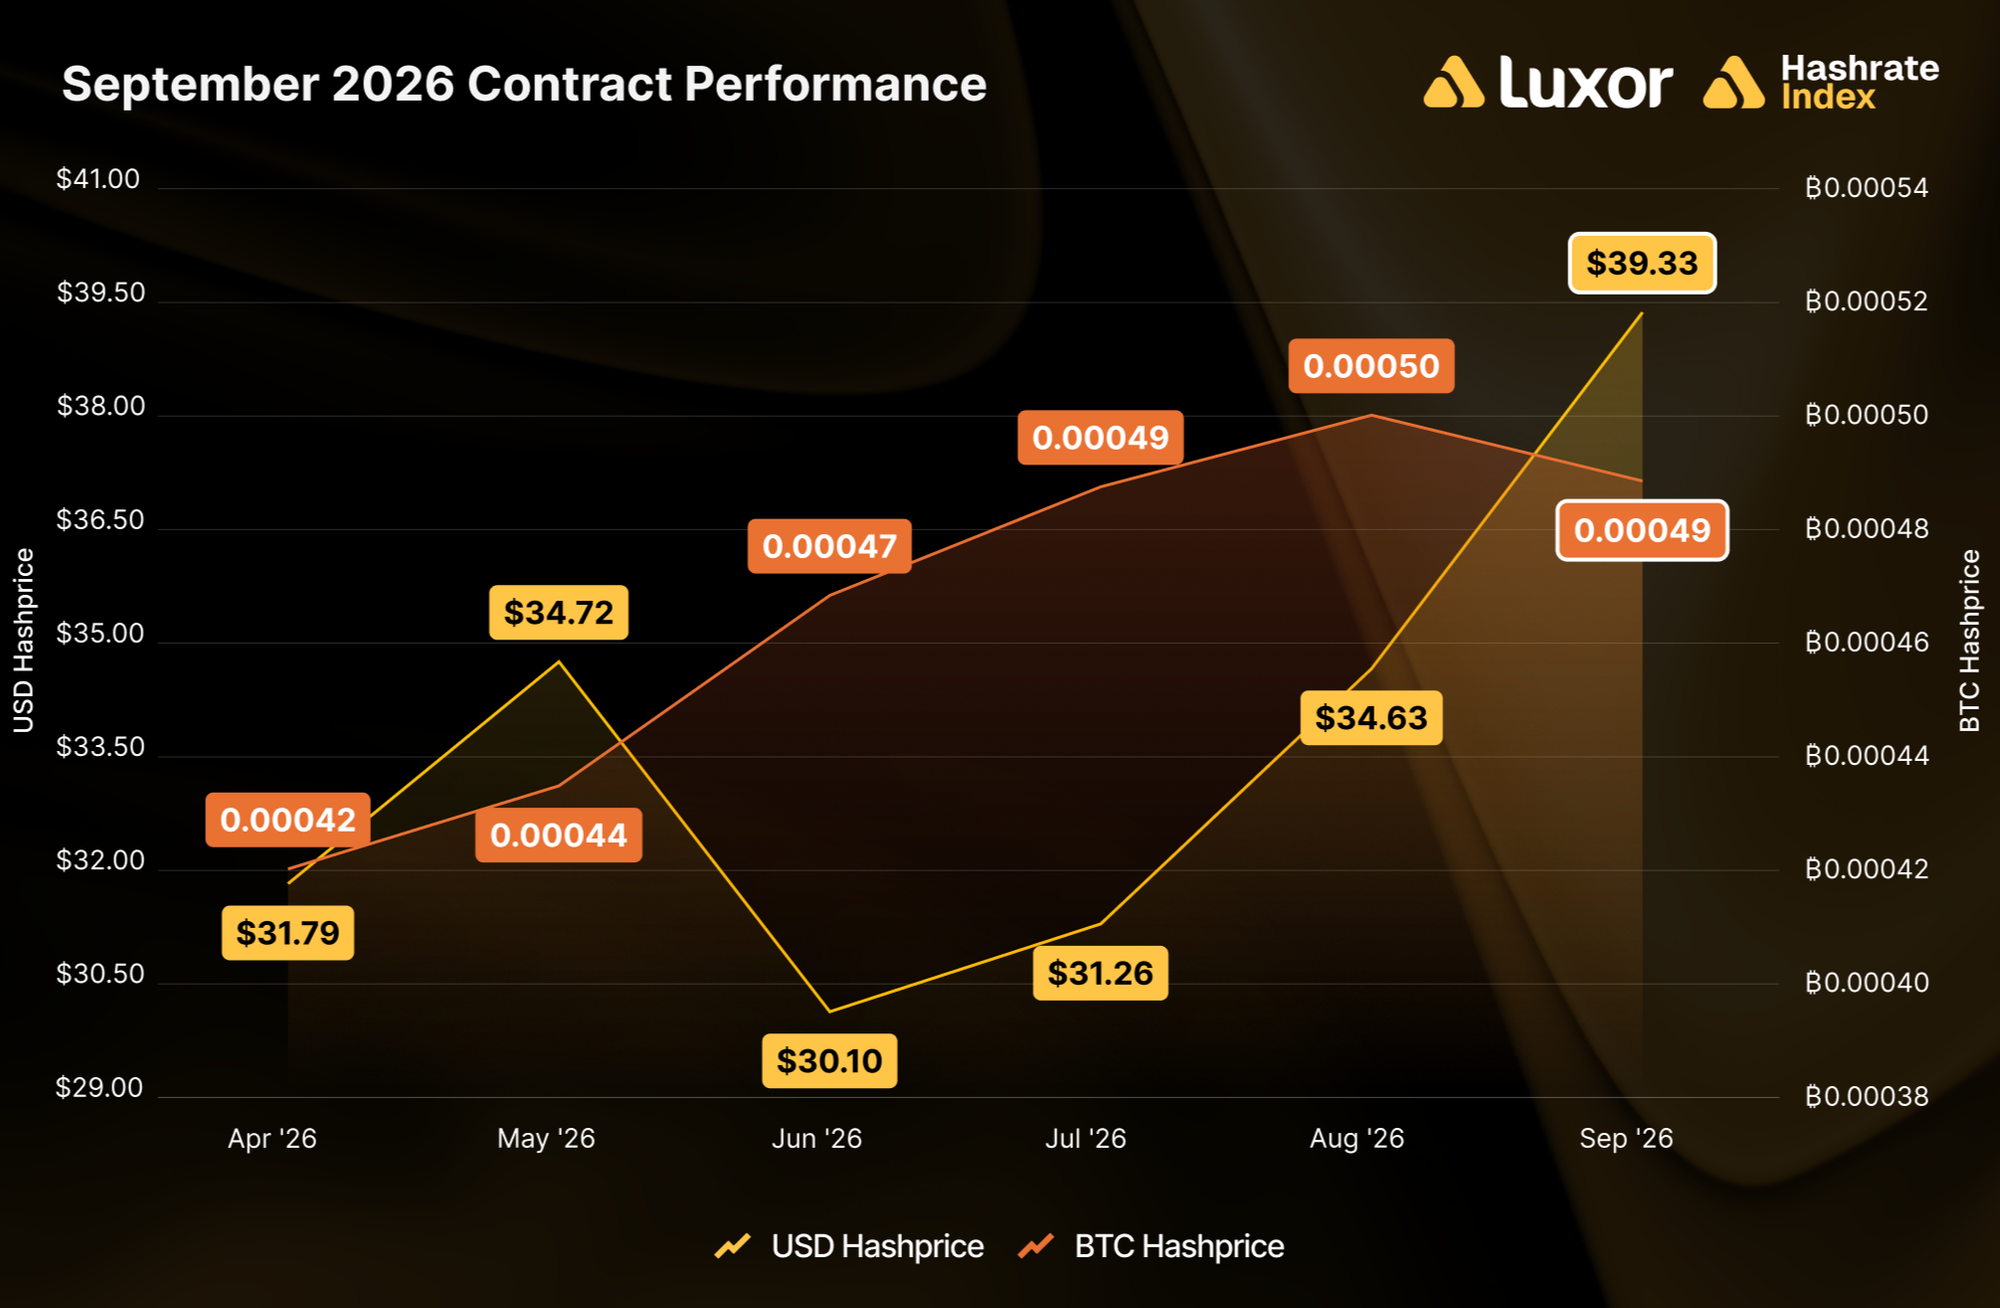
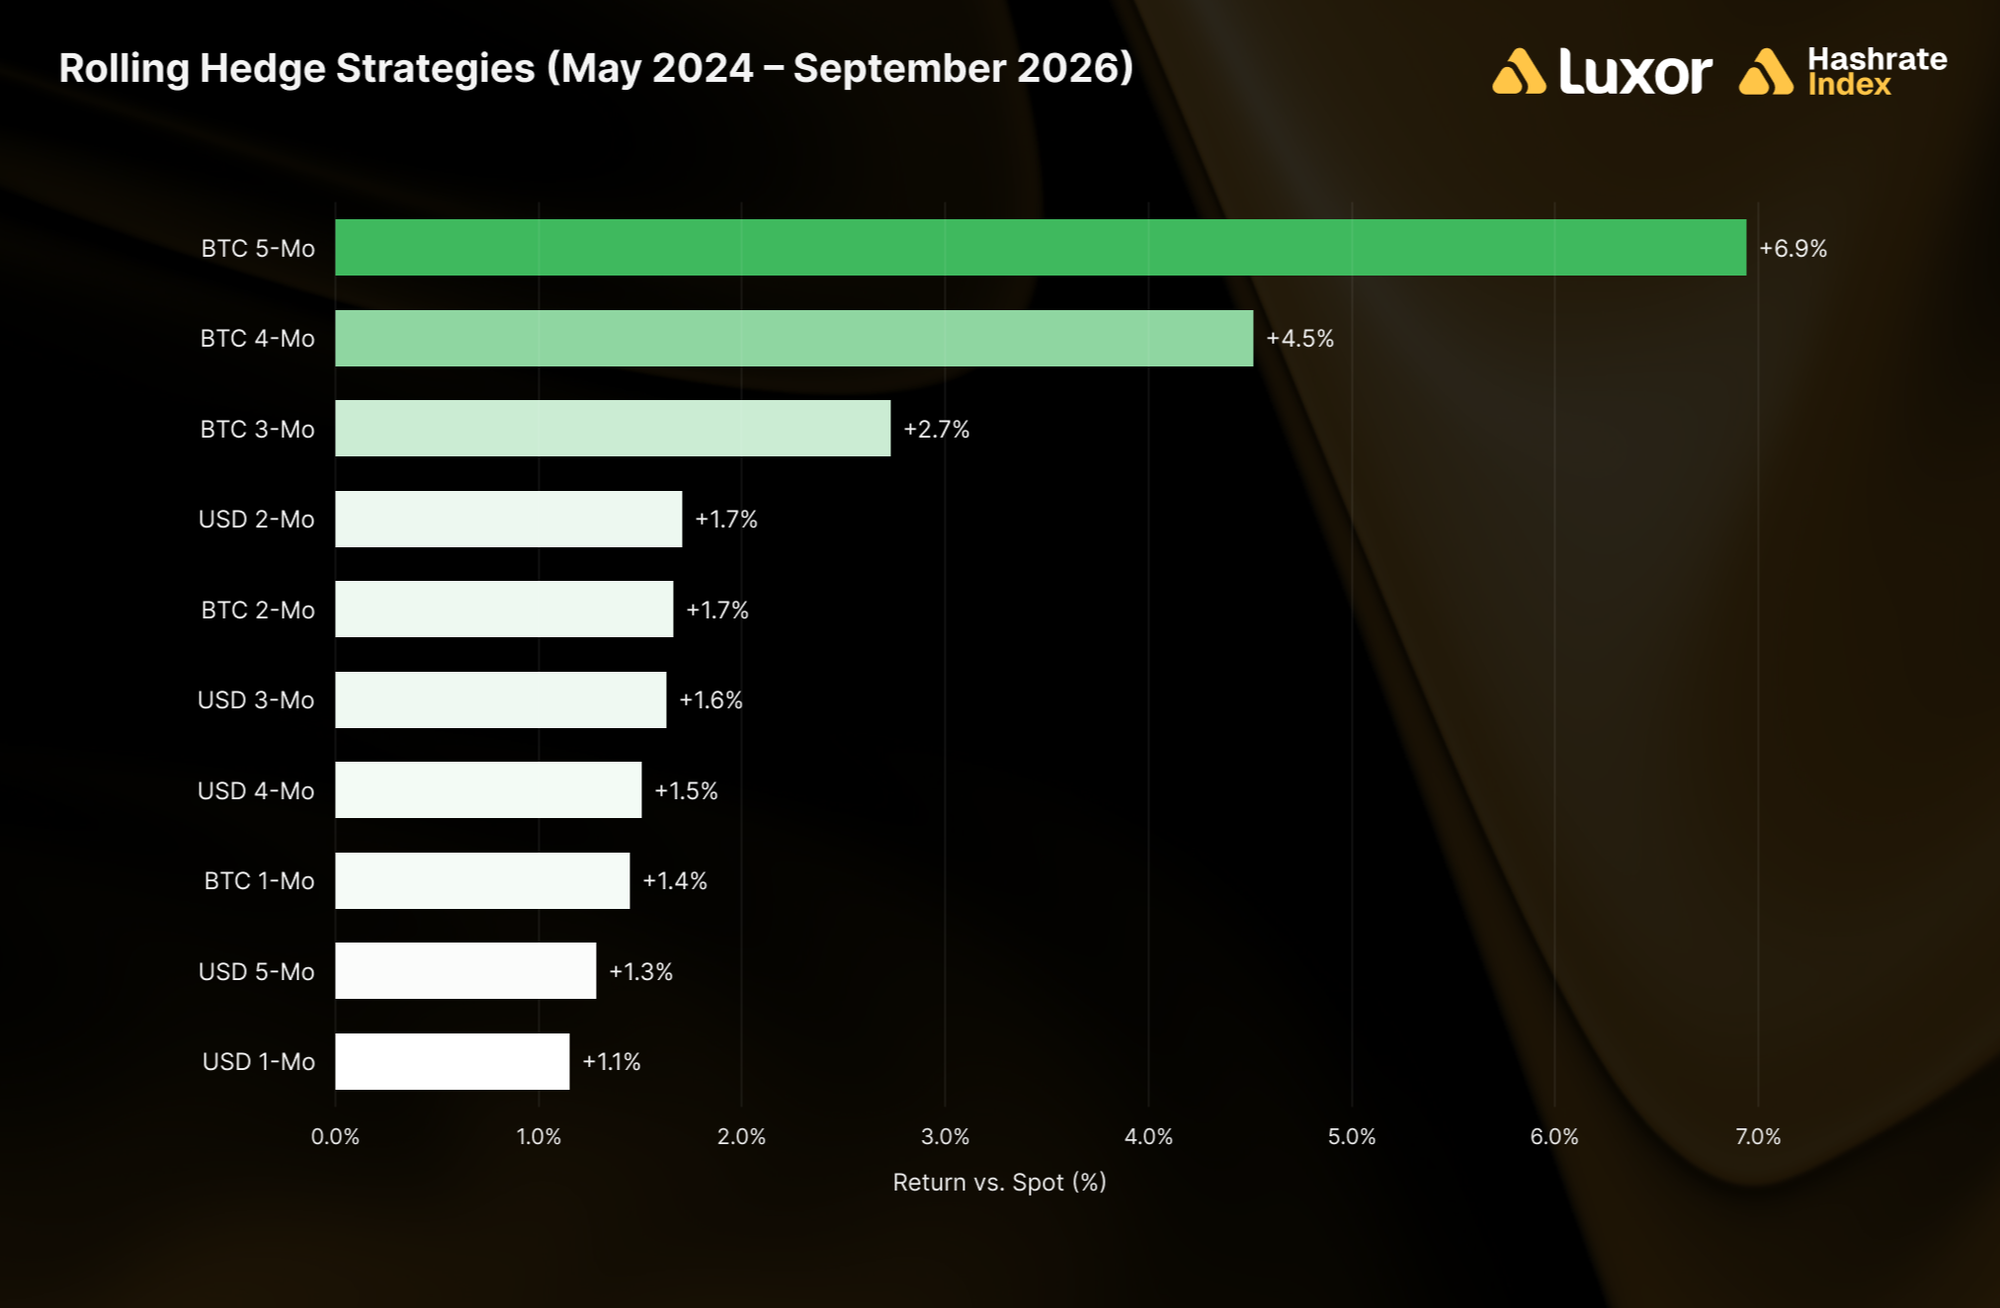
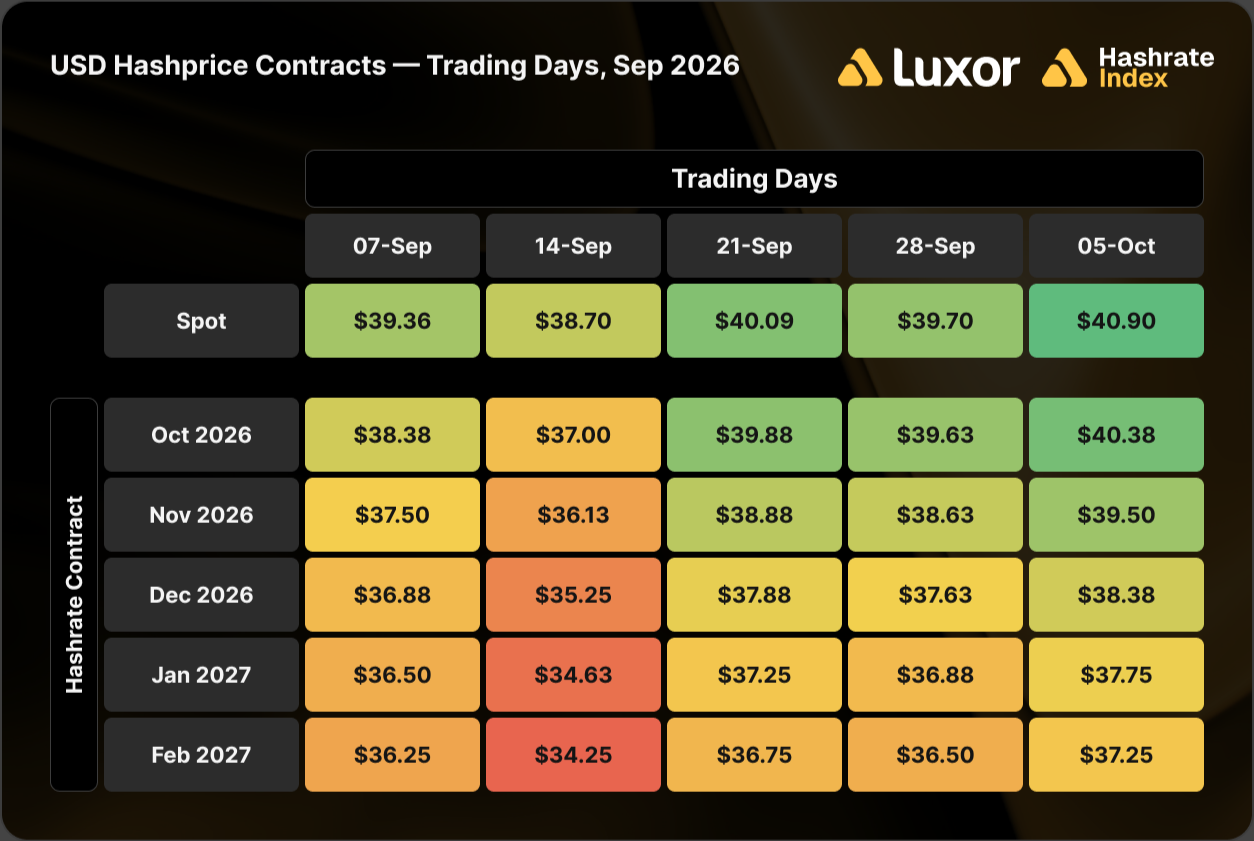
September marked the first month since July 2025 in which all dollar-denominated hedging positions resulted in a loss relative to spot settlements. Sellers of the September USD forward contract locked in rates between $30.10 and $34.72 per PH/s/day, falling well short of the $39.33 spot settlement average. Conversely, the streak of losses for Bitcoin-denominated hedges was temporarily broken: a one-month forward sale executed in August at 0.00050 BTC per PH/s/day outperformed the September spot settlement of 0.00049 BTC by 2.4%. However, longer-term hedging horizons spanning two to five months underperformed spot settlements, continuing a trend established in January.
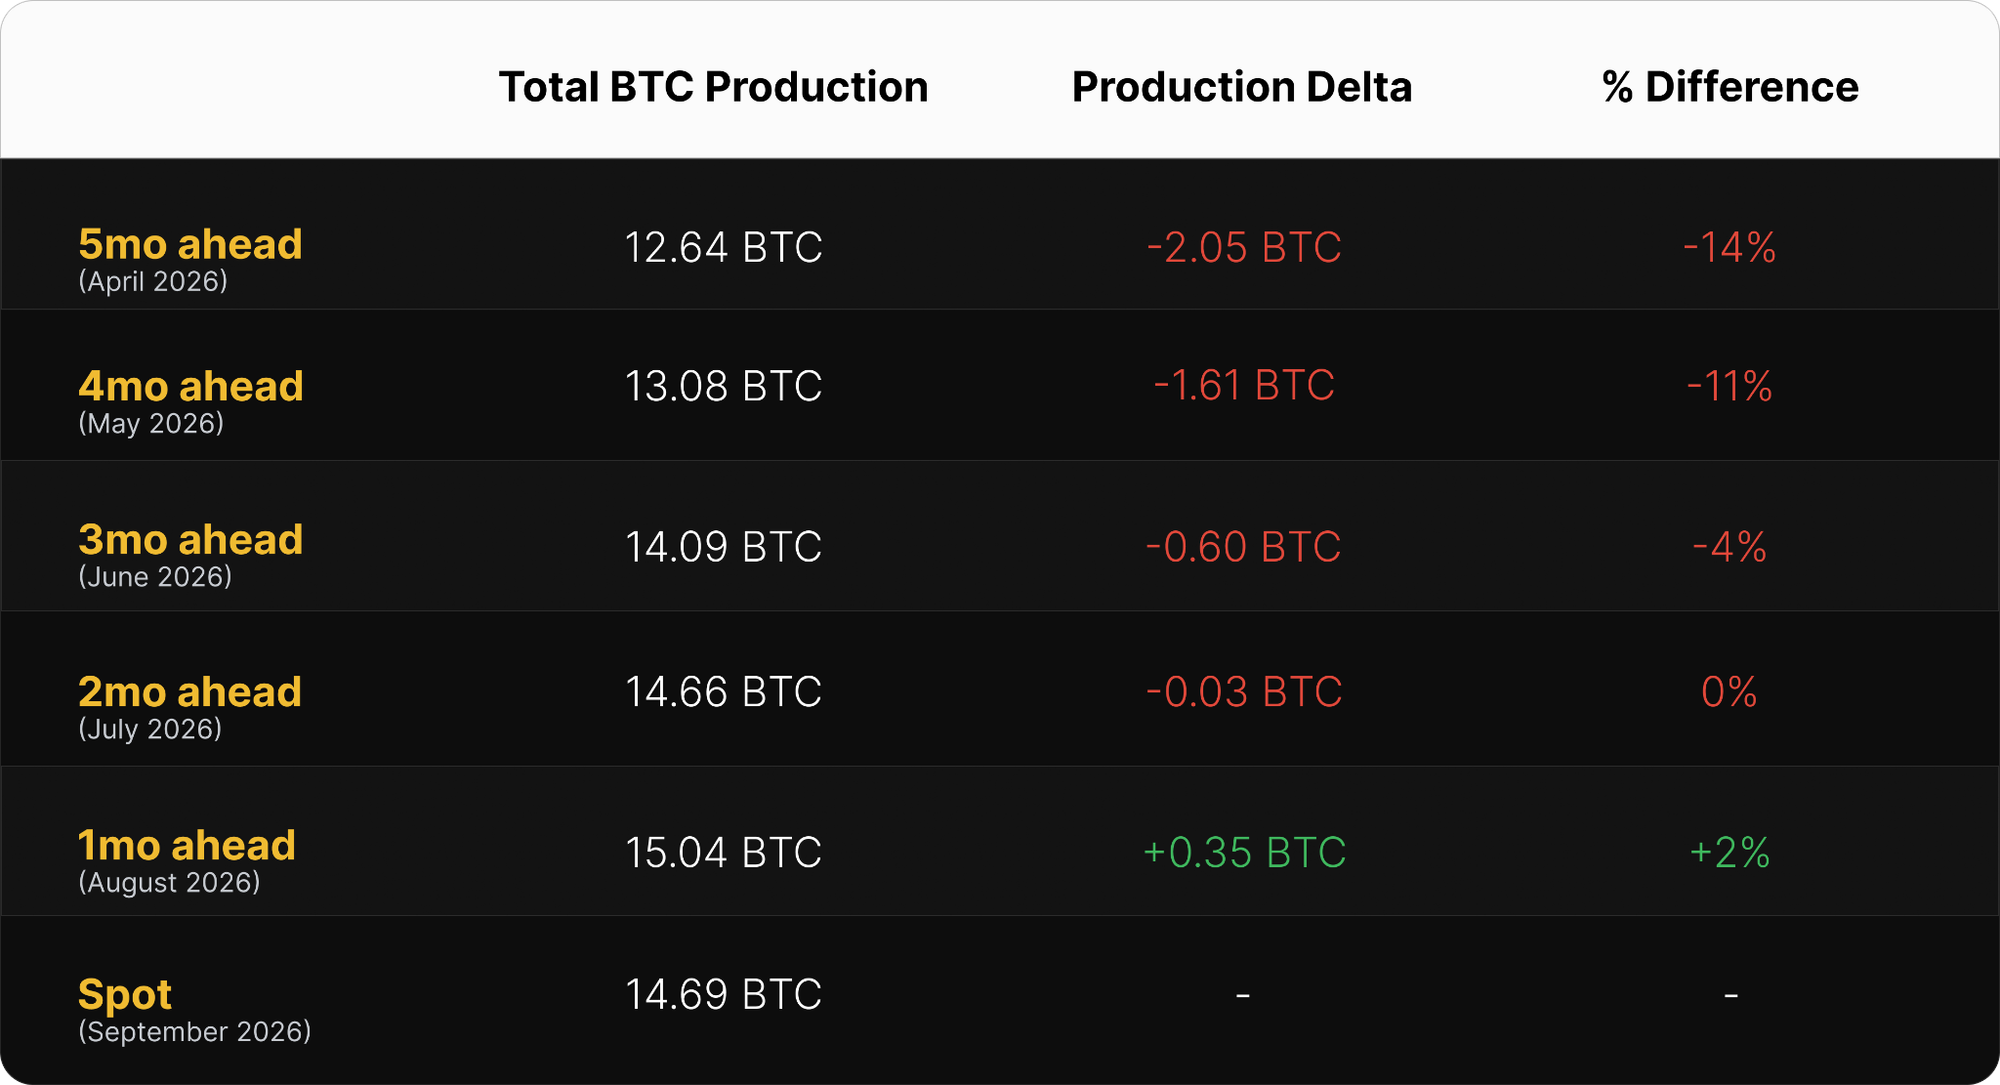
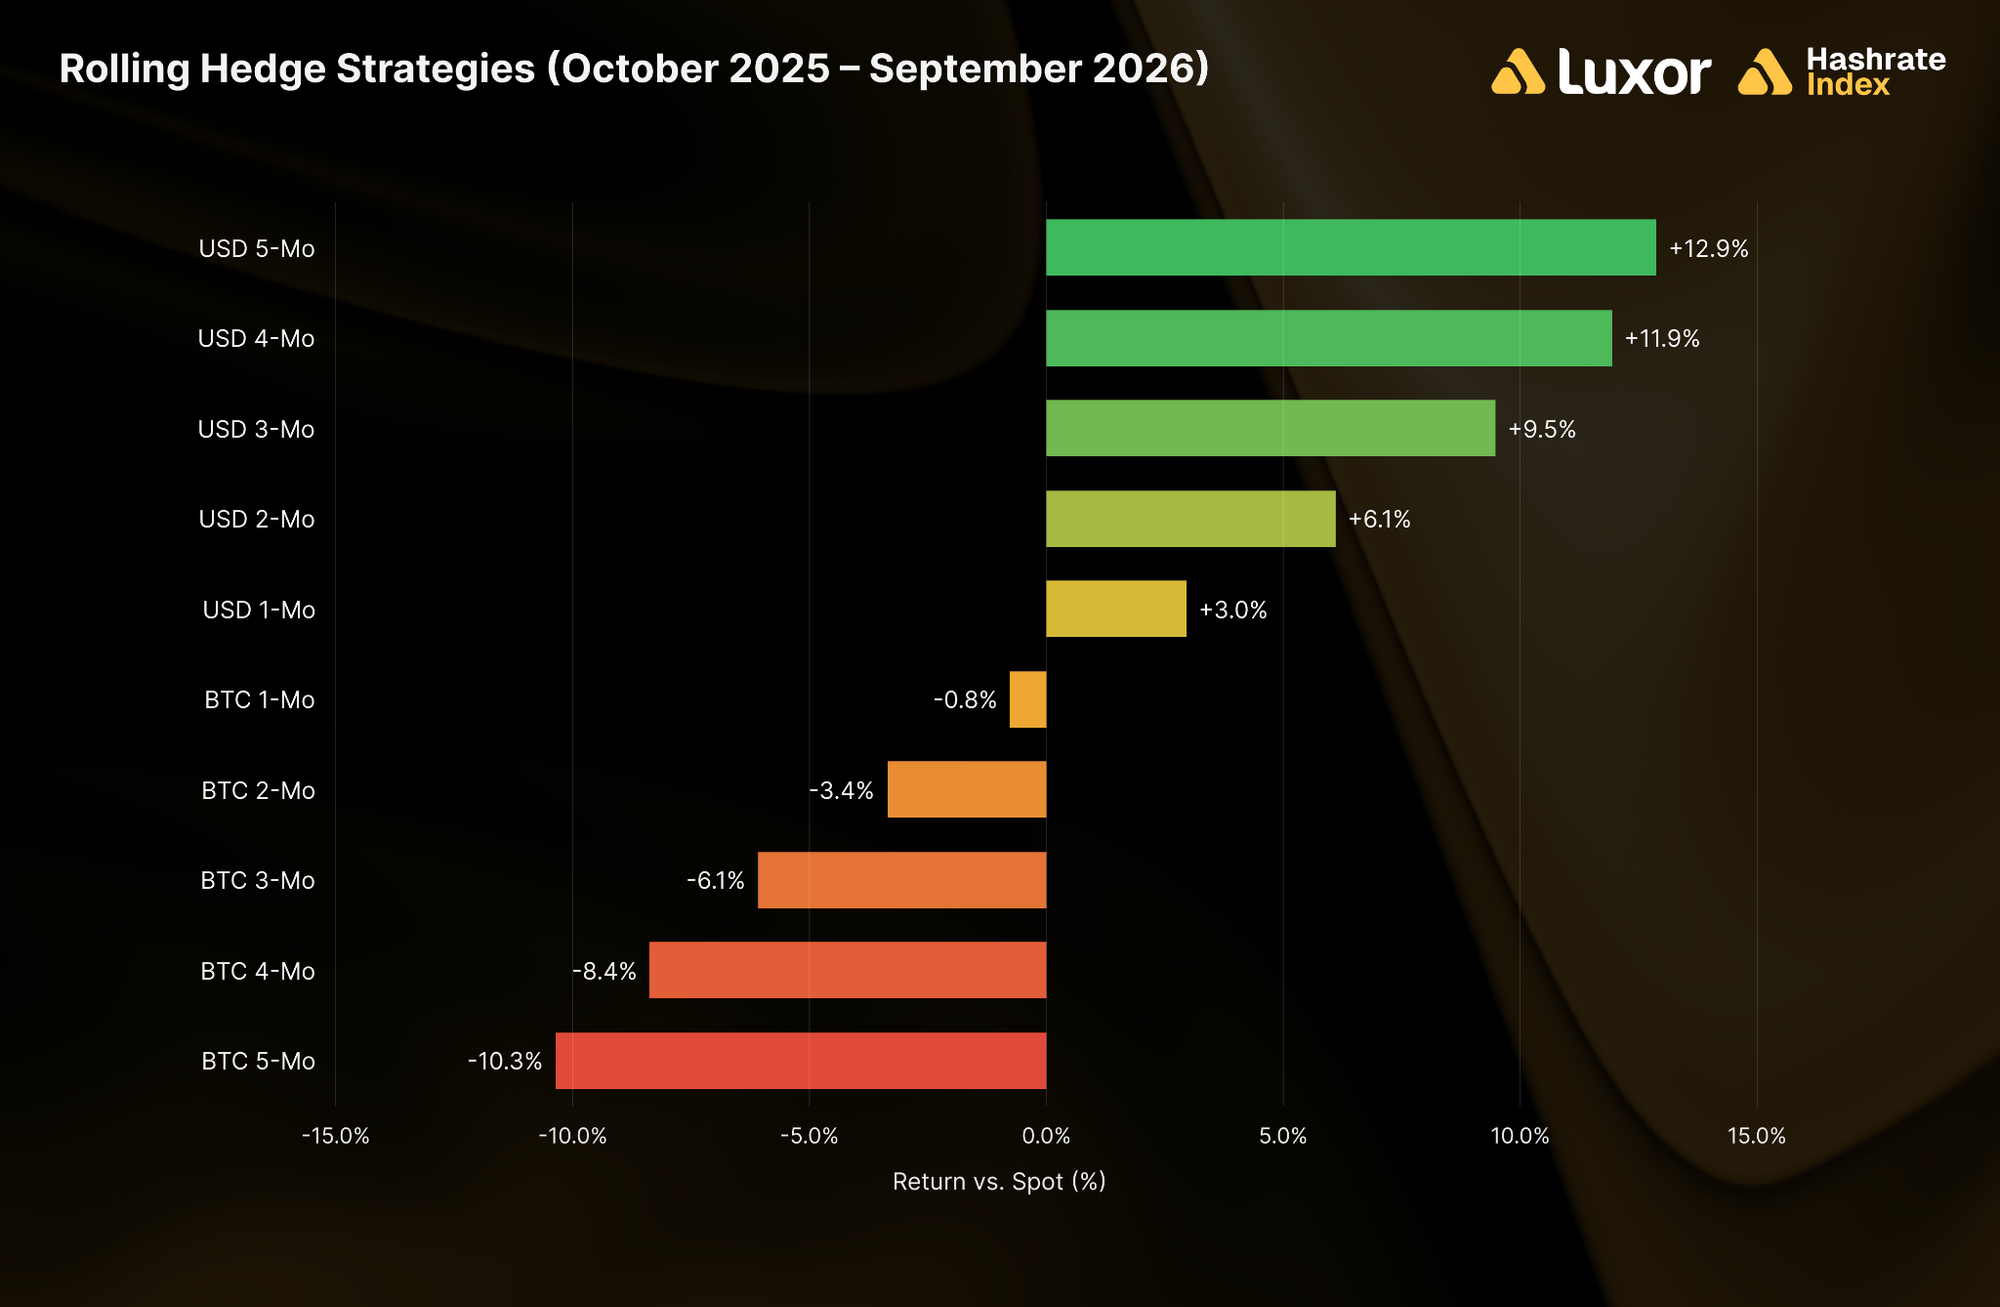
Over the trailing twelve-month period, rolling USD hashprice hedges outperformed spot mining rewards across all tenures, generating gains between 3.0% and 12.9%, while rolling BTC-denominated hedges lagged spot settlements by 0.8% to 10.3%. These divergent outcomes stem from persistent macroeconomic trends: a falling Bitcoin price pushed USD hashprice below forward sale prices, whereas moderating network hashrate growth earlier in the cycle lifted BTC hashprice above projected levels.
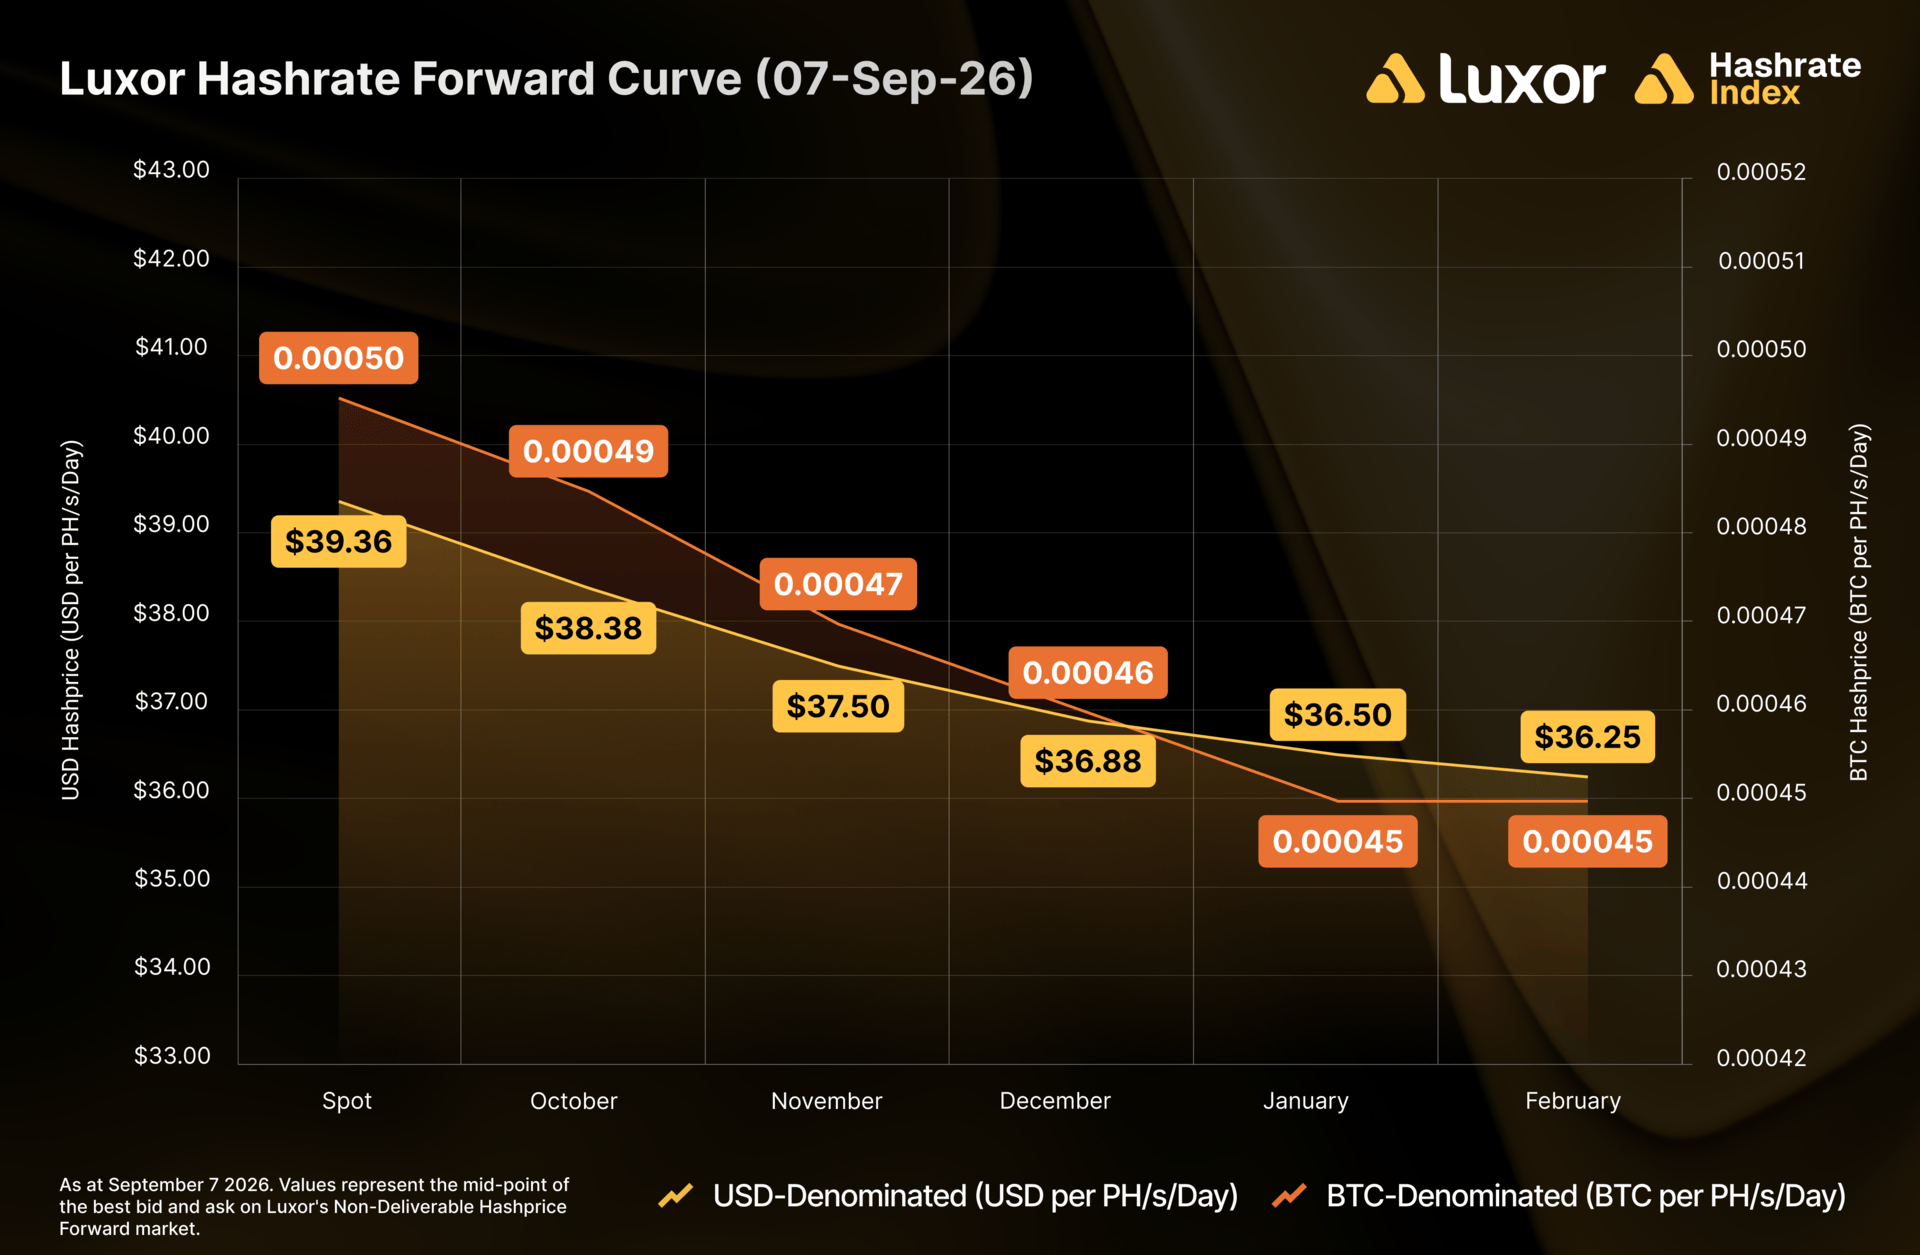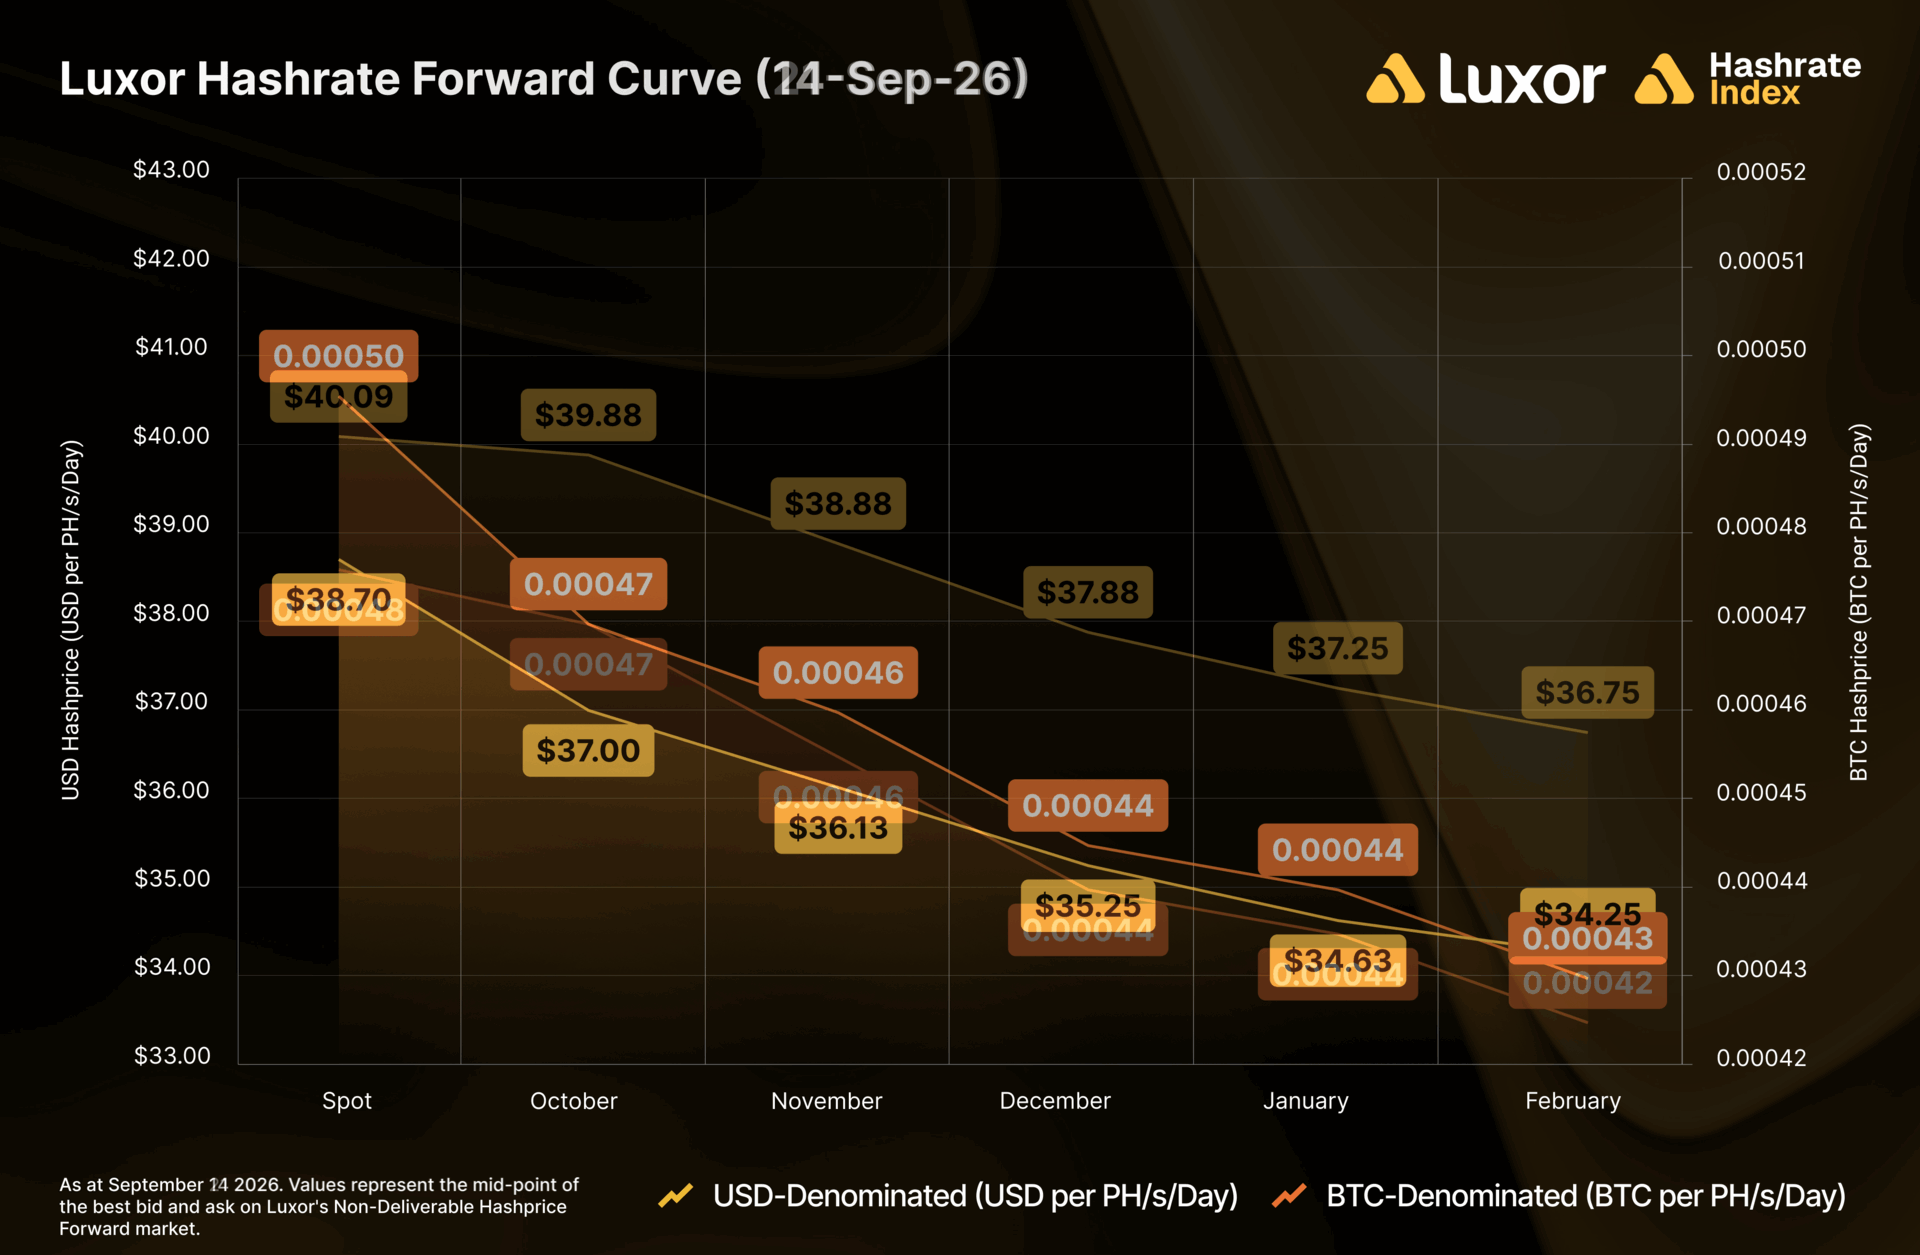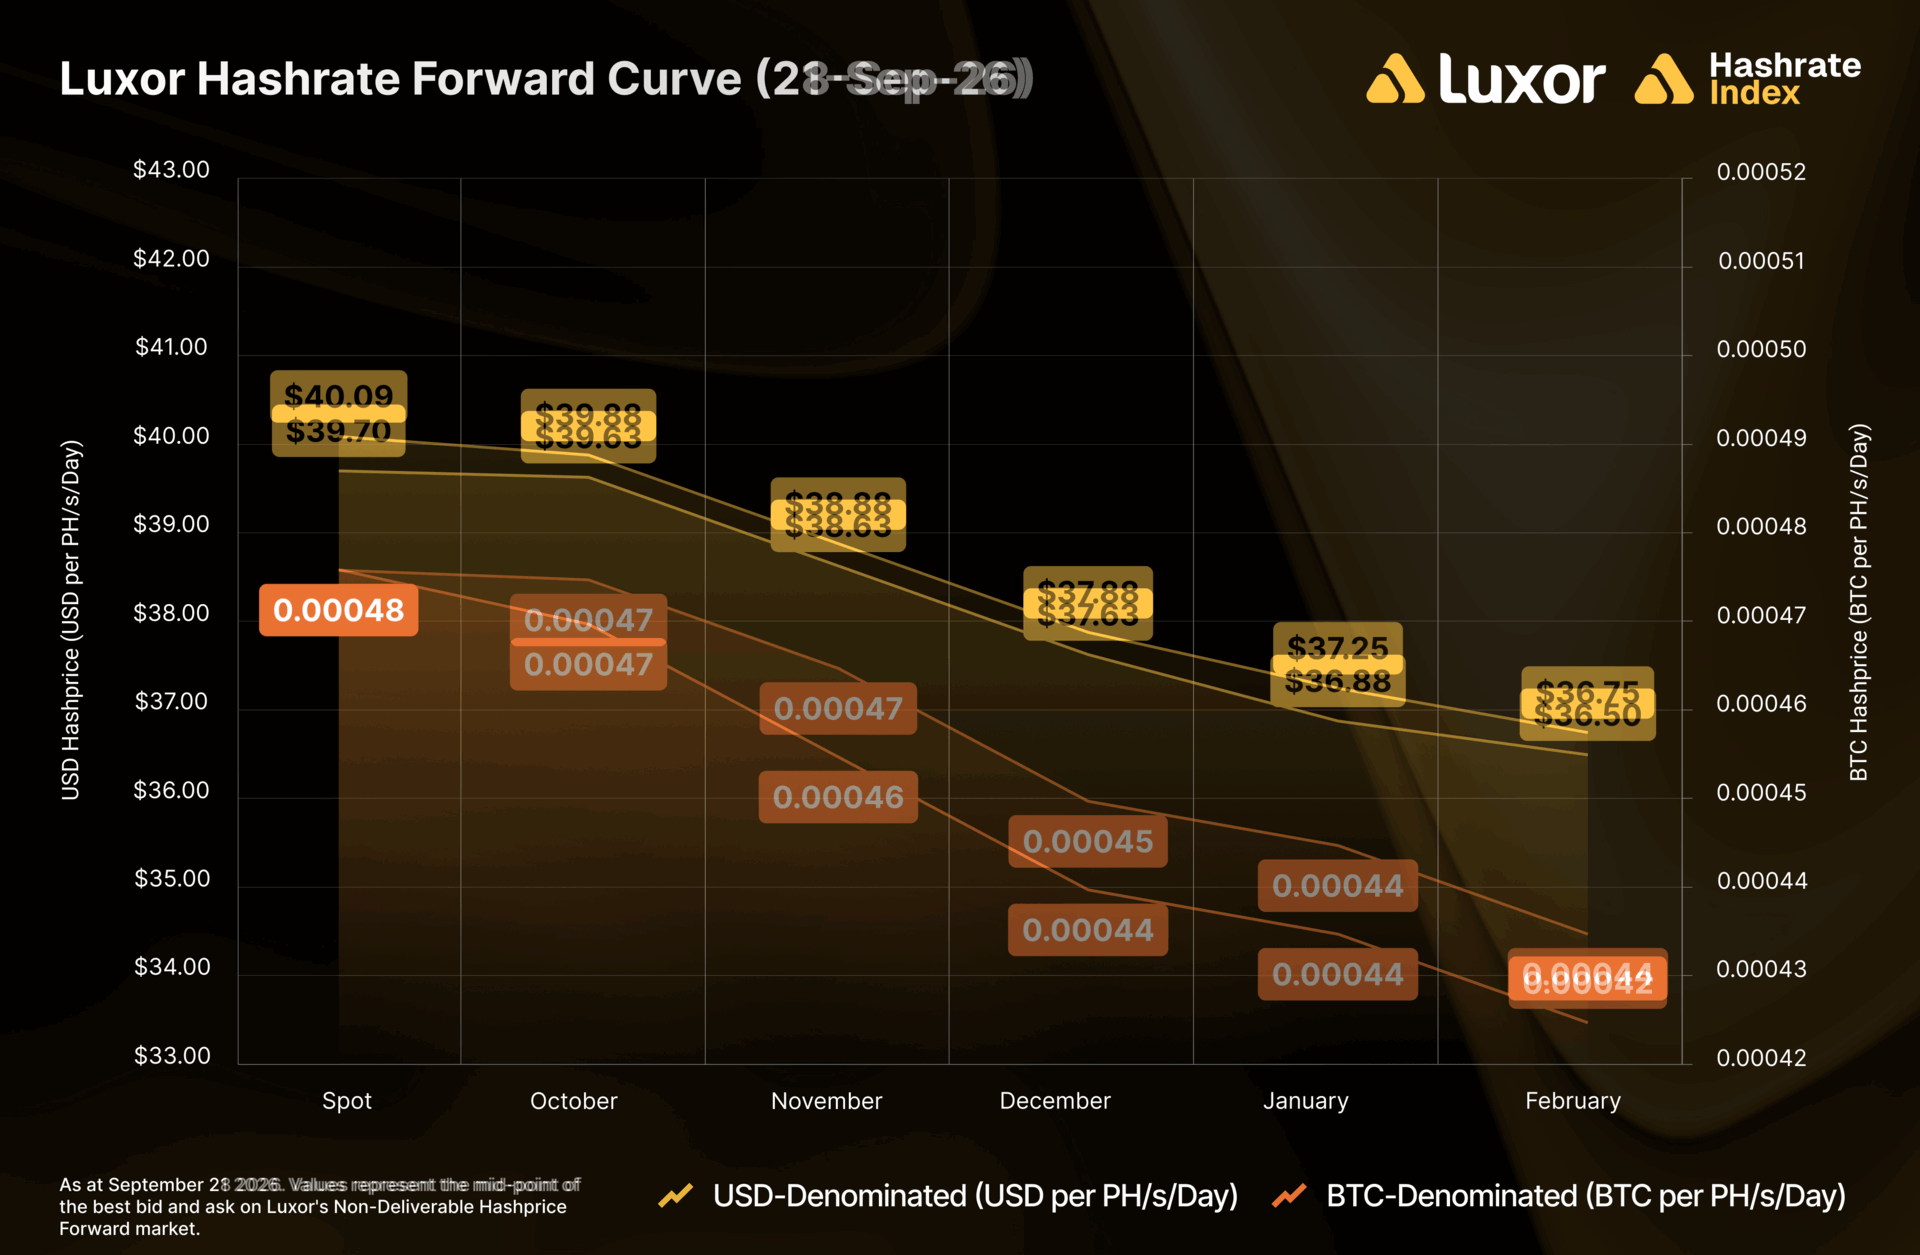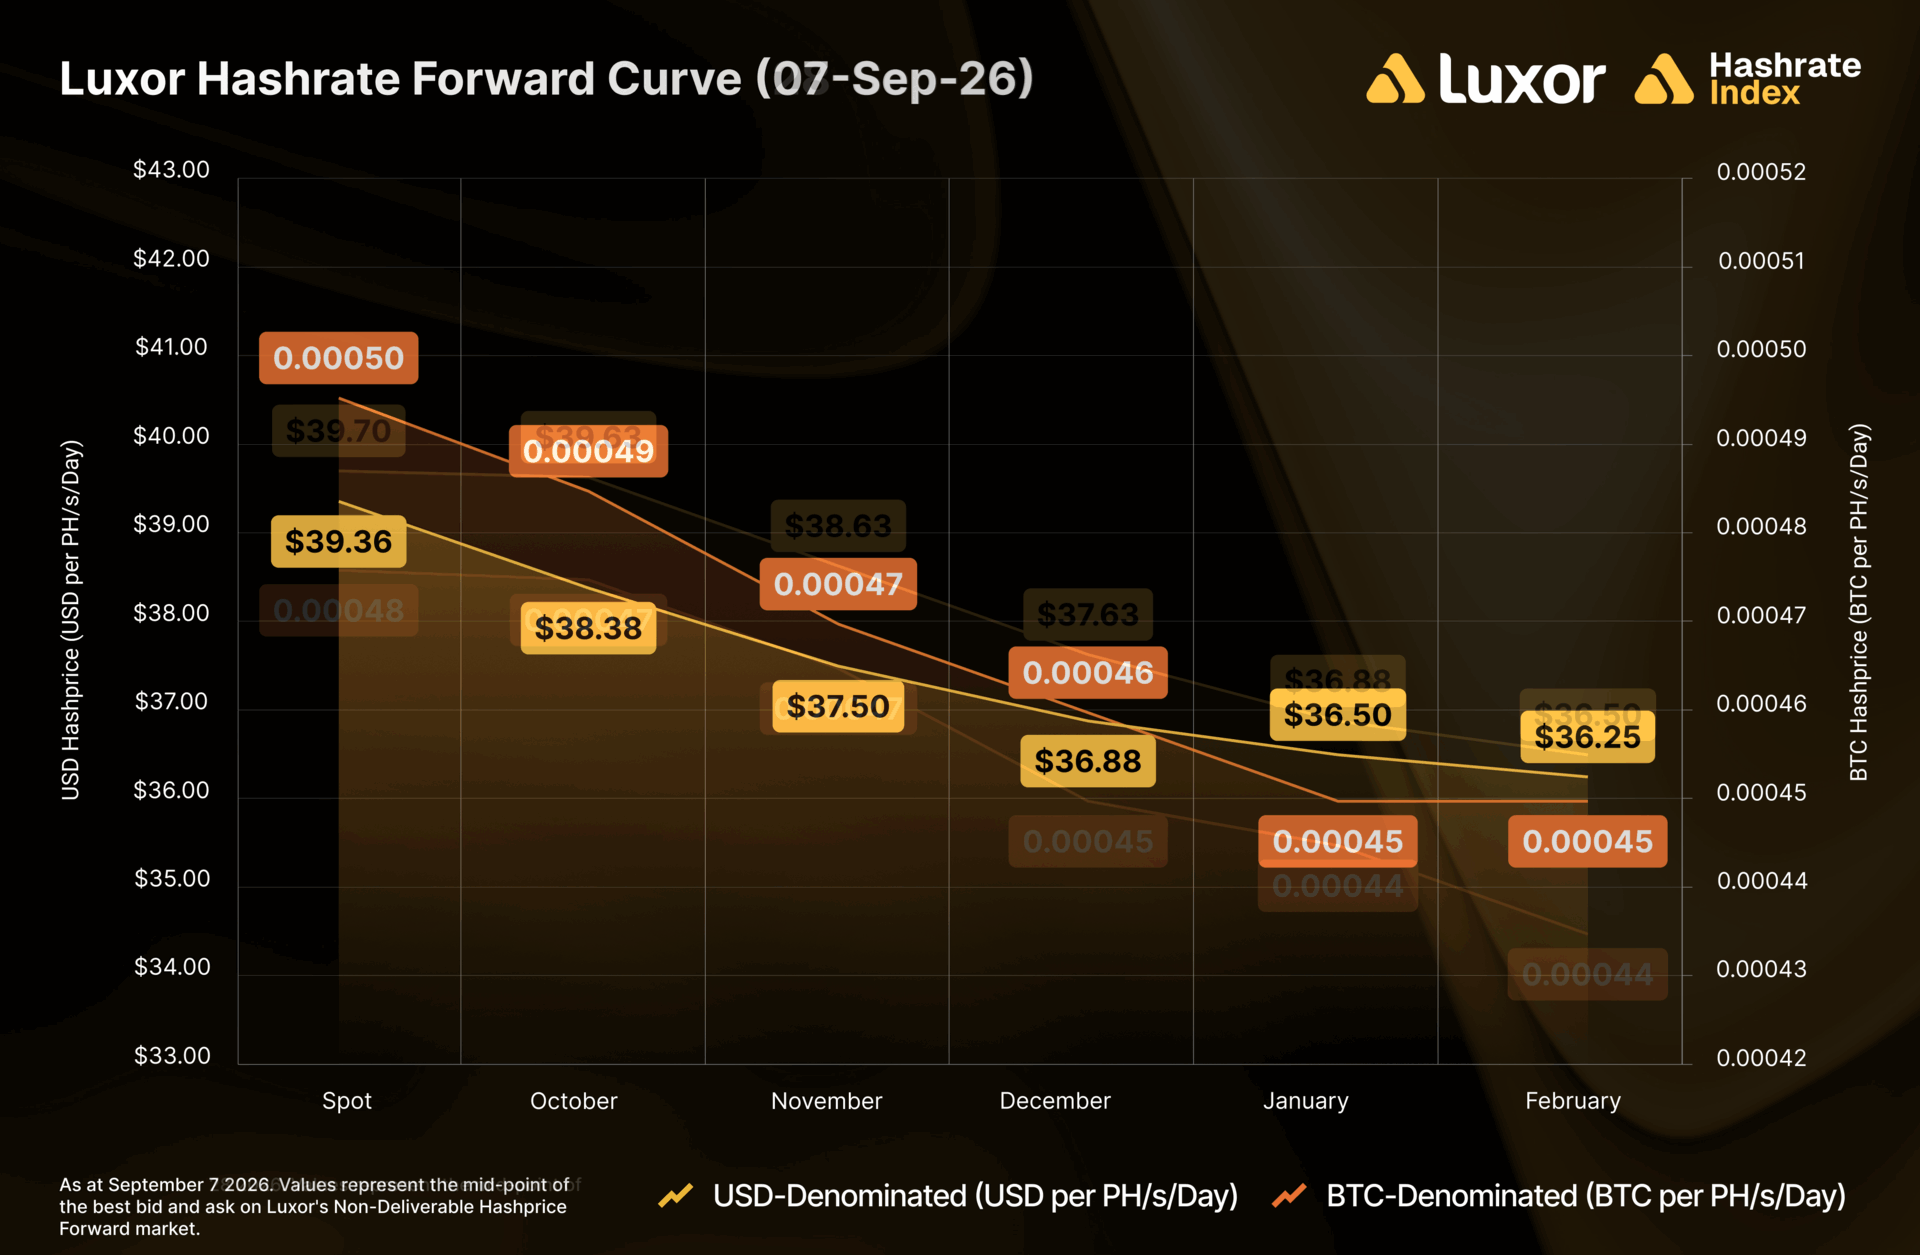
The forward market for the subsequent five-month period spanning October 2026 through February 2027 underwent significant repricing during September. USD-denominated hashrate forward curves rose at a slower pace than spot prices, with lock-in rates for the winter strip increasing between 2.8% and 5.3% against a 3.9% increase in spot hashprice. Simultaneously, BTC-denominated forward curves declined by 1% to 4% across the strip. By dividing USD contract values by their BTC counterparts, the implied Bitcoin price embedded within the forward market can be derived, placing expectations between $84,400 and $86,600 across the five-month horizon.
Assuming a baseline transaction fee collection of 0.0199 BTC per block, these forward contracts imply steady growth in network difficulty and total hashrate. Implied October difficulty was priced near 133.2T, while February 2027 difficulty climbed toward 147.1T. In terms of total network compute power, the forward curve priced the network at approximately 953 EH/s for October, scaling to 1,029 EH/s in January 2027 and 1,053 EH/s in February, confirming that the derivatives market has fully priced in the transition past the 1-exahash threshold.
Outlook and Market Trajectory
As the industry transitions into the final quarter of the year, seasonal patterns suggest that October will bring accelerated network difficulty growth. Historical data indicates that October has delivered positive difficulty adjustments every year since 2022, averaging roughly 10% growth across the month. With early-month blocks pacing rapidly, the first mid-October retarget points toward continued upward momentum.
While macroeconomic uncertainty remains a focal point—highlighted by upcoming Federal Reserve policy decisions and ongoing debates surrounding Texas transmission cost recovery rules—mining operations have largely absorbed the post-summer return of curtailed hashrate. Whether hashprice can sustain levels near $40 will depend entirely on Bitcoin’s capacity to outpace an expanding network difficulty baseline as the industry navigates the final months of 2026.
 Cryptocurrency Mining
 Cryptocurrency Mining
 Cryptocurrency Mining