
After two consecutive quarters of contraction, the Bitcoin network’s global hashrate has finally stopped falling. According to the latest data from Hashrate Index’s Global Hashrate Heatmap, the network’s aggregate computing power finished Q3 2026 at approximately 941 EH/s, remaining effectively flat compared to the ~940 EH/s recorded in the previous quarter. While a flat headline number might suggest a period of quiet consolidation, a closer examination of country-level metrics reveals an unusually dynamic quarter defined by significant global redistribution.
The United States shed another 10 EH/s of mining capacity, while Russia added 8 EH/s. Simultaneously, Ethiopia gave up roughly a third of its total hashrate due to localized hydroelectric shortages, and Pakistan more than tripled its computing output. The global bitcoin mining map is no longer shrinking overall, but it continues to shift rapidly across borders as operators chase cheaper power, adapt to regulatory pressures, and pivot toward lucrative artificial intelligence and high-performance computing (AI/HPC) markets.
From Falling to Flat
Following two quarters of sustained decline, Q3 2026’s network hashrate registered a 30-day simple moving average of ~941 EH/s against Q2’s ~940 EH/s. This marks the first quarter in 2026 where the global total did not record a drop.
However, a flat reading is not synonymous with a full recovery. The Bitcoin network remains roughly 8.7% smaller than it was a year prior, when it stood at approximately 1,031 EH/s in Q4 2025, and it sits roughly 15% below its all-time peak recorded in November 2025.
The primary shift lies in the deceleration of the market bleed. Marginal, less-efficient mining machines that were destined to switch off under prevailing hashprice conditions have largely been powered down. Meanwhile, network difficulty has adjusted downward far enough to keep surviving operations financially viable. This environment has left the most compelling industry developments at the country level, where significant compute capacity relocated across international jurisdictions.
Shifting Market Shares Among the Top Contenders
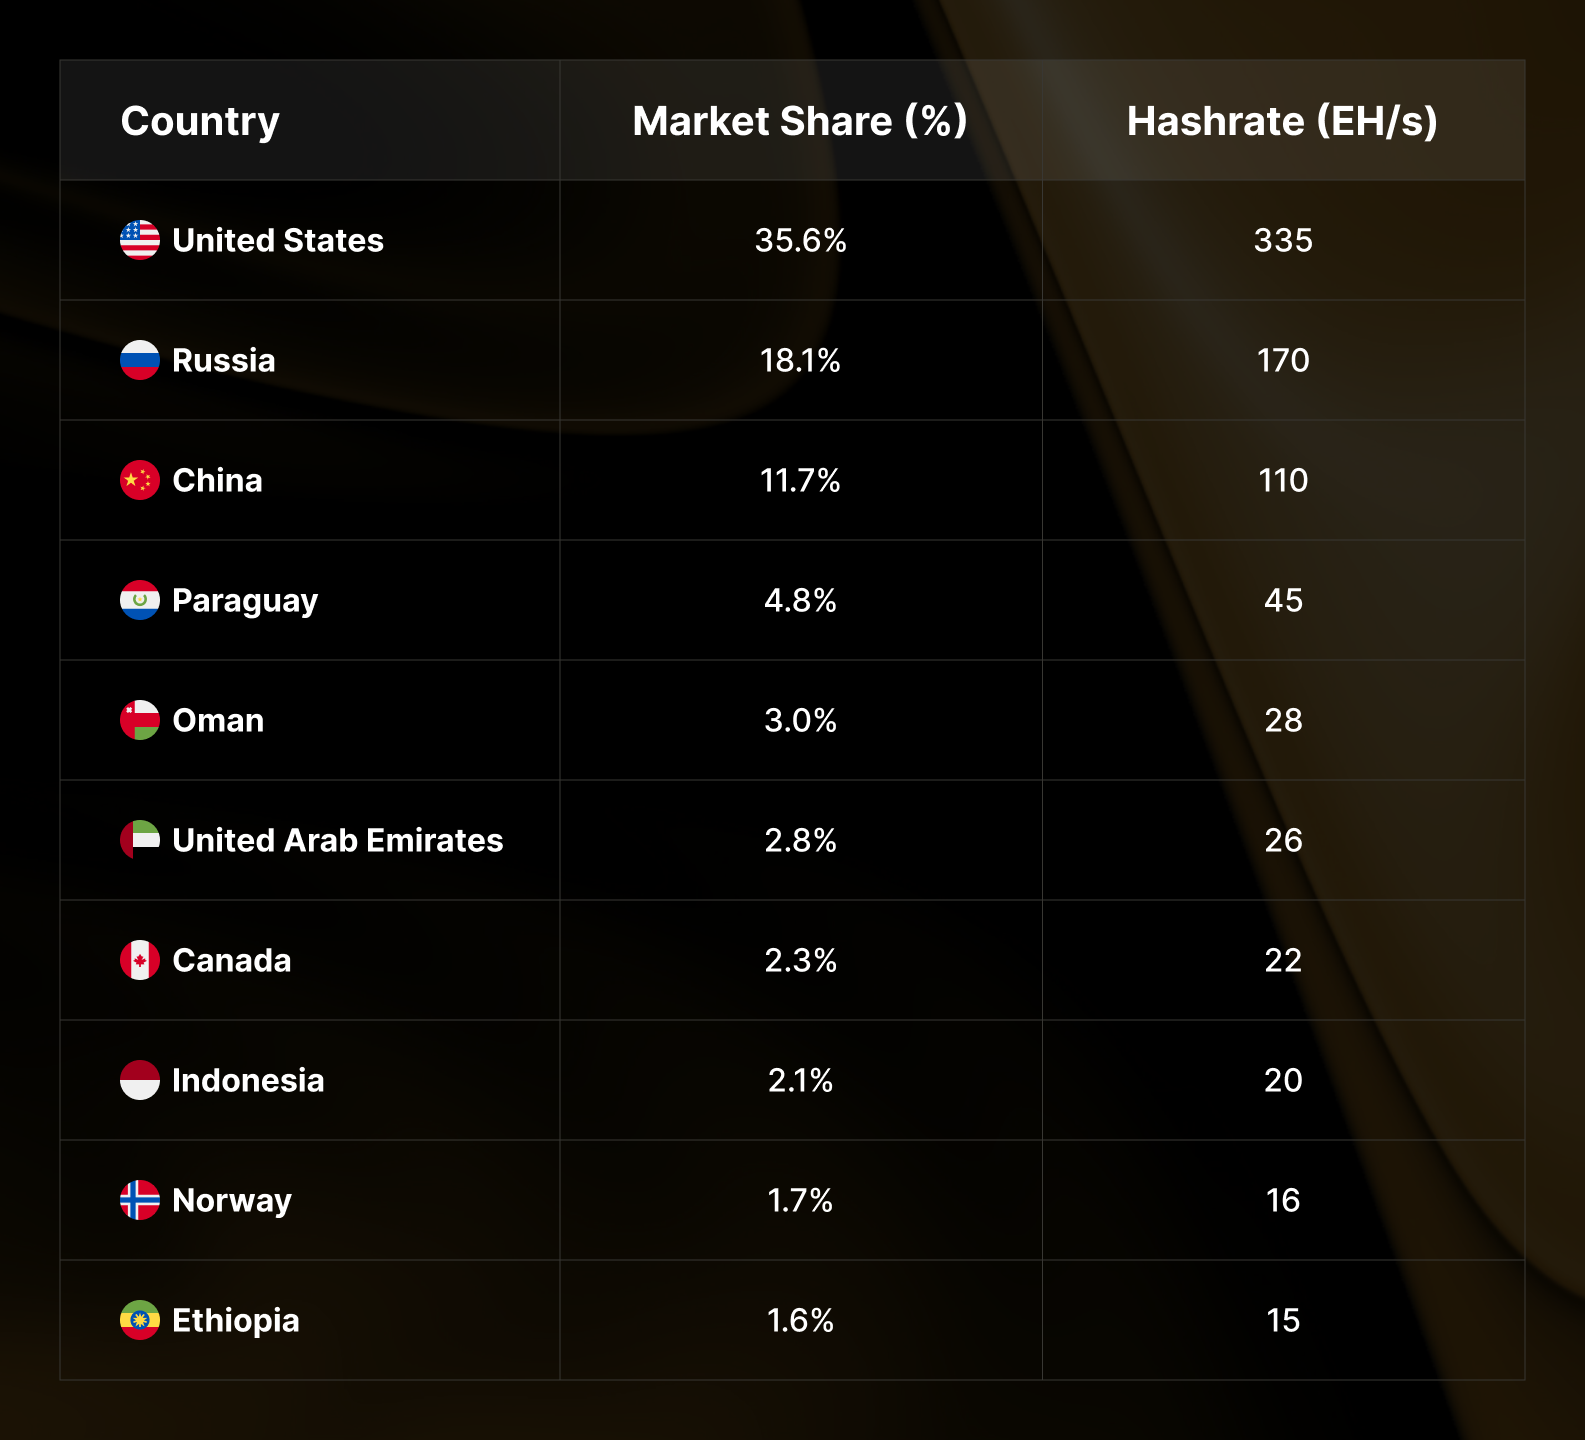
Bitcoin mining remains heavily concentrated, with the top three countries commanding roughly two-thirds of the global hashrate. However, top-three concentration slipped slightly from 66.2% to 65.4%, marking the second consecutive quarterly drop. The United States is surrendering market share faster than Russia is absorbing it.
The overall top-ten country group remains identical to the previous quarter, but five of the ten individual ranks changed hands. Oman climbed past the United Arab Emirates to secure the fifth position. Indonesia advanced from ninth to eighth place, backed by a genuine 3 EH/s gain. Conversely, Ethiopia slipped from eighth down to tenth place. Kazakhstan held steady at the eleventh spot with roughly 15 EH/s for a second consecutive quarter, placing it in a virtual tie with Ethiopia for the final top-ten slot heading into the close of the year.
Comparing Q4 2026 to Q3 2026, the global map split cleanly between a shrinking developed core and a rapidly expanding frontier. On the declining side, established markets faced downward pressure from power reallocation and structural shifts. On the gaining side, emerging markets stepped up significantly. Pakistan added 5.5 EH/s—a larger absolute increase than it had ever posted before—while Venezuela added 4 EH/s, pushing its total market size to approximately 10 EH/s, which places it ahead of jurisdictions like Laos, Finland, and Malaysia.
The Long View and the AI/HPC Pivot
Examining year-over-year trends strips away short-term quarterly noise to highlight more durable structural trajectories. Every market that registered substantial annual growth represents a low-cost or stranded-power story.
However, the declining markets do not form a simple mirror image of that trend. Traditional mining hubs like Canada and the United Arab Emirates are not prohibitively expensive places to operate. Canadian hashrate relies heavily on hydroelectric power in Quebec, Manitoba, and British Columbia, while Abu Dhabi draws on gas, solar, and nuclear-backed energy supplies. These jurisdictions did not lose hashrate because local power generation became too costly.
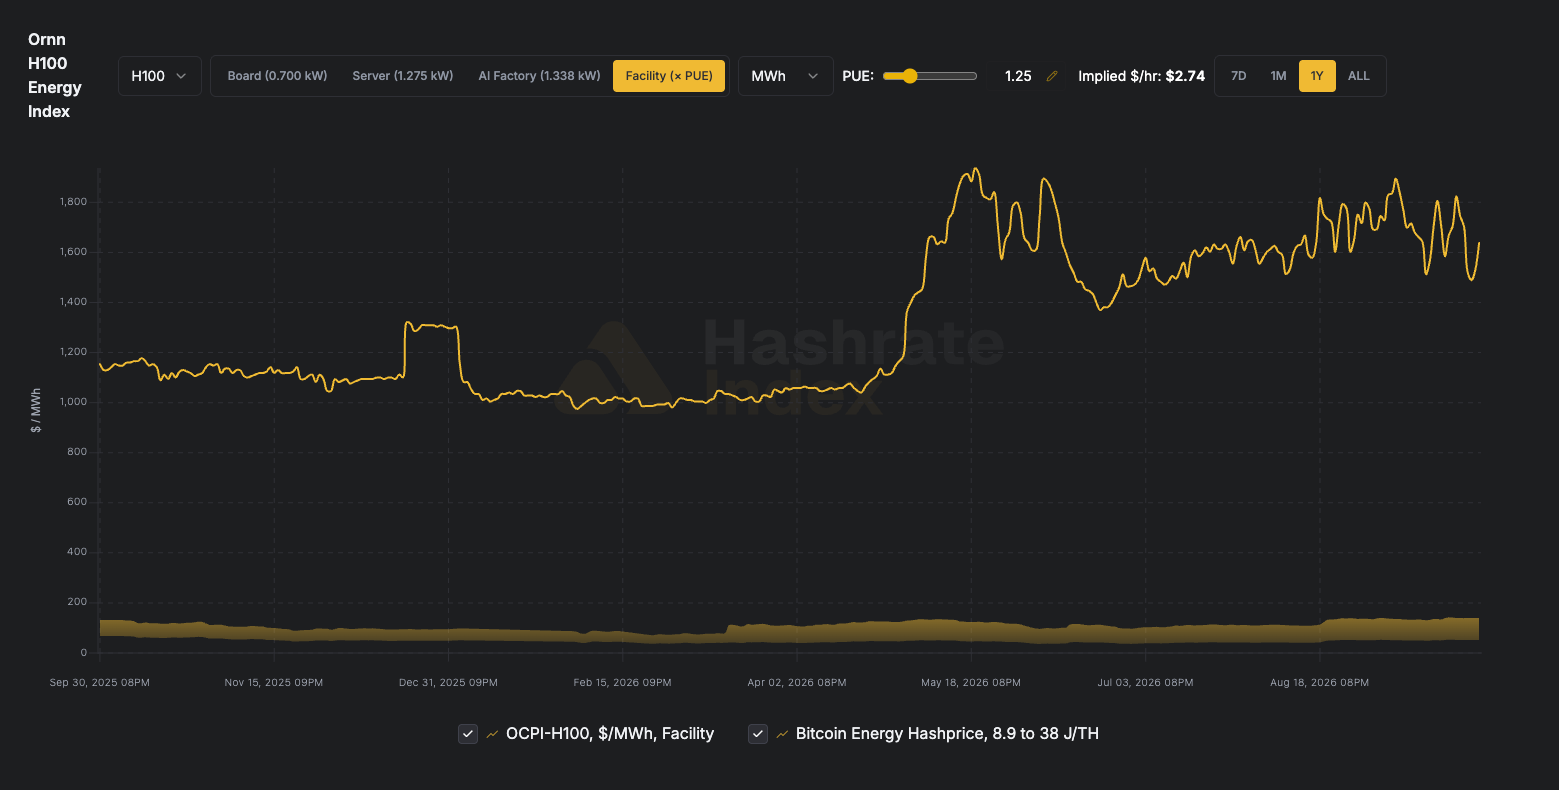
Instead, they lost computing power because the available energy found a much more lucrative application. Both regions host sophisticated operators that are well advanced in the artificial intelligence and high-performance computing pivot that defined 2026. The economic disparity between sectors is stark, with AI compute generating anywhere from $1,500 to $3,500 per megawatt-hour, compared to a range of $50 to $150 for Bitcoin mining.
This distinction holds profound implications for the future of the network. A marginal ASIC machine that goes offline due to a drop in hashprice can easily be powered back on if market conditions improve. By contrast, power capacity committed to a multi-year AI tenant cannot be easily reclaimed, even if the price of Bitcoin rallies and mining difficulty drops. Consequently, global market decliners are splitting along three distinct paths: capacity converting to AI and high-performance computing infrastructure in places like the United States, Canada, and the UAE; ongoing regulatory pressures in nations like Kazakhstan, China, and Iran; and macroeconomic impairments in countries like Argentina.
Standouts and the Ethiopian Hydroelectric Crunch
Paraguay continues to anchor the group of nations expanding through a down-cycle, adding another 1 EH/s to reach roughly 45 EH/s, which secures its place as the fourth-largest global mining hub with a 12% year-over-year increase anchored by Itaipú hydropower. Indonesia stands out as the quarter’s clearest structural gainer, operating at approximately 20 EH/s to secure a top-eight slot with an 18% year-over-year gain, driven by Southeast Asian hydro diversification. Norway, meanwhile, has held steady at roughly 16 EH/s for four consecutive quarters.
The most dramatic reversal story of the period belongs to Ethiopia. The East African nation fell from roughly 23 EH/s to 15 EH/s, marking a 35% quarterly decline that dropped its global ranking from eighth to tenth and returned its metrics to mid-2025 levels. Measured from its peak of 27.5 EH/s earlier in the year, the market has contracted by 45% in three quarters.
The cause of this contraction is well-documented and stems directly from natural resource constraints rather than a policy reversal. On September 15, Ethiopian Electric Power drastically cut electricity supplies to Bitcoin miners down to approximately 23% of contracted volumes—representing a reduction of about three-quarters. This emergency measure was enacted after reservoir inflows dropped by roughly 20% due to severe El Niño-driven dry conditions.
Ethiopian mining operations proved uniquely exposed to these conditions because the nation’s entire industrial mining sector relies on a single massive hydropower source, leaving operations vulnerable when seasonal water levels fail to materialize. Without a recovery in reservoir inflows, Ethiopian hashrate is widely expected to face further downward pressure, with state energy officials signaling that additional power cuts and restrictions on electricity exports to neighboring countries remain under consideration.
Regional Dynamics Across Global Markets
In North America, the United States remains the dominant global leader with a 35.6% market share, though it recorded its third consecutive quarterly decline down to roughly 335 EH/s, representing a 14% year-over-year drop from its peak of 400 EH/s earlier in the year. Canada continued its downward slide to 22 EH/s, marking a 27% annual decline that represents the sharpest drop among developed markets.
Across Europe and Central Asia, Russia emerged as the quarter’s largest absolute gainer, expanding by 8 EH/s to reach approximately 170 EH/s, which accounts for an 18.1% global share. Kazakhstan stabilized around 15 EH/s following a prolonged period of losses, while Norway held at 16 EH/s and Georgia maintained 11 EH/s.
In the Asia-Pacific region, China’s hashrate eased further to approximately 110 EH/s, continuing a steady multi-quarter bleed that reflects a 24% year-over-year contraction. At the same time, regional diversification continued as Indonesia reached 20 EH/s and Malaysia climbed to 7 EH/s, while Laos added 1 EH/s to reach 9 EH/s.
The Middle East saw Oman reverse its previous trajectory by adding 2 EH/s to reach 28 EH/s, allowing it to surpass the United Arab Emirates, which slipped to 26 EH/s amid a 21% annual decline. Iran also posted a modest recovery, ticking up to roughly 3 EH/s for its first increase since geopolitical tensions escalated earlier in the year.
In Latin America, Paraguay leads the field at 45 EH/s and continues to expand its footprint. Venezuela’s climb to 10 EH/s served as a major regional headline, achieved despite a blanket state prohibition on mining that has remained in force since mid-2024. Observers note that surviving operations largely operate informally or semi-legitimately. Elsewhere in the region, Bolivia edged up to 4 EH/s, while Argentina continued to decline to 3 EH/s due to ongoing macroeconomic instability.
Finally, the African continent experienced a notable contraction driven entirely by Ethiopia’s 35% quarterly drop, which pulled the continent’s flagship market down to 15 EH/s. With no other regional markets large enough to offset the deficit, Africa’s overall share of the global hashrate contracted significantly as the industry navigated the realities of localized energy constraints.
 Cryptocurrency Mining
 Cryptocurrency Mining
 Cryptocurrency Mining







