
North America stood as the most influential region for global cryptocurrency markets during the 12-year reporting period ending July 1, 2026. Backed by the deep investor capital of the United States, progressive updates to domestic regulations, the widespread utility of stablecoins as a digital currency, and businesses integrating blockchain ever-closer to traditional financial systems, the region continues to export its crypto industry trends to the rest of the world.
According to metrics from the period, the United States and Canada topped the unweighted "big-money index," an economic power measurement covering the surveyed countries. Together, their respective crypto economies totaled $3.02 trillion for the 2026 period, representing a modest 1.9% contraction from the prior year. This regional slowdown was primarily driven by the United States, where the $2.78 trillion crypto economy dipped by 2.2% period-over-period against the backdrop of a severe bear market.

Despite the slight pullback, the world’s single-biggest crypto economy largely retained the near-doubling of value it achieved during the 2025 period. Institutional drivers, including the proliferation of crypto exchange-traded funds (ETFs), accelerated asset tokenization, and the massive expansion of stablecoins, proved vital in sustaining those historical gains.
Hoolie Tejwani, Head of Coinbase Ventures, noted that much of the market activity compared to 2025 points to the broader maturation of the industry. The foundational building blocks established previously have successfully transitioned into functional products boasting real users, robust liquidity, and active markets in 2026.
This maturation is underscored by a trio of U.S.-developed crypto products that have attracted massive engagement both domestically and globally: AI commerce, stablecoins, and tokenized real-world assets. Meanwhile, the Canadian market proved resilient against the broader North American downtrend, growing 2.3% to reach a $250 billion crypto economy, fueled in part by a vibrant peer-to-peer ecosystem anchored by its immigrant population.

The U.S. Leads the AI On-Chain Economy
The United States has emerged as an undeniable leader in the global artificial intelligence development race, an advantage that is now reshaping digital assets. To understand how the intersection of AI and blockchain is taking shape, researchers examined x402, a prominent digital payments rail enabling AI agents to autonomously spend funds.
As autonomous software increasingly pays for services on-chain, cornerstone American companies are supporting the infrastructure. Circle, the issuer of the leading agent currency USDC, and Coinbase, the developer of the x402 system, are heavily involved. Traditional financial institutions are also taking notice; Will Su, Head of Digital Assets Research at BlackRock, highlighted that the firm is monitoring agentic commerce closely due to AI agents potentially generating continuous demand for frequent, low-value payments around the clock.

By the close of the 2026 period, over 138 million x402 transactions had been recorded on Base, the leading blockchain network utilized for agentic commerce. Traditional payment rails like credit card networks cannot economically process micro-transactions worth fractions of a cent. However, stablecoins with settlement costs of less than a cent make it economically viable for machines to spend tiny amounts, unlocking entirely new pay-as-you-go digital services, such as on-demand data retrieval via API calls.
Circle characterizes this evolution as a clean division of labor, utilizing card rails for consumer-prompted agent payments and stablecoin rails for machine-to-machine settlements that fall below the economic thresholds of traditional cards. The vast majority of x402 activity registered as micropayments, with over 87% of payments falling between a hundredth of a cent and a dime, and the most common transaction sizing between one and ten cents.
AI Payments Are Becoming Stickier

While agentic commerce remains in its broader experimentation phase, clear signs of maturation are visible. Early adoption of x402 was characterized by transient users testing crypto trades and abandoning the protocol once their initial funds depleted. That dynamic has drastically shifted over time.
Subsequent cohorts of wallets have arrived with significantly higher long-term commitments. Grouping wallets by the quarter they were first funded, the share securing a second funding within 30 days climbed from 70.6% for wallets initialized in the third quarter of 2025 to 89.3% for those funded in the second quarter of 2026. This behavior mirrors traditional subscription renewals. Furthermore, the temporal gap between initial wallet funding and the first x402 spend has sharply compressed. While median wallets in late 2025 were 73 days old before initiating an x402 payment, that duration dropped to just 18 minutes by the third quarter of 2026, signaling that new wallets are deliberately provisioned for immediate agentic commerce.
What AI Agents Are Buying with x402

While initial transactions on x402 were dominated by short-lived speculative fads like memecoins, the network’s maturation has fostered enduring machine-to-machine utility, particularly within the information sector. AI models are systematically purchasing machine-readable knowledge on-chain.
Millions of transactions now flow from AI wallets into services like code review, financial intelligence, and search APIs. Additionally, agents are funding gameplay, token issuance, gambling services, and agentic tooling. Significantly, a massive category of x402 expenditure is dedicated to model inference, with AI agents effectively paying other AI models for computational output.
The U.S. Dominates AI-to-AI Commerce

American-funded AI agents transact far more frequently with x402 services than operators from any other country, commanding a 30% share of all geolocated agent-to-service transactions. U.S. wallets account for 88.1% of all geolocated AI model inference payments on the protocol, alongside major shares in agent frameworks and data APIs.
Conversely, Chinese-attributed wallets displayed a different pattern, heavily concentrating on security and code analysis. Roughly nine out of ten transactions routed into security and code analysis originated from Chinese-linked wallets, primarily interacting with AgentLISA, an LLM-powered Solidity smart contract auditing service. Chinese-linked operators also held significant shares in financial intelligence and payment rails, but accounted for just 0.1% of model inference payments. This disparity reflects economic realities and localized preferences, as Chinese markets lean toward domestic open-weight models like DeepSeek and Qwen, which are free to use, whereas U.S.-developed metered models like ChatGPT and Claude require consistent payment.
The U.S. Imports Digital Gold and Exports Digital Dollars

The formalization of digital asset policies has further cemented the United States as the world’s leading exporter of digital dollars. Stablecoins have transformed U.S. sovereign debt into the preferred currency for cross-border businesses and peer-to-peer economies alike, generating billions of dollars in economic activity.
While exporting stablecoins globally, the United States has concurrently become a major importer of bitcoin. Following the introduction of spot bitcoin ETFs in early 2024, the U.S. share of global bitcoin activity rose steadily. Conversely, stablecoins comprise a smaller percentage of domestic American crypto activity compared to foreign markets, as citizens already enjoy direct access to traditional bank accounts and domestic fiat infrastructure.
Cross-border bitcoin flows into and out of the U.S. revealed that the nation became a net importer of bitcoin for the first time since 2022. While retail-sized transfers under $10,000 ran net outbound, institutional-sized transactions flipped the ledger, with transfers exceeding $10 million accounting for massive net inflows. Nearly all stablecoin order book volume remains pegged to the dollar, creating an efficient routing layer that connects fiat, local stablecoins, and global dollar liquidity while backing tokens primarily with short-dated U.S. government debt.

The U.S. Impact on Asset Tokenization
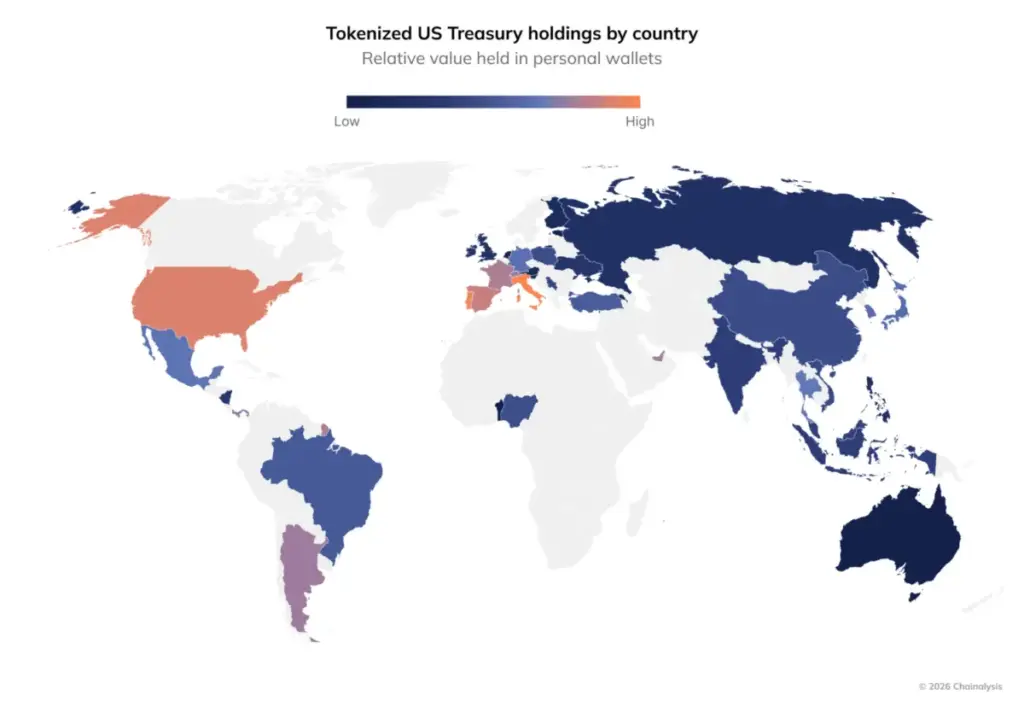
The United States continues to dominate the rapidly expanding tokenization sector, which saw the global market finish the second quarter of 2026 at $36.07 billion, marking a 135% year-over-year increase. U.S. Treasury bonds represented the single largest real-world asset (RWA) category, holding $15.42 billion on-chain and capturing 42.8% of all tokenized RWA value.
While corporate credit and private equity experienced exponential percentage gains from smaller bases, Treasury debt’s absolute expansion dwarfed other categories. Interestingly, while domestic U.S. holders account for roughly 11% of the global tokenized RWA holder base and total value, tokenized Treasuries show a different geographic distribution. International jurisdictions like Italy, Portugal, and Singapore lead in the total value of tokenized Treasuries held, while countries like Japan boast large retail holder bases with smaller individual allocations. This mechanism effectively allows retail investors worldwide to bypass traditional U.S. brokerage relationships, generating foreign demand for U.S. government debt.

Canada Leads in Global Peer-to-Peer Adoption
Canada maintained its position as the second-largest crypto economy in North America, growing 2.3% during the 2026 period to reach $247.7 billion. Despite being a highly developed economy, Canada boasts an unusually robust peer-to-peer crypto market, ranking seventh globally in domestic and cross-border flows and leading the G7 in P2P activity.
Stablecoins capture a dominant 44% of Canadian dollar-based order book volume, with USDC leading the market while domestic Canadian dollar-backed stablecoins remain minuscule in comparison. Industry experts note that this reliance on USD-denominated stablecoins funnels demand toward U.S. debt rather than domestic alternatives, a policy topic being closely monitored by Canadian regulators following the implementation of the country’s new stablecoin framework.

Furthermore, Canada’s thriving immigrant population—representing roughly 23% of the country—serves as a primary catalyst for its massive cross-border remittance economy. Stablecoin and bitcoin transfers routed from Canada to high-growth corridors like India, China, and the Philippines reached $2.36 billion over the period, spanning millions of transactions. Driven by the prohibitive costs of traditional remittance providers, immigrant workers increasingly rely on blockchain rails to support financial obligations abroad efficiently. Domestic P2P transaction volumes in Canada have historically tracked closely with temporary visa and immigrant population trends, demonstrating that populations with active cross-border financial lives readily adopt lower-cost settlement options.
Ultimately, North America’s current crypto narrative centers less on retail user counts and more on foundational infrastructure. American institutions, stablecoin issuers, and developers anchor the underlying rails for tokenized Treasuries, digital dollars, and AI commerce. As international regulators continue exploring regional alternatives, the ongoing evolution of regulatory frameworks and digital asset adoption will dictate how the global economy interacts with North American-built blockchain technology.
 Crypto Wallets & Security
 Crypto Wallets & Security
 Crypto Wallets & Security







