Luxor’s Monthly Lookback Series provides a deep dive into Bitcoin hashrate market activity, tracking the evolving economics of digital asset mining. The August 2026 report covers hashrate market trends, hashprice movements, forward market participation, trading activity, and contract performance against a backdrop of shifting macroeconomic conditions and regulatory developments.
August 2026 Spot Hashprice and Its Constituents
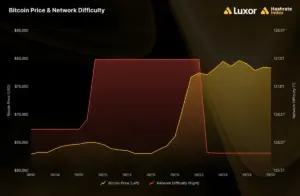
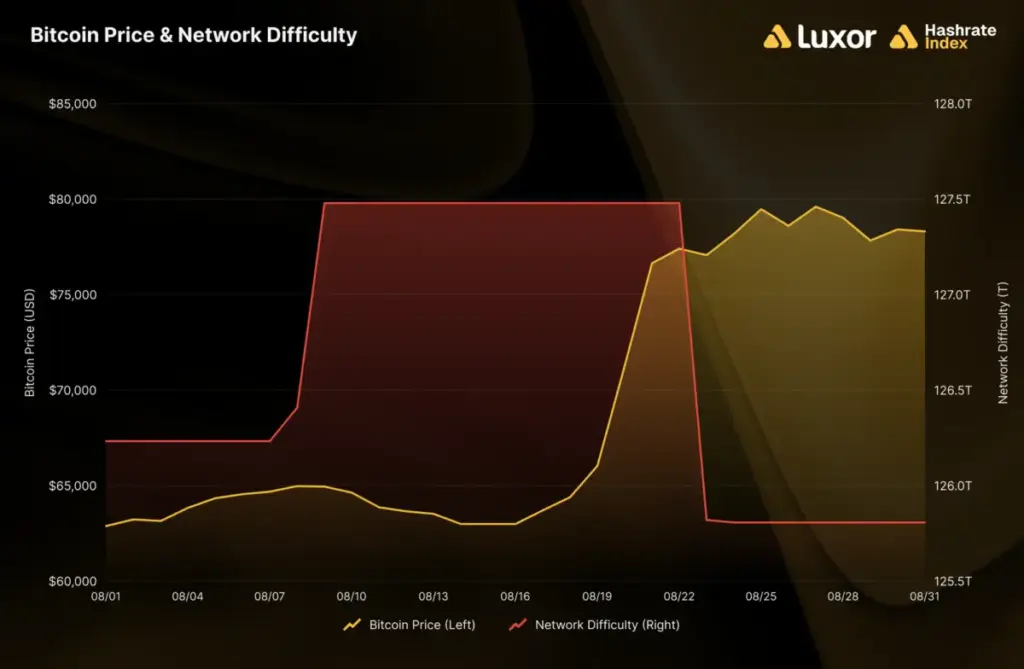
August unfolded as a month of two distinct halves. For the first nineteen days, the market extended the quiet trend observed in July, with hashprice holding within a tight band between $31 and $33 while Bitcoin traded in the low $60,000 range. Then, the market experienced a sharp repricing event. Bitcoin surged 19.0% over the course of three days, dragging hashprice upward alongside it.
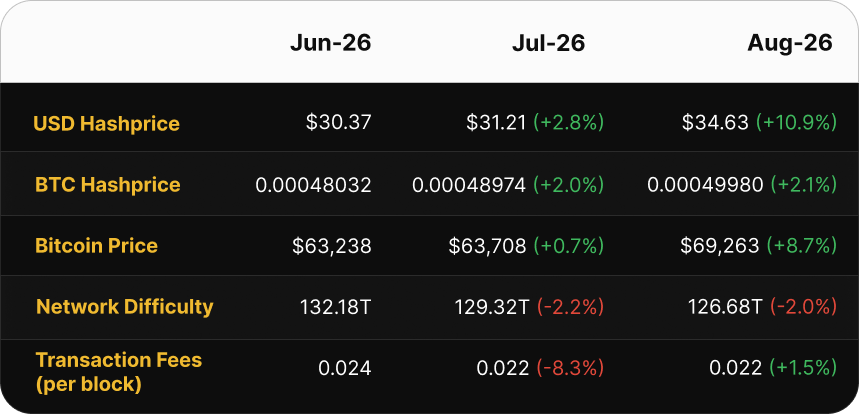
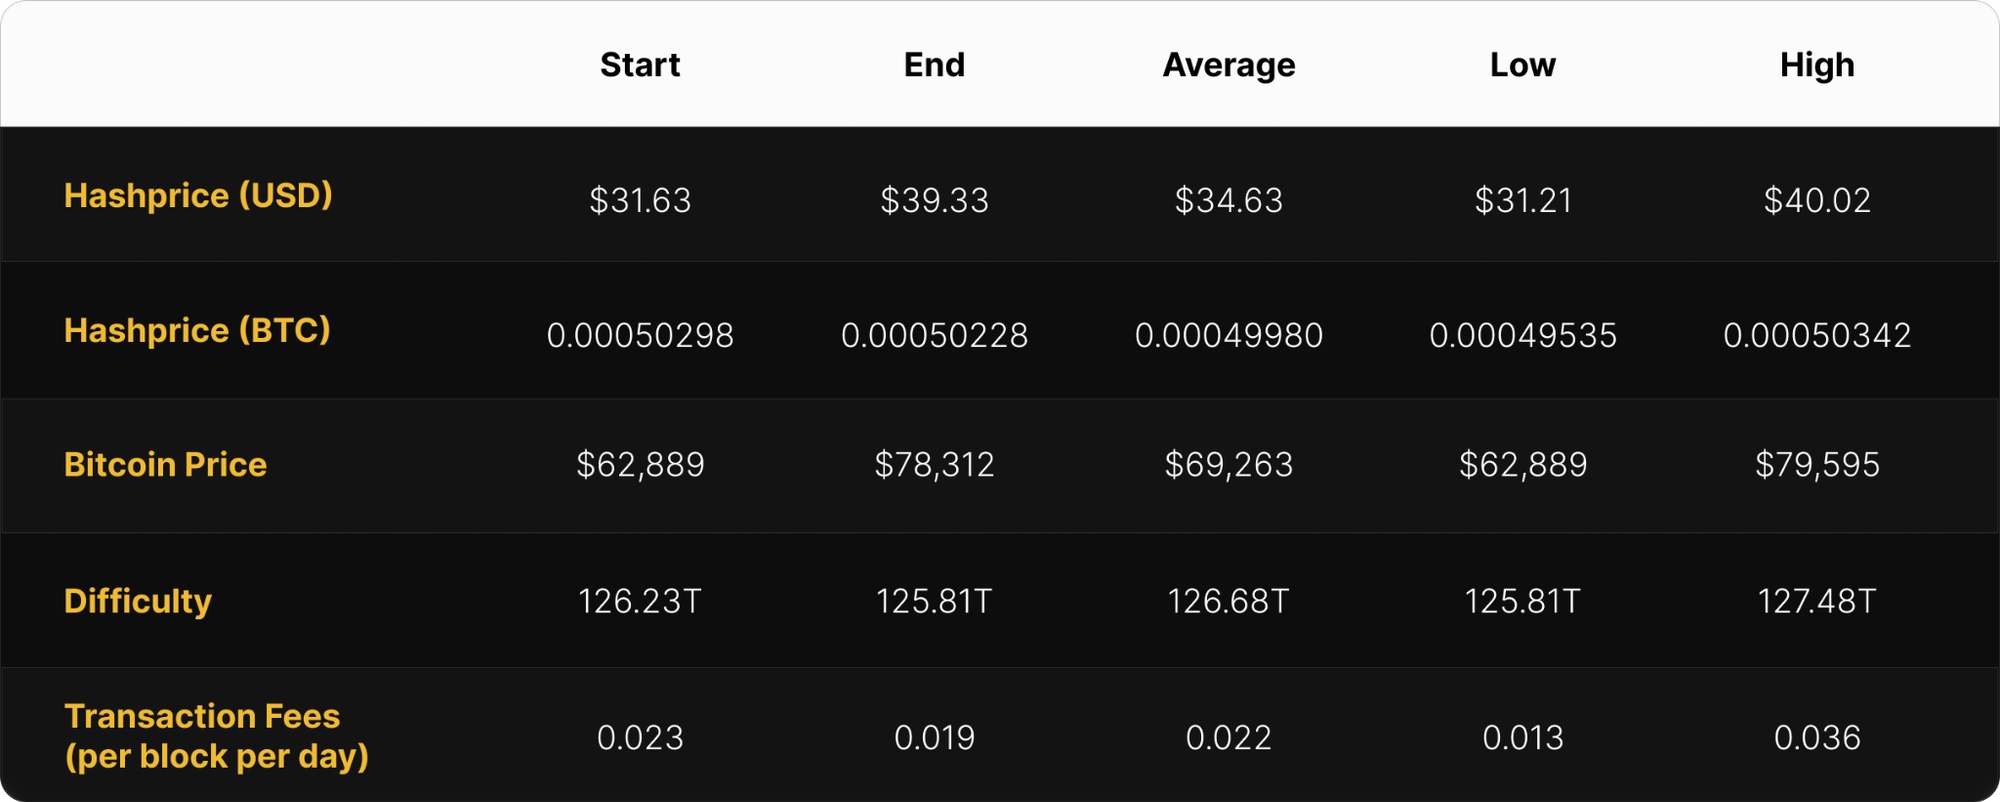
The monthly average USD hashprice rose from $31.21 to $34.63 per PH/s/day, marking a 10.9% increase and reaching the highest level since May, when it stood at $36.60. The month opened at $31.63, drifted to a monthly low of $31.21 on August 16, and ultimately closed at $39.33, representing a 24.4% increase from the open. The period from August 1 through August 19 averaged $31.90, while the final twelve days from August 20 through August 31 averaged $38.95. Eleven of the final twelve days settled above the $38 threshold, a valuation tier that had not been sustained since May 15.
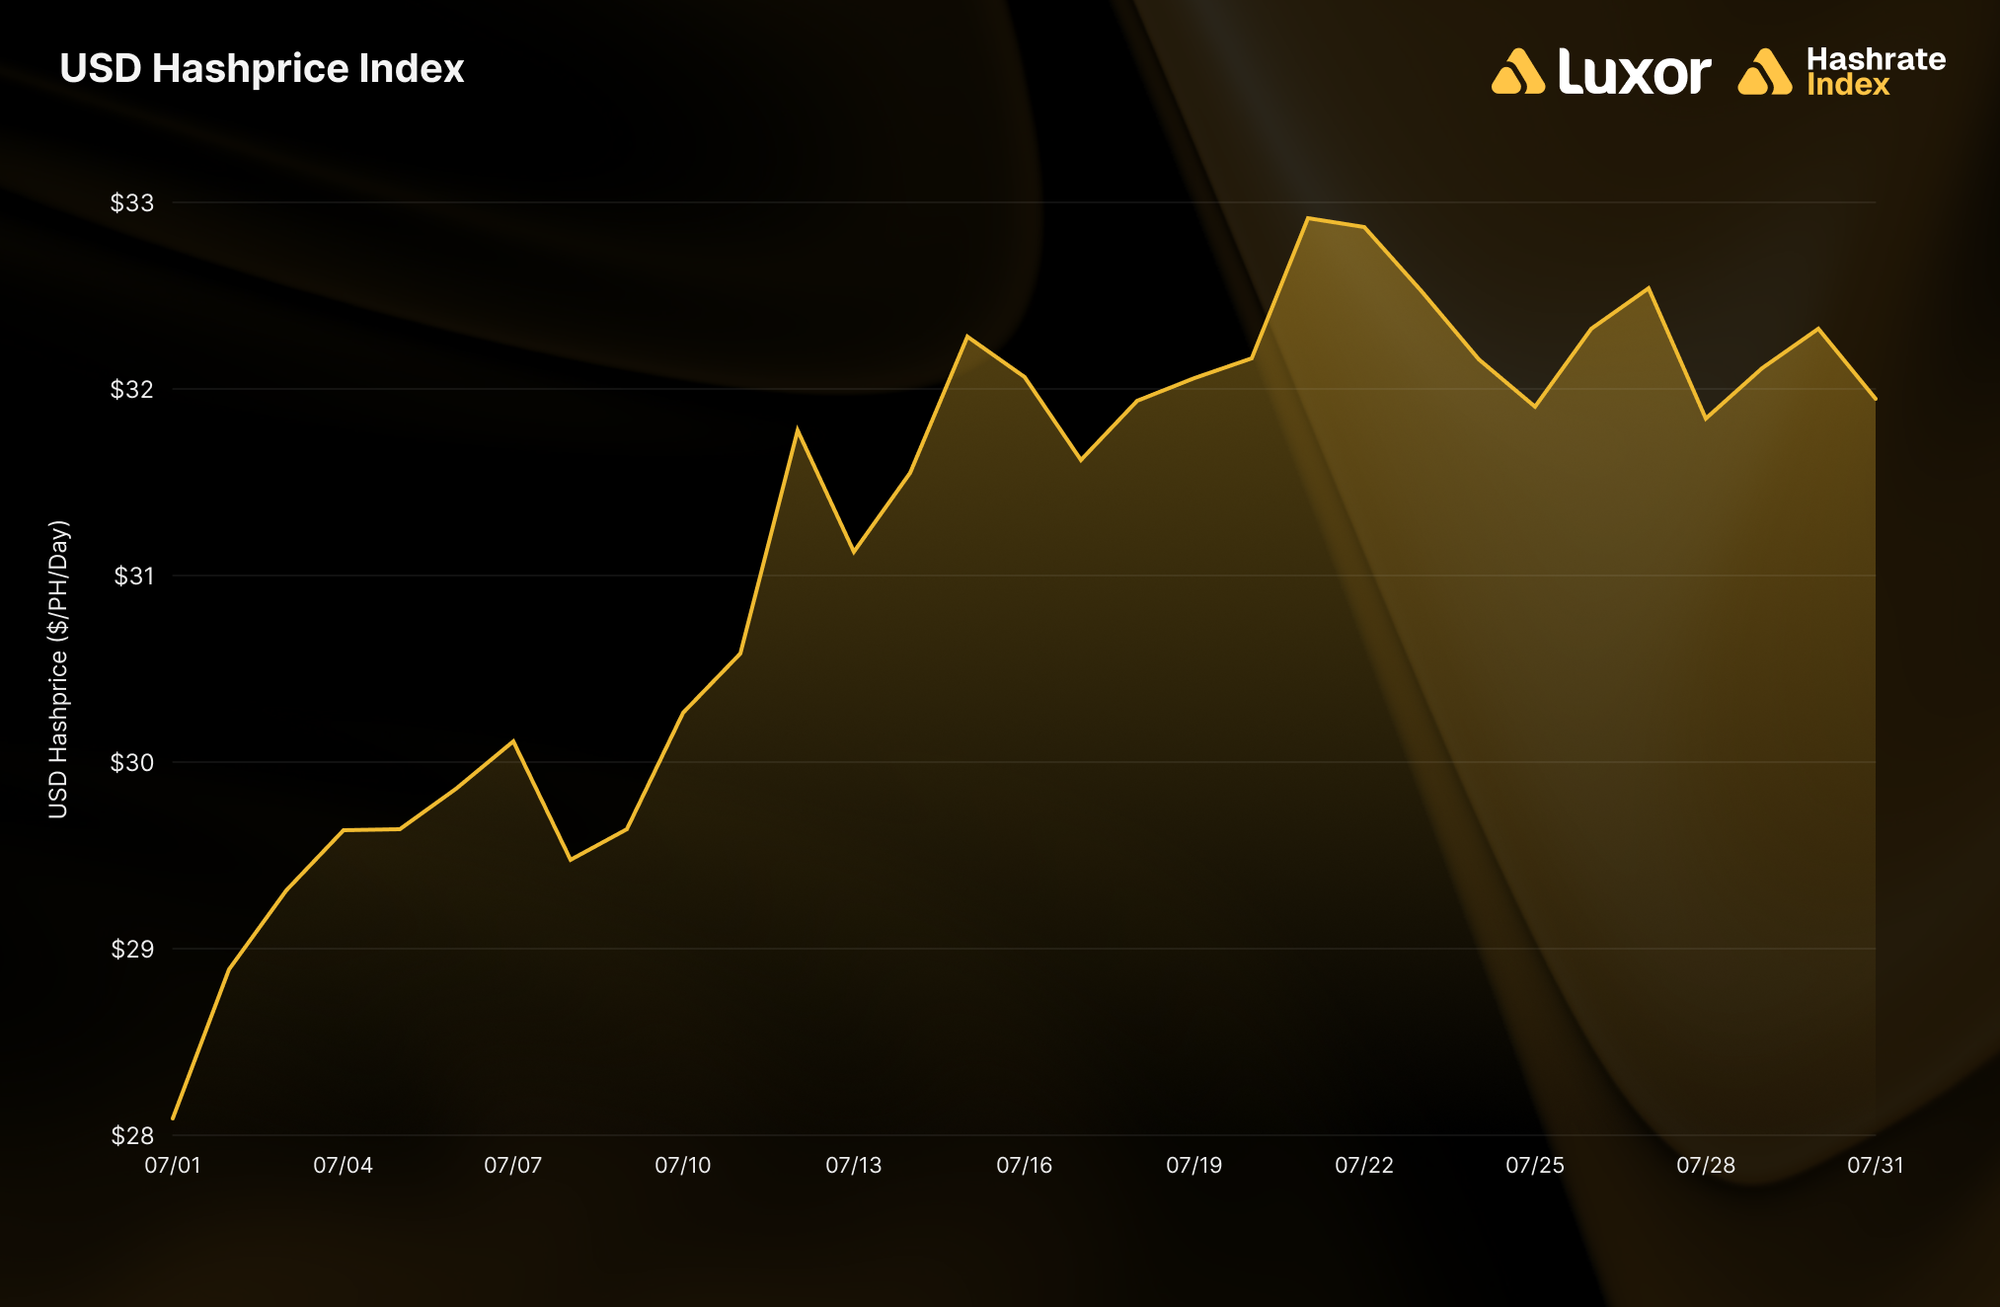
The 24.4% open-to-close surge ranks 18th out of 116 months recorded since 2017, making it the largest monthly open-to-close gain since November 2024, which saw a 30.6% increase. Furthermore, August 27 recorded a spot hashprice of $40.02, marking the first time hashprice crossed the $40 mark since January 19—a span of 220 days. However, this milestone proved fleeting, lasting for just a single day. By comparison, monthly averages throughout 2025 ranged between $37.89 and $59.38 with a mean of $50.68, placing August 2026 roughly 32% below the historical baseline of the previous year.
BTC Price and Significant Market Catalysts
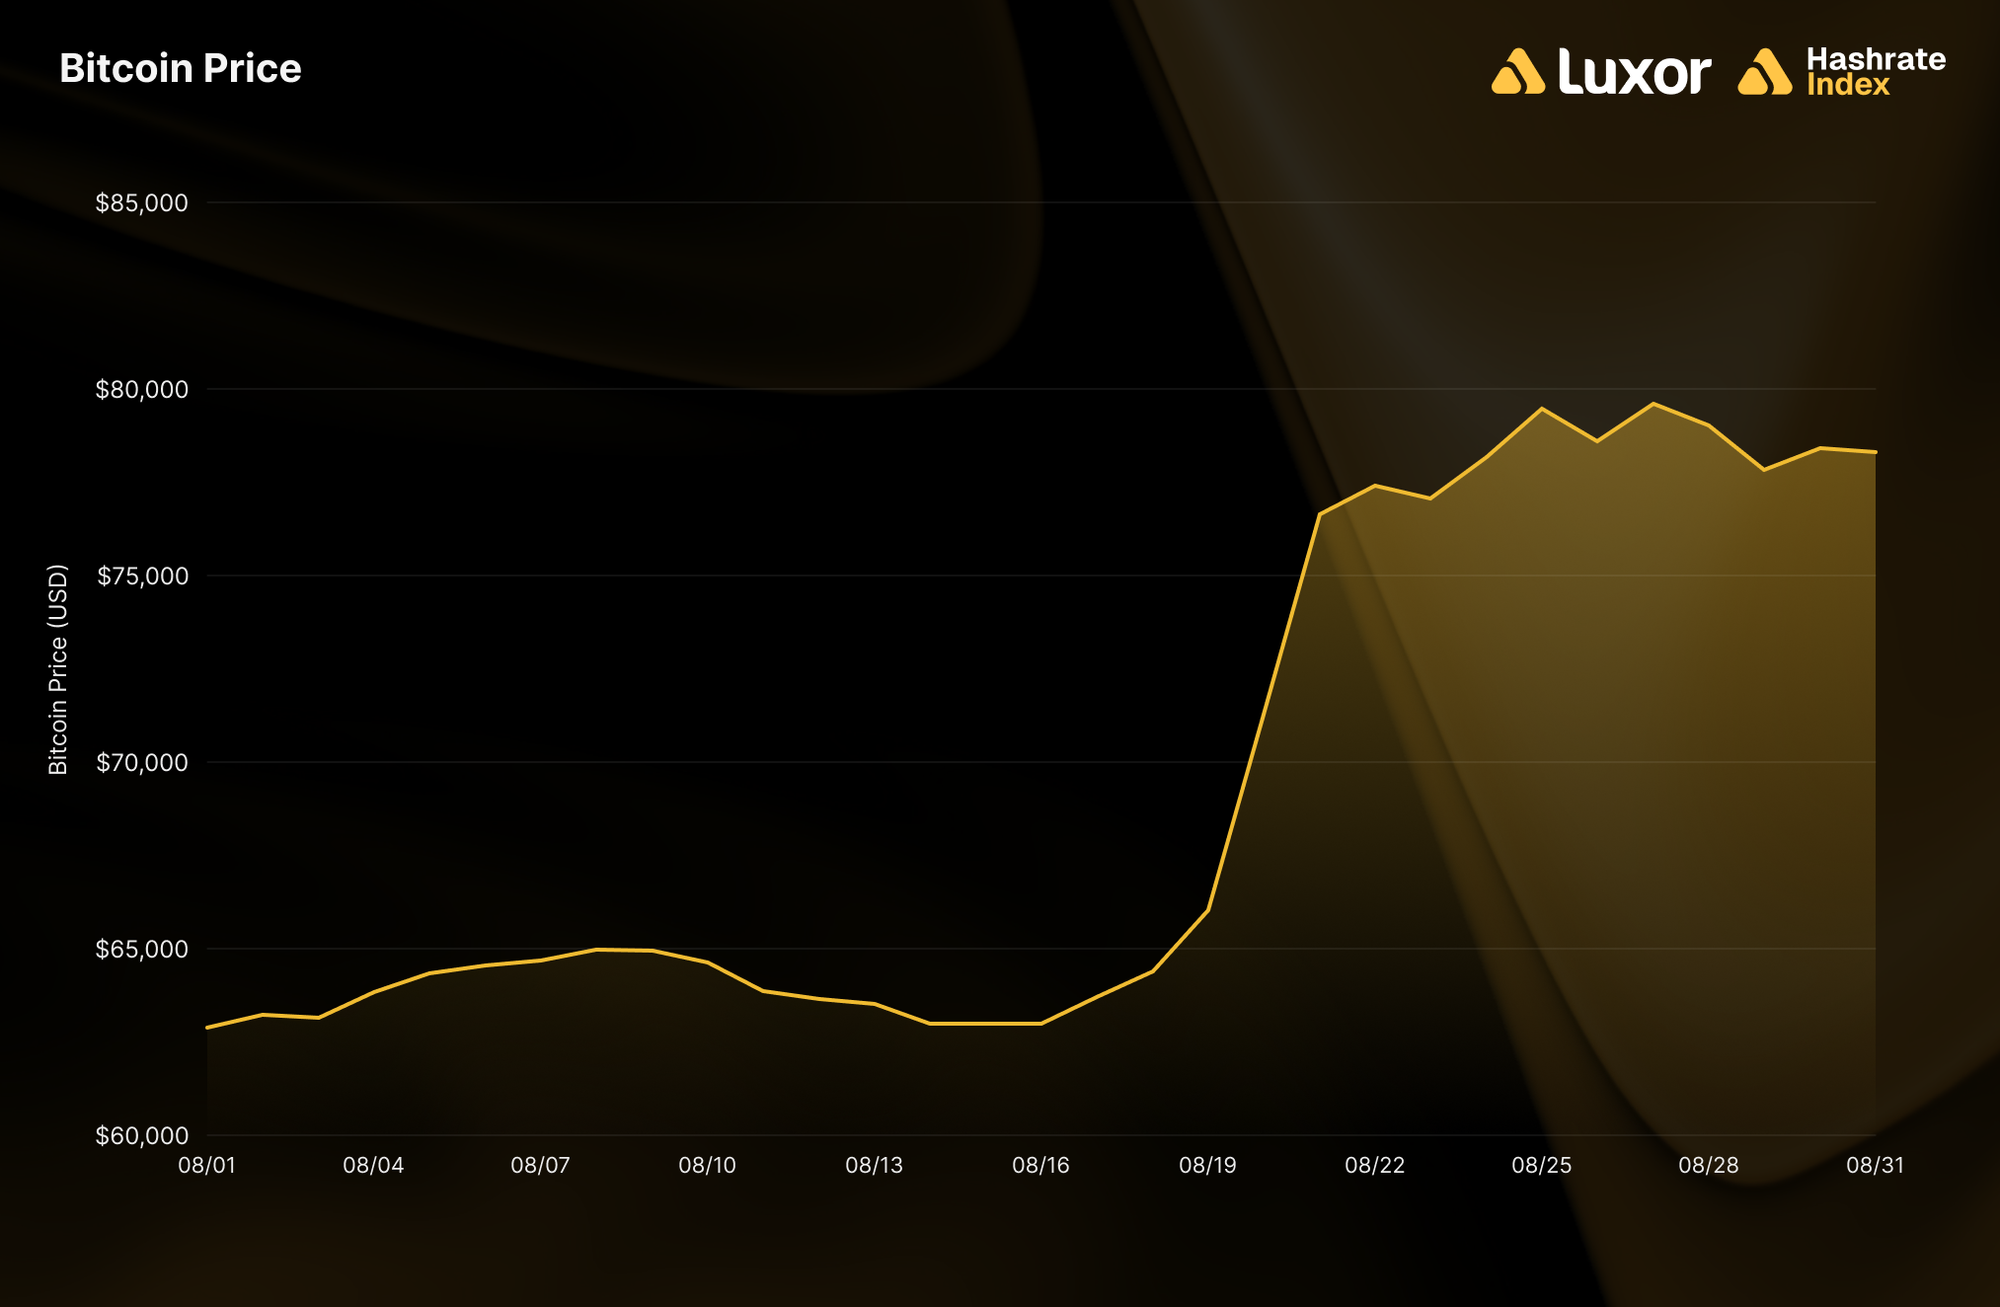
Bitcoin opened August at $62,889 and closed at $78,312, registering a 24.5% gain while averaging $69,263, up 8.7% month-over-month. The asset reached a monthly peak of $79,595 on August 27. This performance ranks as the 22nd largest monthly gain out of 116 months since 2017, representing the strongest monthly advance since November 2024’s 38.8% surge.
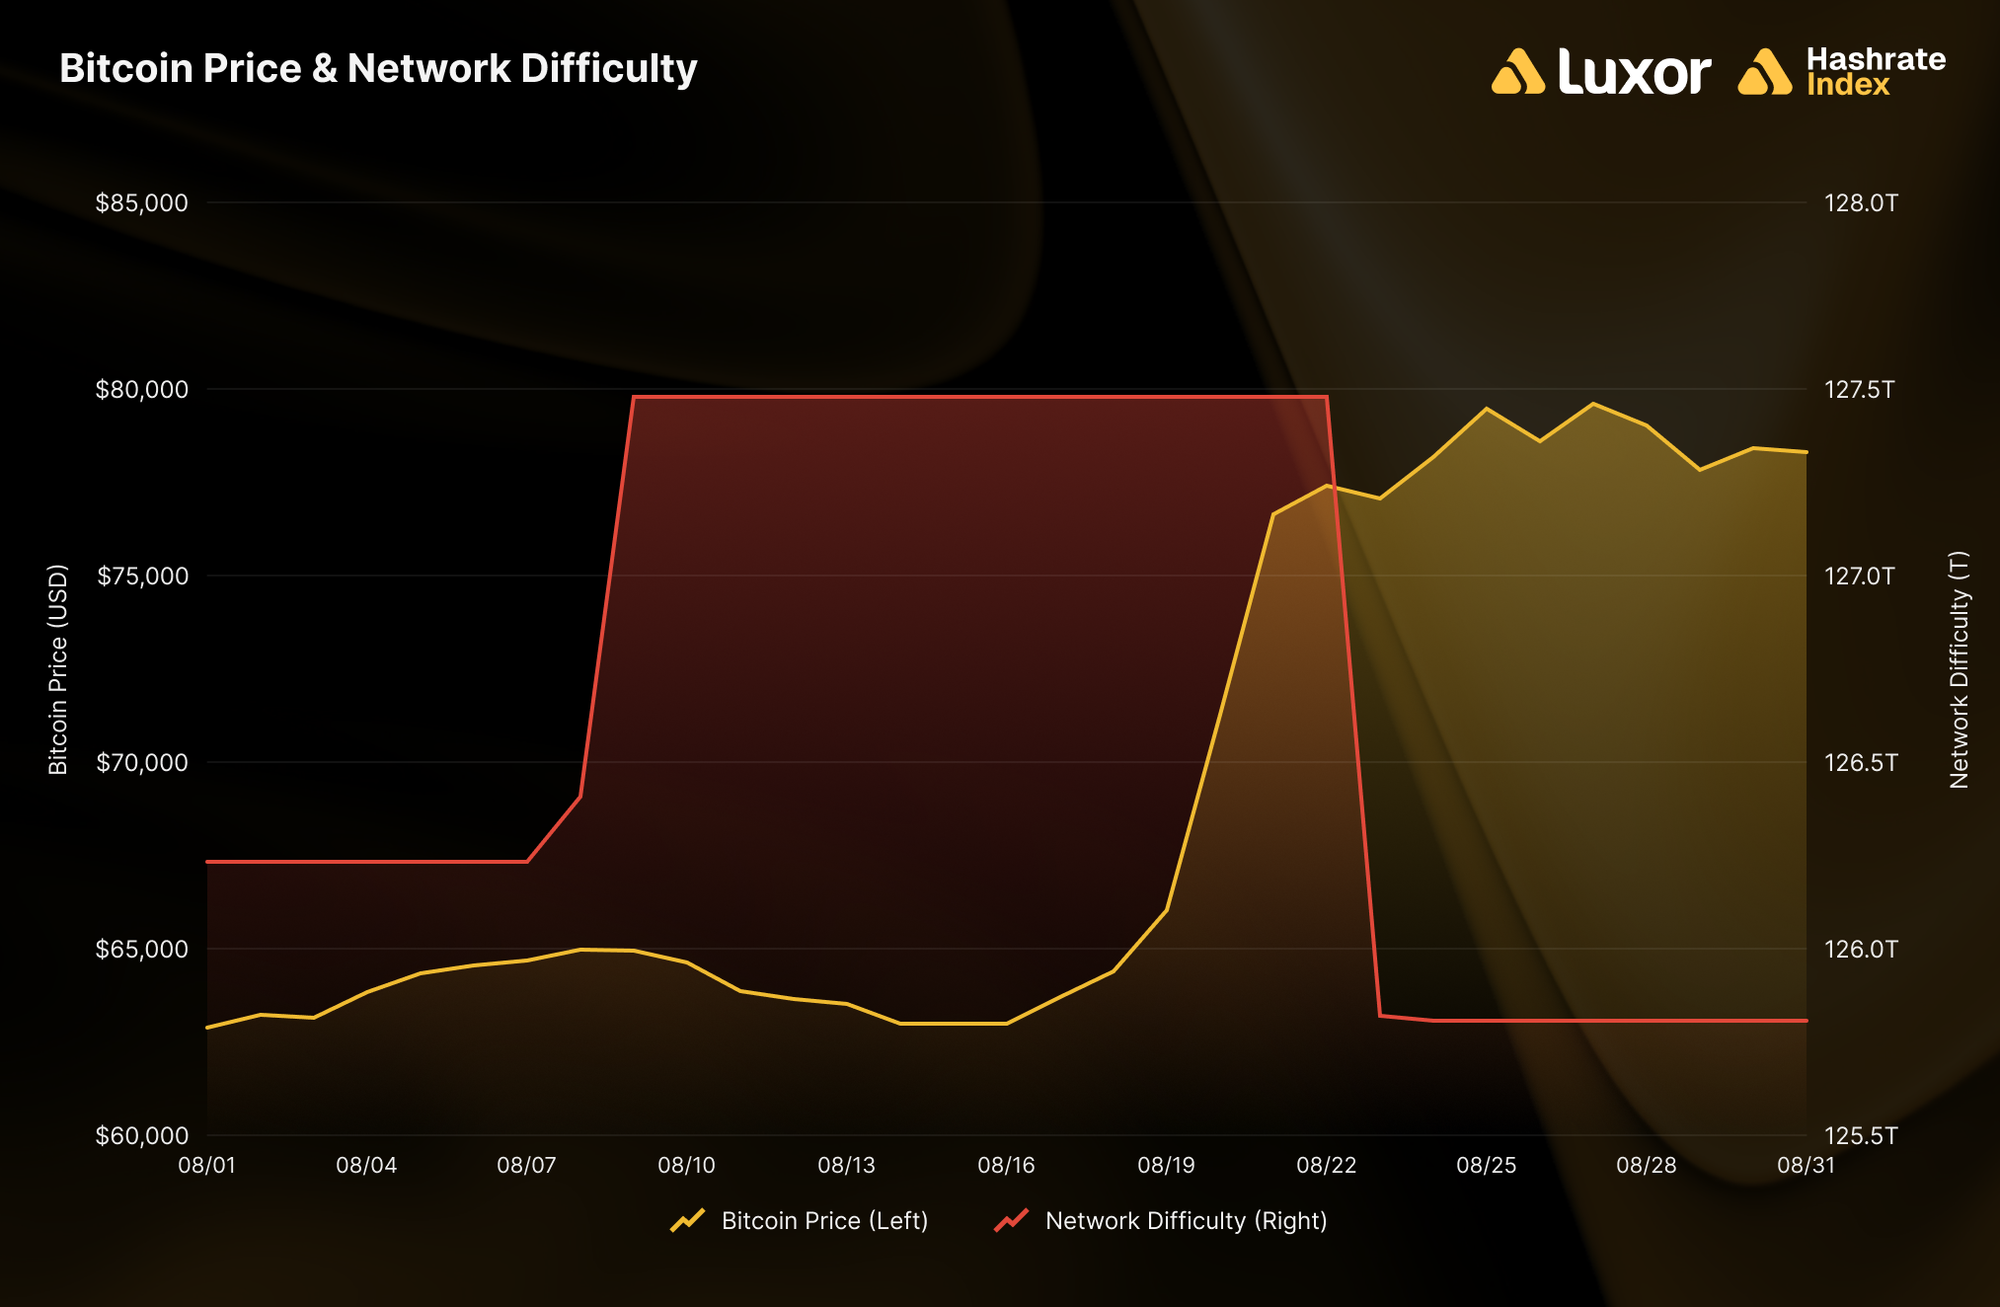
A vast portion of this momentum was concentrated into a narrow window of just two days. Bitcoin averaged $66,032 on August 19, jumped to $71,280 on August 20, and climbed further to $76,635 on August 21. The 7.9% gain recorded on August 20 stands as the largest single-day price increase since the April 2024 halving, while August 21’s 7.5% rise ranks as the third-largest single-day gain over the same post-halving period. Combined, these sessions formed the largest two-day move, up 16.1%, and the largest three-day move, up 19.0%, since the halving, ranking 19th and 20th respectively among all multi-day moves recorded since 2017.
This sudden price appreciation was driven by a convergence of policy, legislative, and market factors. On August 18, the Securities and Exchange Commission proposed Regulation Crypto Assets, marking the agency’s first major rulemaking dedicated specifically to crypto offerings, which proposed exempting capital raises of up to $5 million and $75 million from traditional Securities Act registration requirements. On August 19, the U.S. Treasury announced plans to at least double its long-end buyback operations from $2 billion to $4 billion, effective September 9, which contributed to a nearly 10 basis point drop in 30-year Treasury yields from a 19-year high. On August 20, President Trump publicly urged the Senate to pass the Clarity Act. Simultaneously, these macro catalysts triggered the liquidation of approximately $2.7 billion in short positions across the broader crypto market. Spot Bitcoin ETFs acted as a confirming force rather than a primary driver, pulling in $3.52 billion in August inflows compared to a modest $172 million in July, finishing positive on 16 of 21 trading sessions and lifting assets under management from $76.3 billion to $99.6 billion.
The upward trajectory encountered its first major obstacle on August 28 during the Jackson Hole Economic Symposium. Federal Reserve Chair Kevin Warsh delivered a keynote speech characterizing recent summer inflation readings as insufficient to signal a clear trend toward the central bank’s target. Following these remarks, CME FedWatch probabilities for a September interest rate hike spiked from a range of 33% to 40% up to 57% to 66%. Bitcoin subsequently retreated by 1.5% the following day. Despite closing at $78,312, Bitcoin finished August down 37.1% from its all-time peak of $124,485 reached on October 6, 2025, though this represented an improvement over the 48.9% discount at the end of July and the 52.6% trough recorded in June. The asset remained 18.7% below its 2026 high of $96,278 established on January 15.
Network Difficulty and Block Dynamics
Network difficulty averaged 126.68T during August, marking a 2.0% decline from July levels. The period saw two scheduled adjustments: a 0.99% increase on August 8 that lifted difficulty from 126.23T to 127.48T, followed by a 1.31% downward adjustment on August 23 that brought it down to 125.81T. The net result was a negligible 0.34% change across the month, representing a stark contrast to July’s 5.71% reduction and resulting in a relatively flat operational environment.
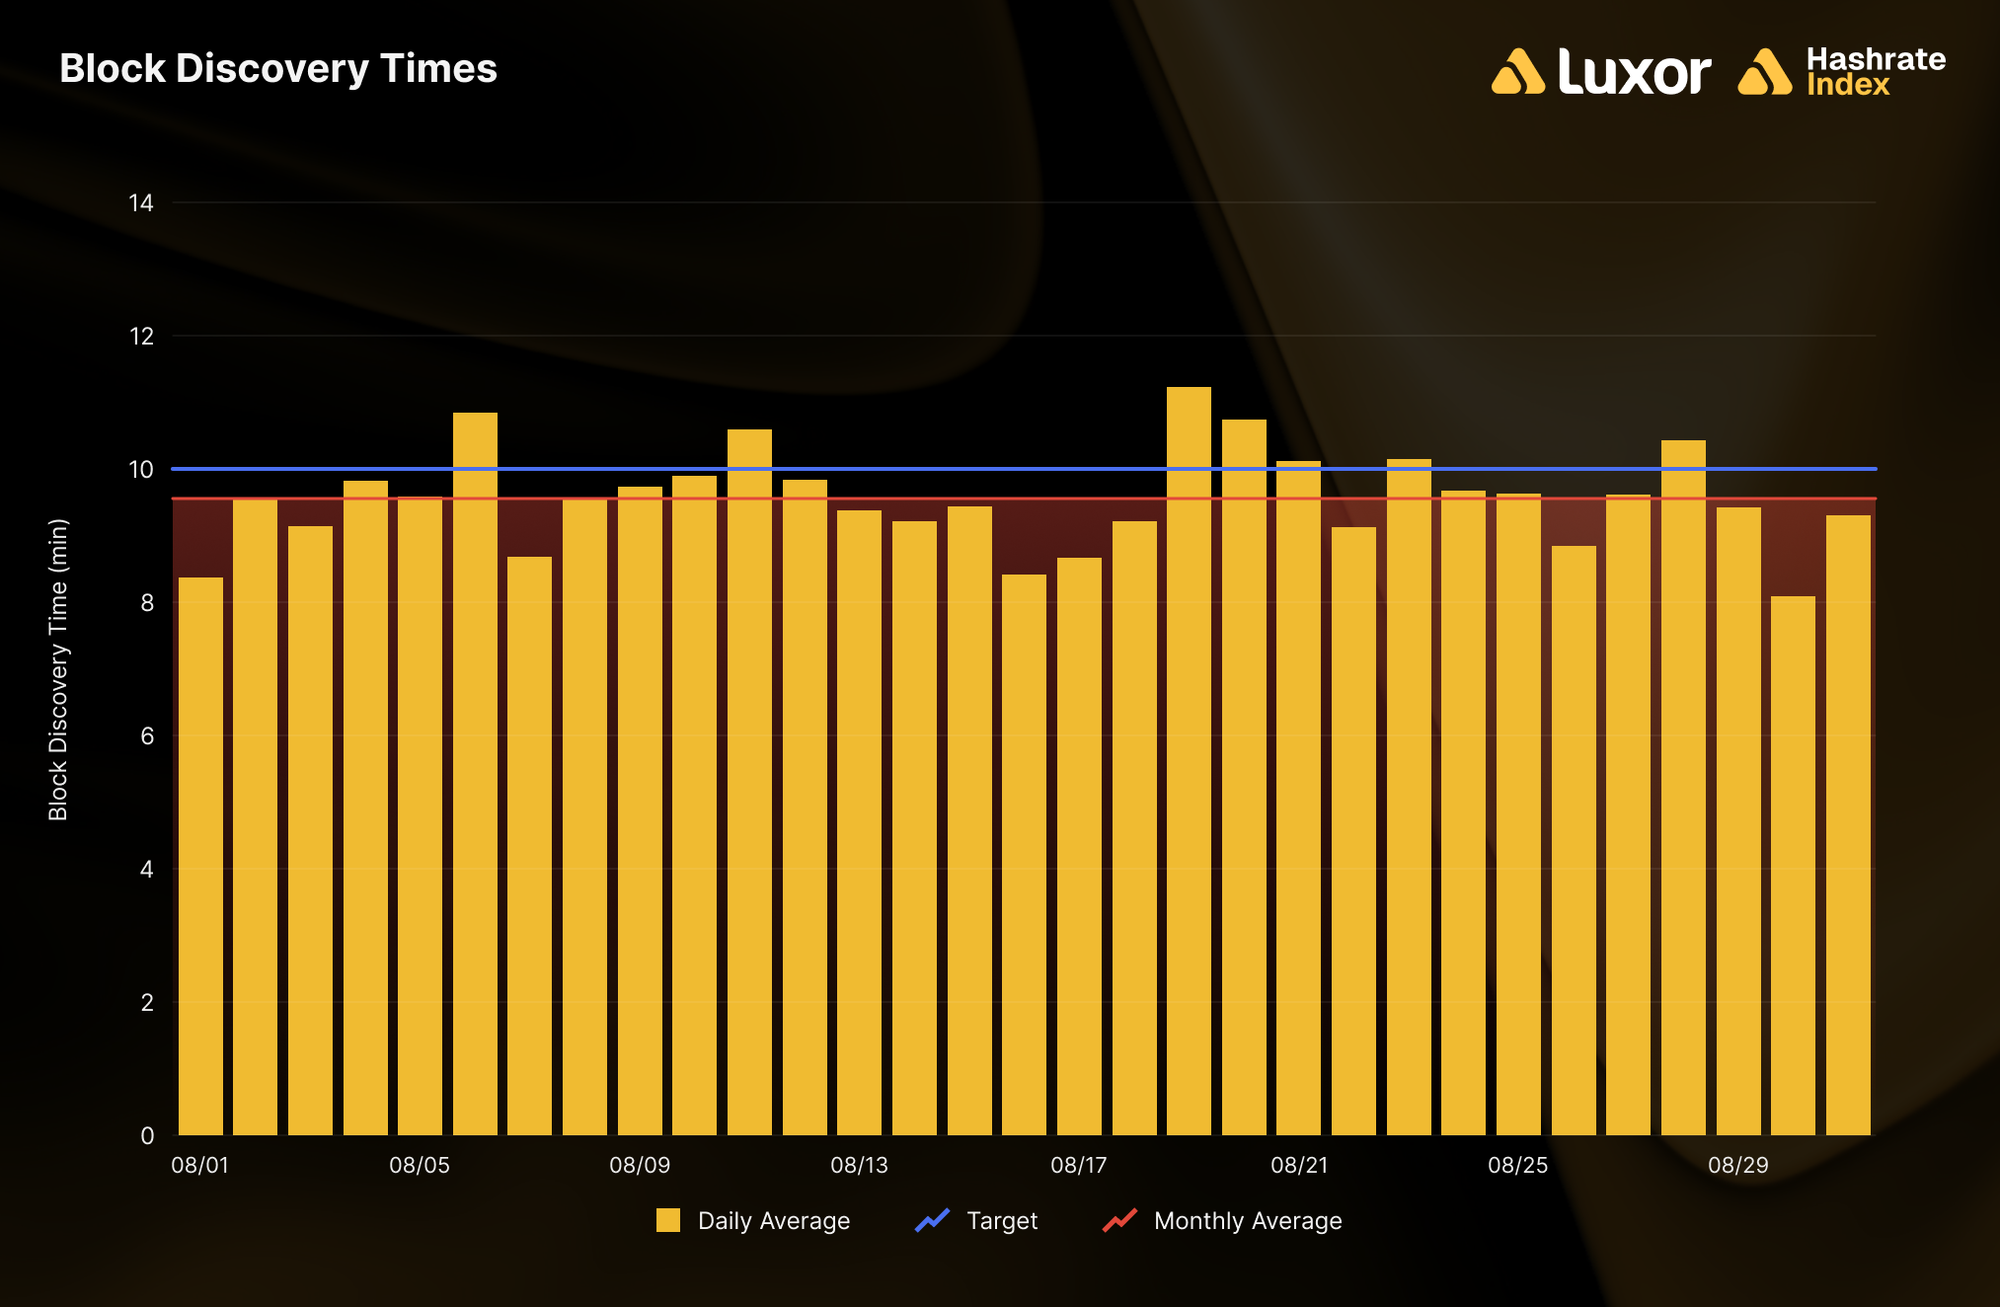
Block times averaged 9 minutes and 34 seconds, faster than July’s average of 9 minutes and 55 seconds. Across the month, 24 out of 31 days recorded average block times below the 10-minute target, led by a fastest daily average of 8 minutes and 6 seconds on August 30. The network produced blocks 4.6% faster than prevailing difficulty levels implied, indicating that marginal hashrate that had previously gone offline during the market contractions of June and July was steadily returning to operations. A subsequent adjustment on September 5 confirmed this trend with a 1.31% upward correction.
The August 23 difficulty reduction marked the twelfth consecutive adjustment below the 139.70T threshold, which equates to the 1 EH/s network scale marker, maintaining a streak that has persisted since March 20. The ongoing drag from Texas’s Four-Coincident-Peak transmission cost mechanism continued to impact local operators; August’s two adjustments averaged a 0.16% decrease, contrasting sharply with the historical August norm of a 2.0% increase recorded between 2022 and 2025.
Transaction Fees and Revenue Realities
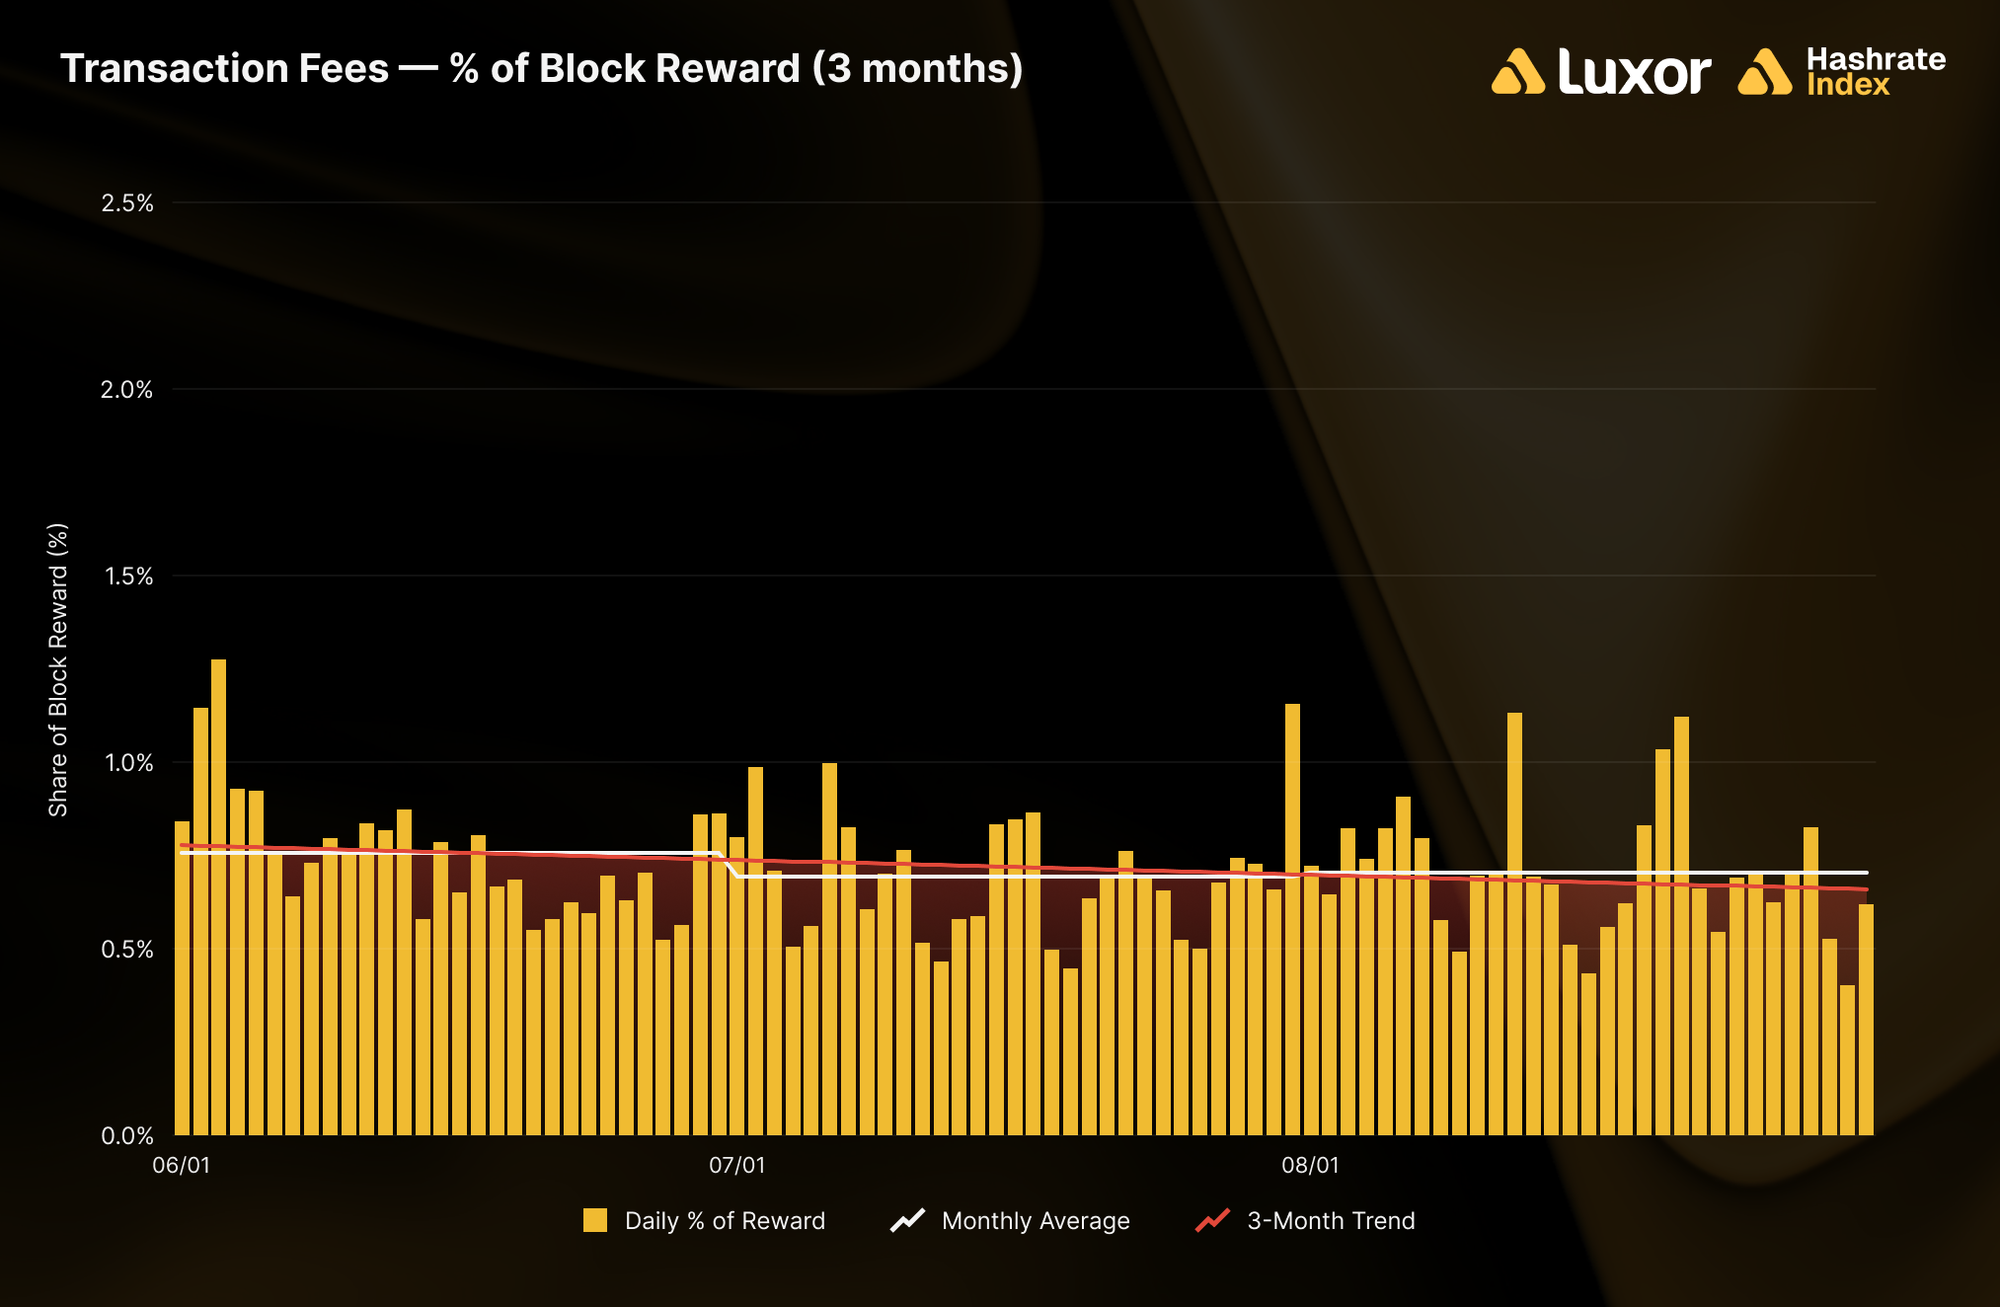
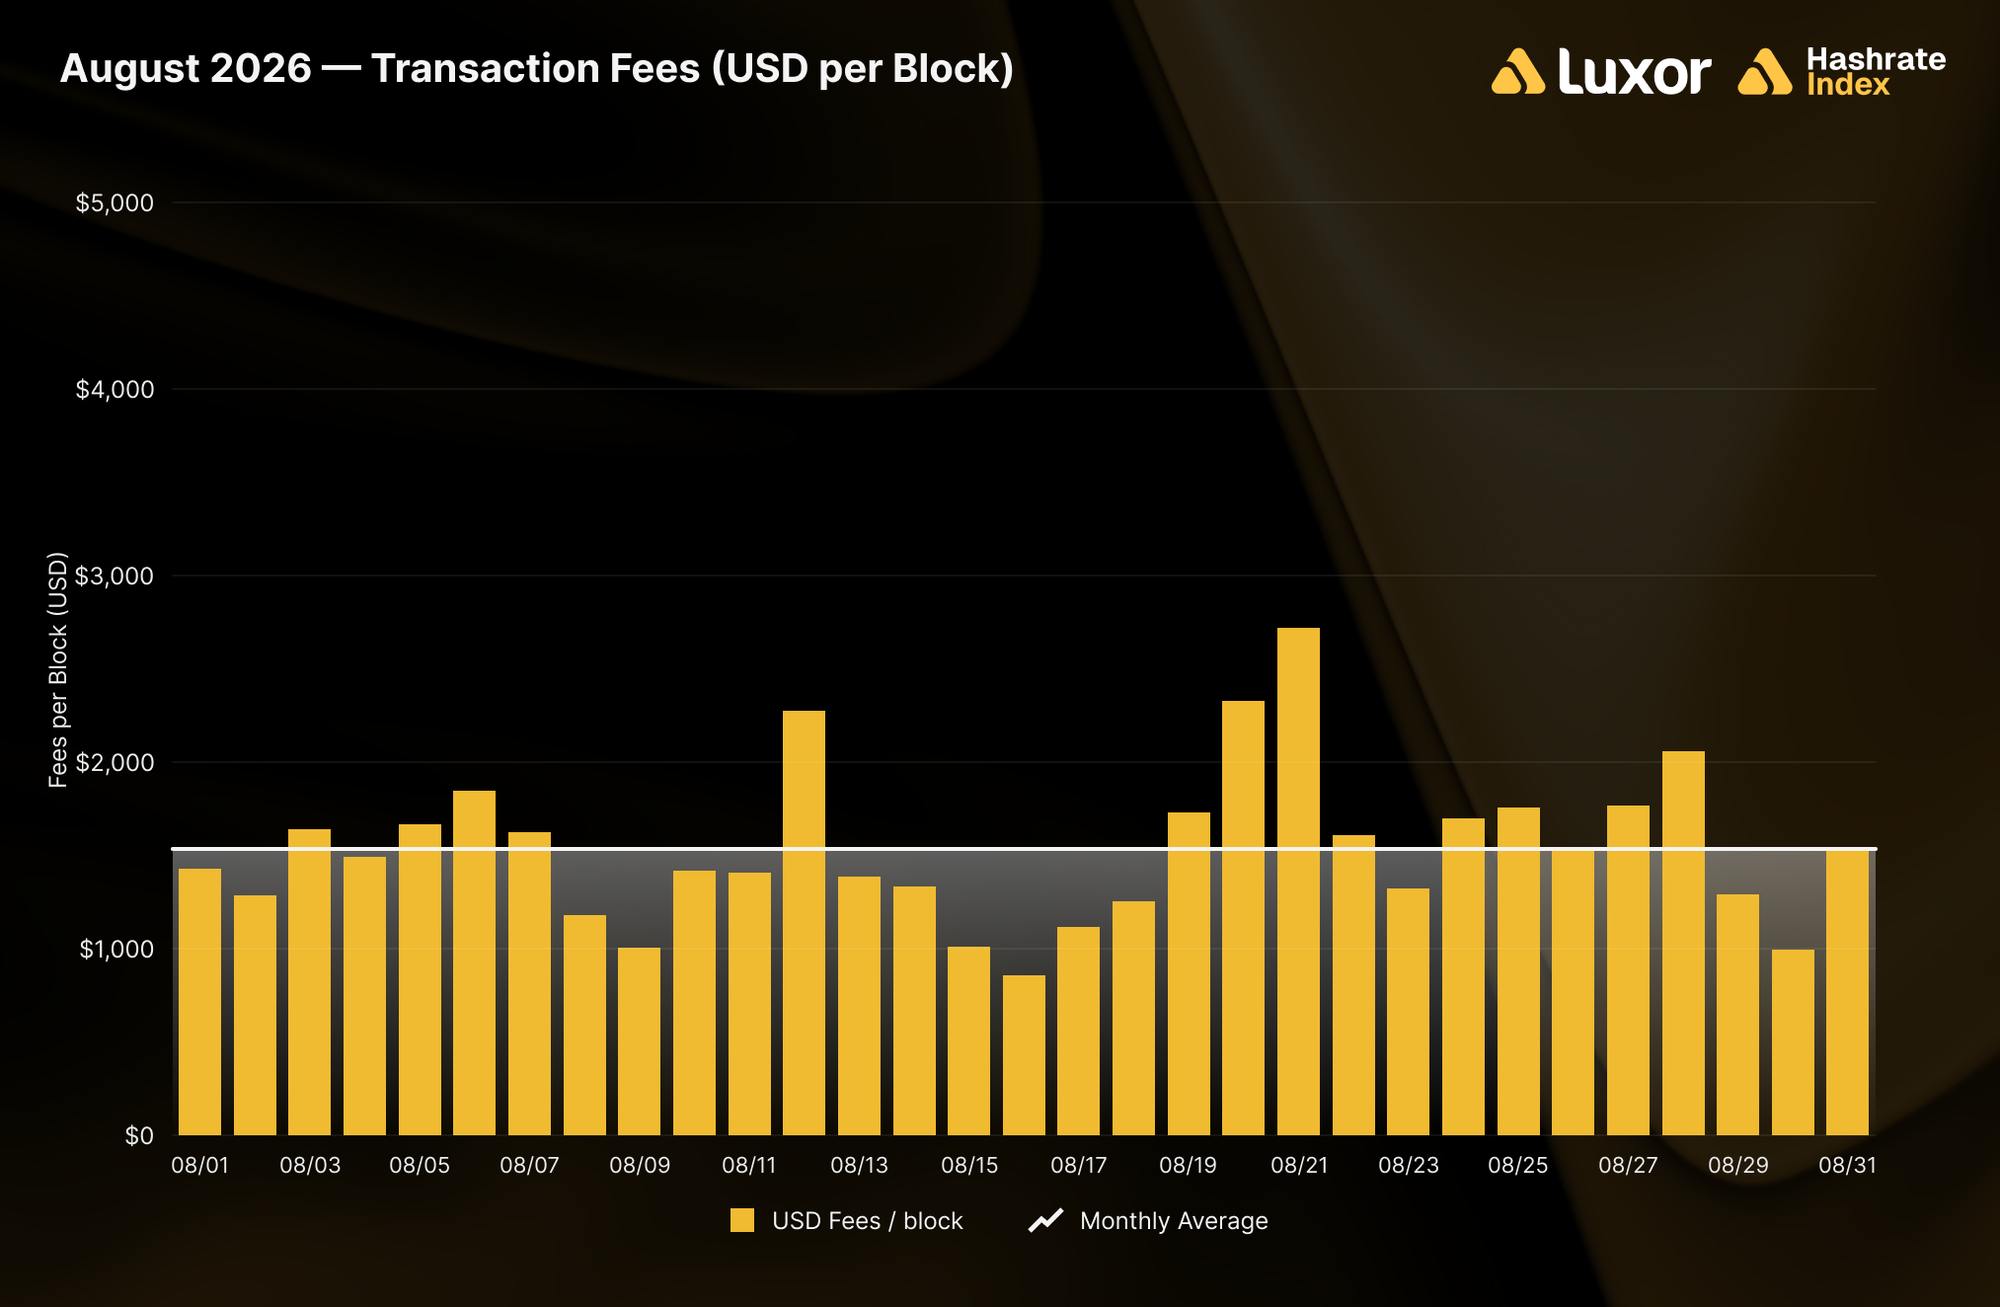
Average fee collection rose by 1.5% to 0.02218 BTC per block. Fees accounted for 0.70% of total block rewards, marking the fourteenth consecutive month that transaction fees have remained below 1% of total miner revenues. Measured in U.S. dollars, the average block generated approximately $1,534 in fees, a 10.3% increase, while total monthly network fee revenue reached roughly $6.85 million, also up 10.3%. While the Bitcoin-denominated figure remained essentially flat, the dollar-denominated increase was driven entirely by the appreciation of the underlying asset.
Fee collection hit a monthly peak on August 12, averaging 0.03576 BTC per block—61% higher than the monthly average. This spike was driven by a single anomalous event involving Block 962,142, mined by SpiderPool at 12:16 UTC. The block carried 1.82 BTC in total fees, of which 1.60 BTC originated from a single transaction. The user’s automated Replace-by-Fee script repeatedly escalated the transaction fee every second until the entire input value was consumed by the fee mechanism while the output amount fell to zero. Consequently, the user paid approximately $103,000 in fees to transmit nothing. Excluding this single transaction, the daily average for August 12 would have registered at 0.0230 BTC, aligning closely with the broader monthly baseline.
BTC Hashprice and Energy Dynamics
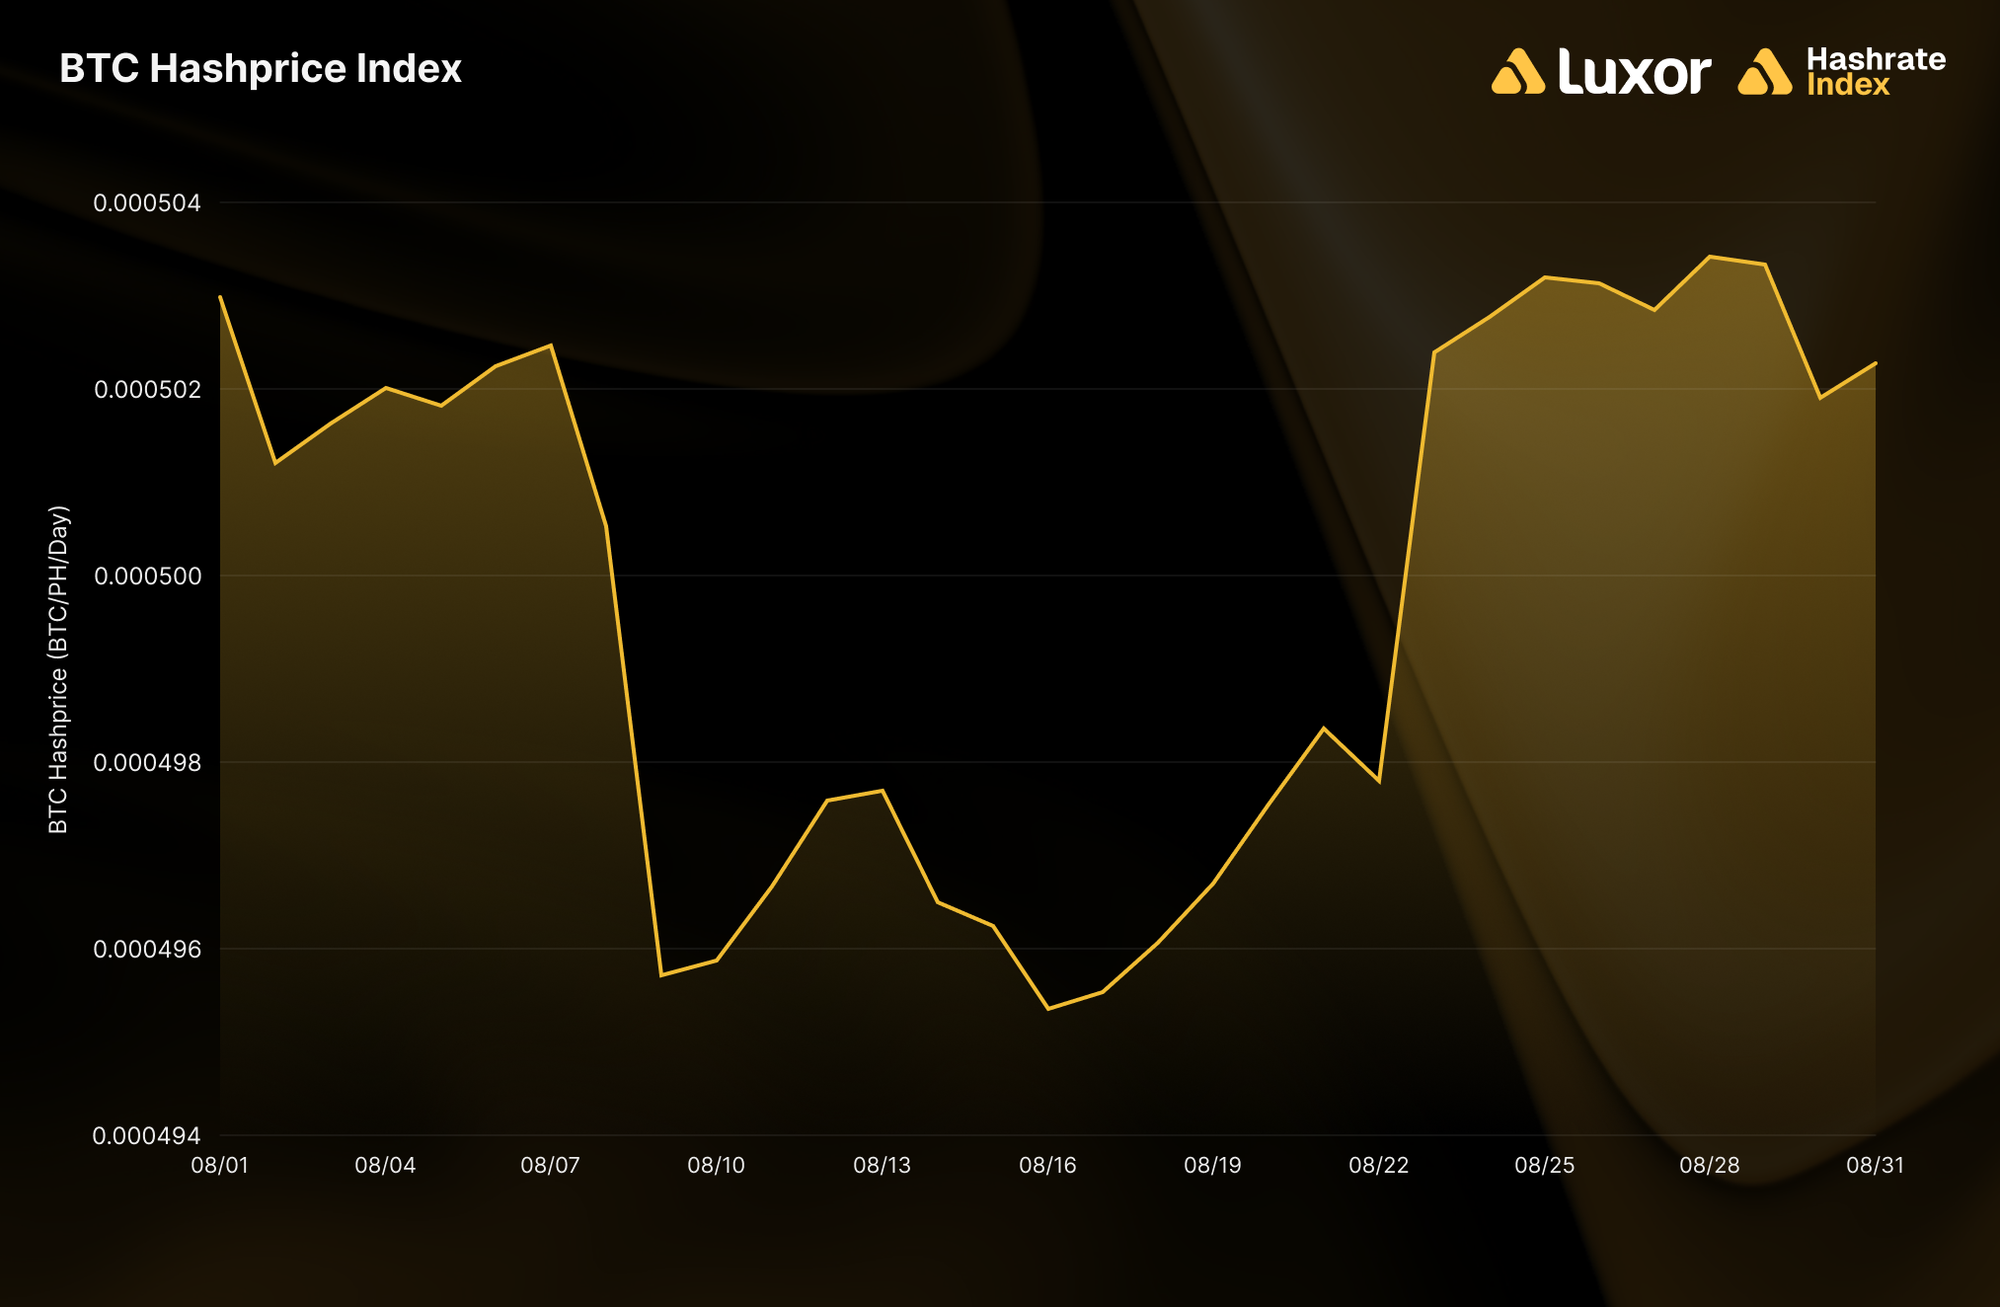
The monthly average Bitcoin-denominated hashprice rose 2.1% from 0.00048974 to 0.00049980 BTC per PH/s/day, marking the highest level recorded since July 2025, when it stood at 0.00051625 BTC. This relative strength was supported by lower average difficulty levels across the period. The BTC hashprice opened at 0.00050298, adjusted downward following the August 8 difficulty increase, recovered after the August 23 reduction, and closed the month at 0.00050228, down 0.1% overall.
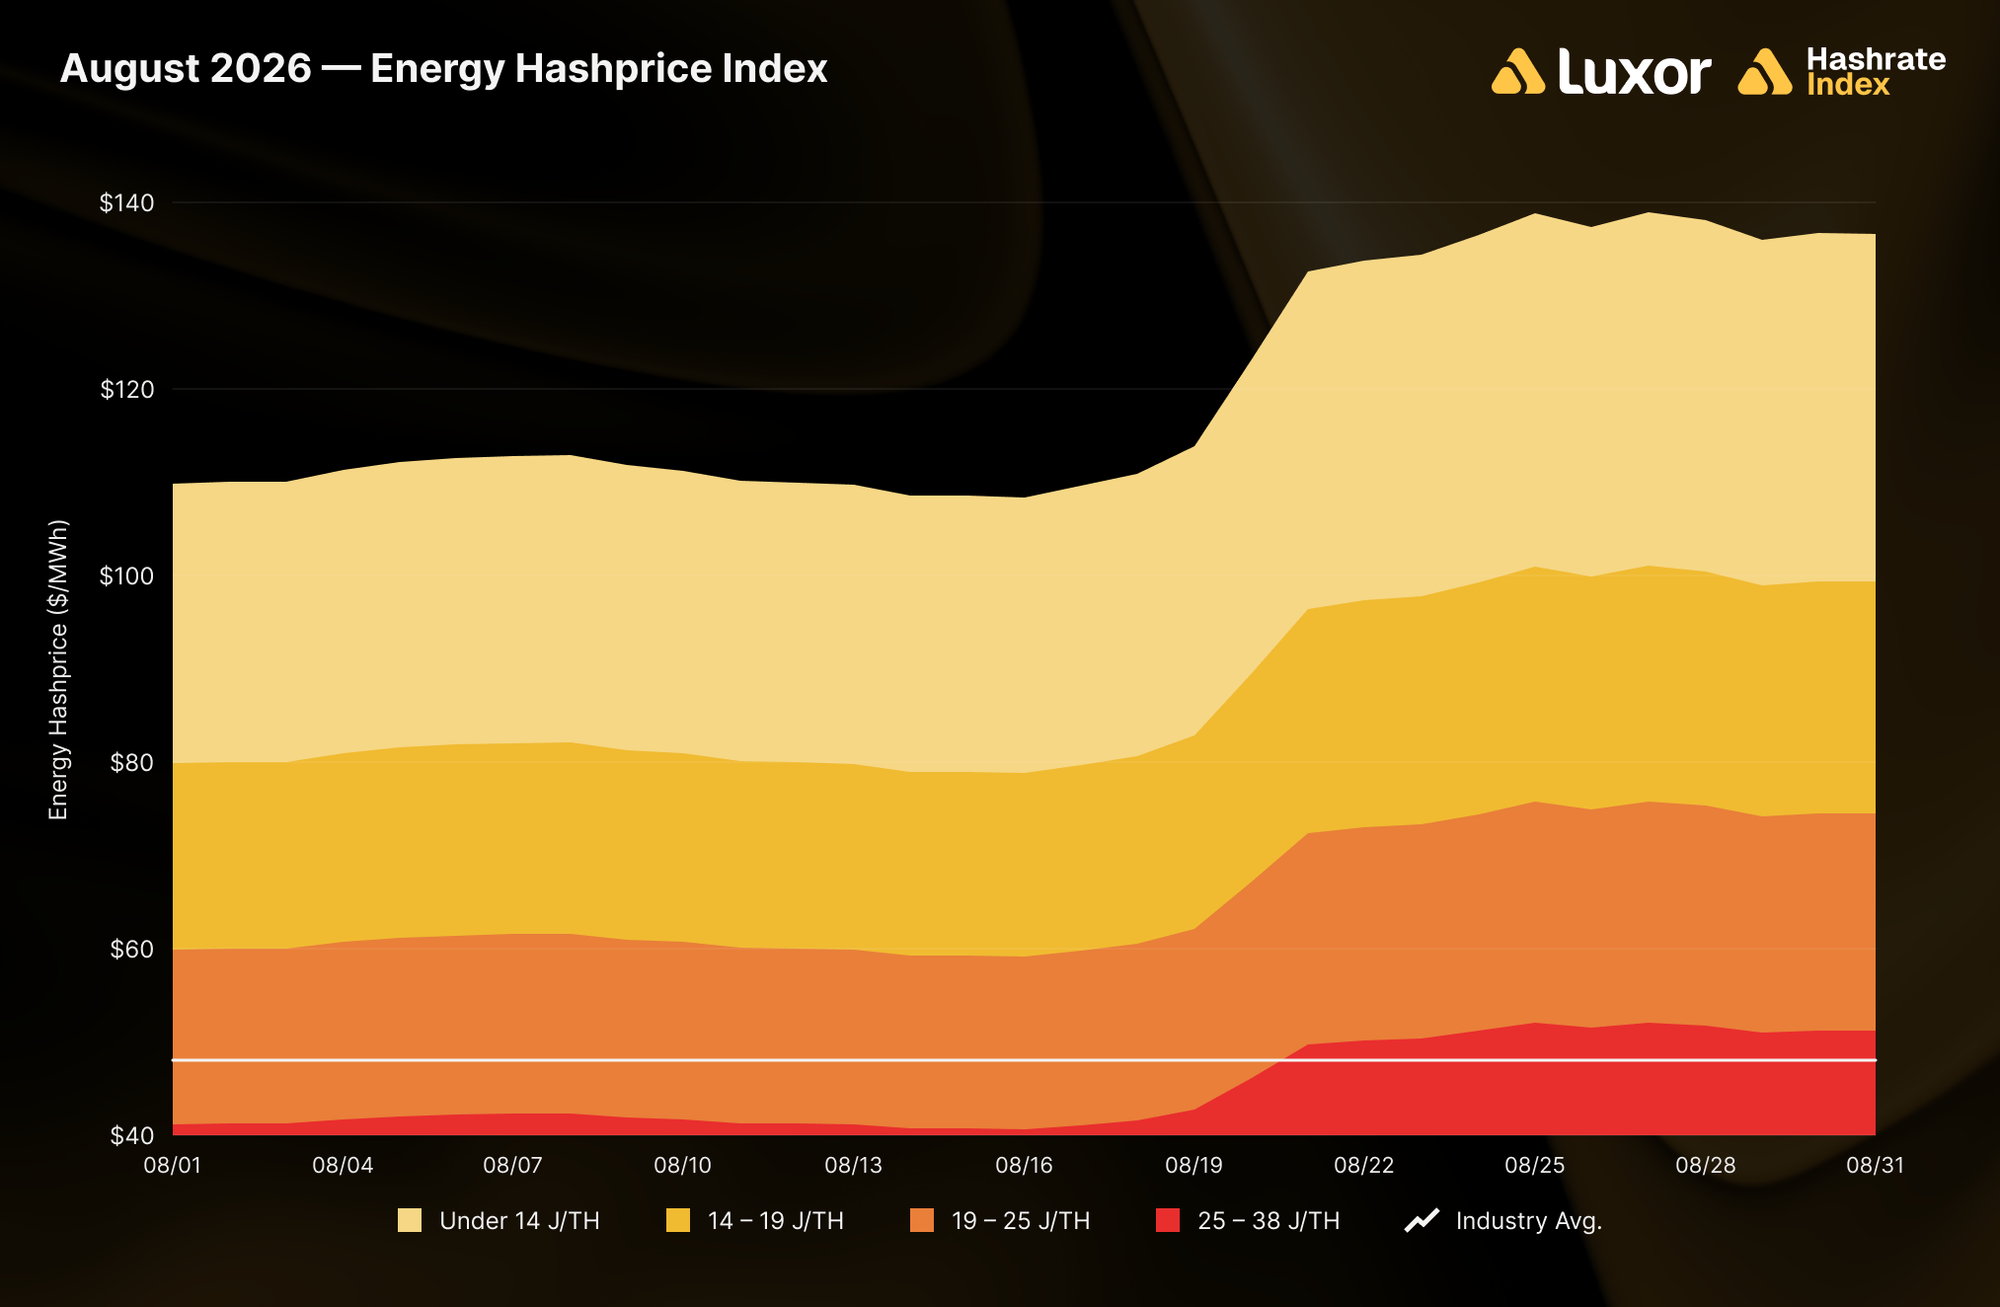
Energy hashprice trends provided a temporary reprieve for marginal mining fleets. Against a network-average power cost of roughly $48 per megawatt-hour, mining operations falling within the 25 to 38 joules per terahash efficiency tier spent a third consecutive month below breakeven on a monthly average basis. However, this cohort cleared the $48 power cost threshold on 11 out of 31 days, peaking at $52 per megawatt-hour on August 27 and sustaining levels above $51 through the end of the month. Meanwhile, the most efficient fleets concluded August generating over $135 per megawatt-hour in energy-adjusted returns.
Hashrate Market Activity and Forward Trading
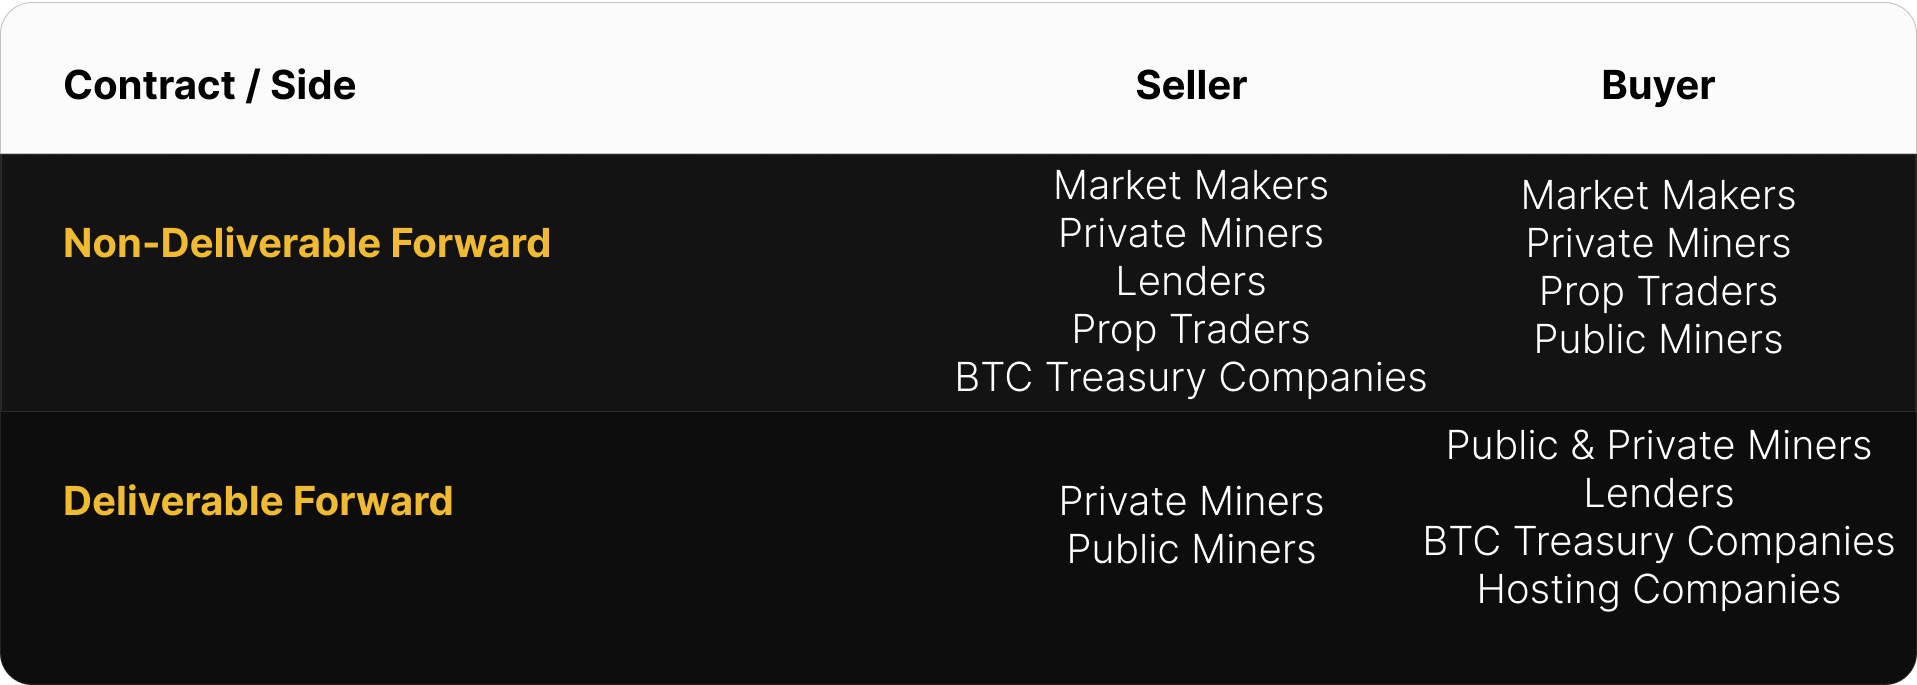
Analysis of the hashrate derivatives market highlights how forward contracts traded in preceding months and how the forward curve shifted in response to August’s market developments. Luxor’s USD and BTC-denominated forward markets reflected changing sentiment among market participants. Lenders remained active on the buy side of deliverable forward contracts, while public and private mining enterprises utilized the instruments to sell forward, secure immediate financing, and fund fleet expansion initiatives.
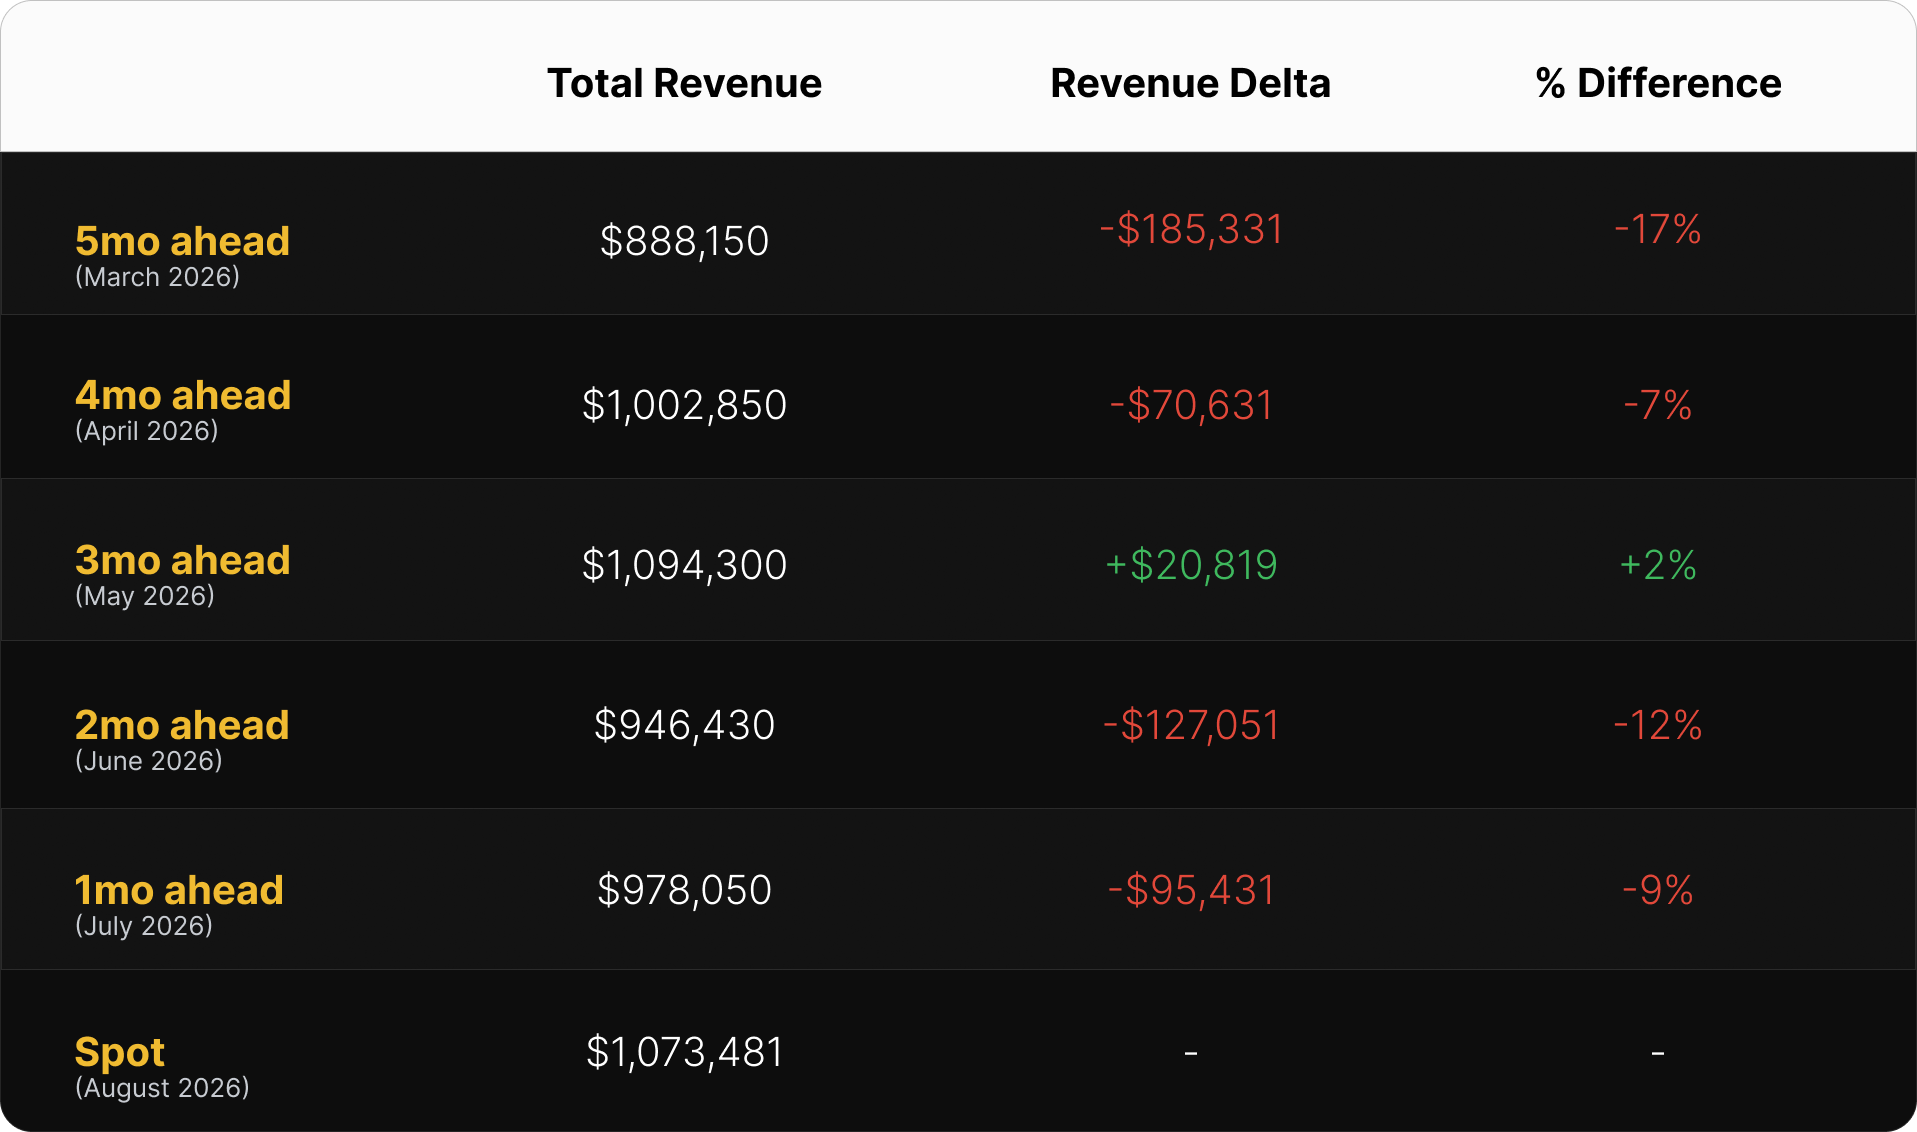
Because deliverable forwards are prepaid, they typically trade at a discount to non-deliverable forwards to compensate buyers for credit risk and the cost of capital. Pairing a deliverable forward with an offsetting non-deliverable contract allows lenders or corporate treasuries to lock in that spread as a fixed Bitcoin-denominated yield, or enables miners to secure non-dilutive financing. During August, this implied cost of capital ranged between 6% and 13% annualized.
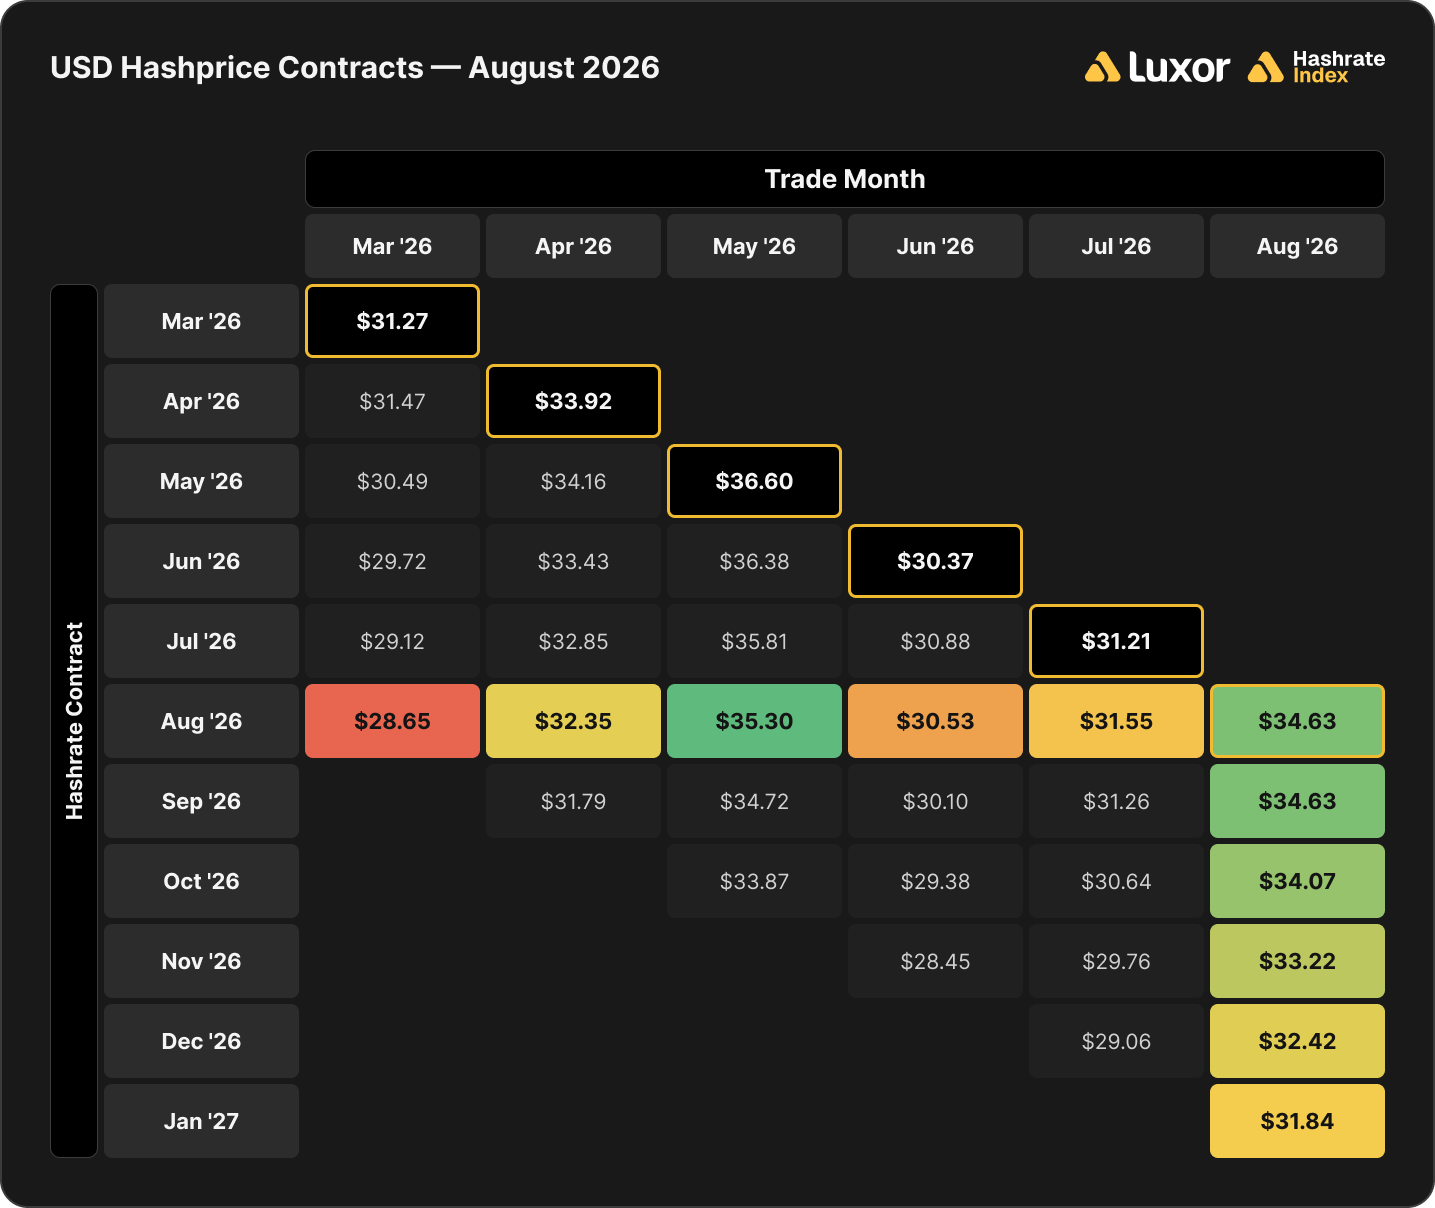
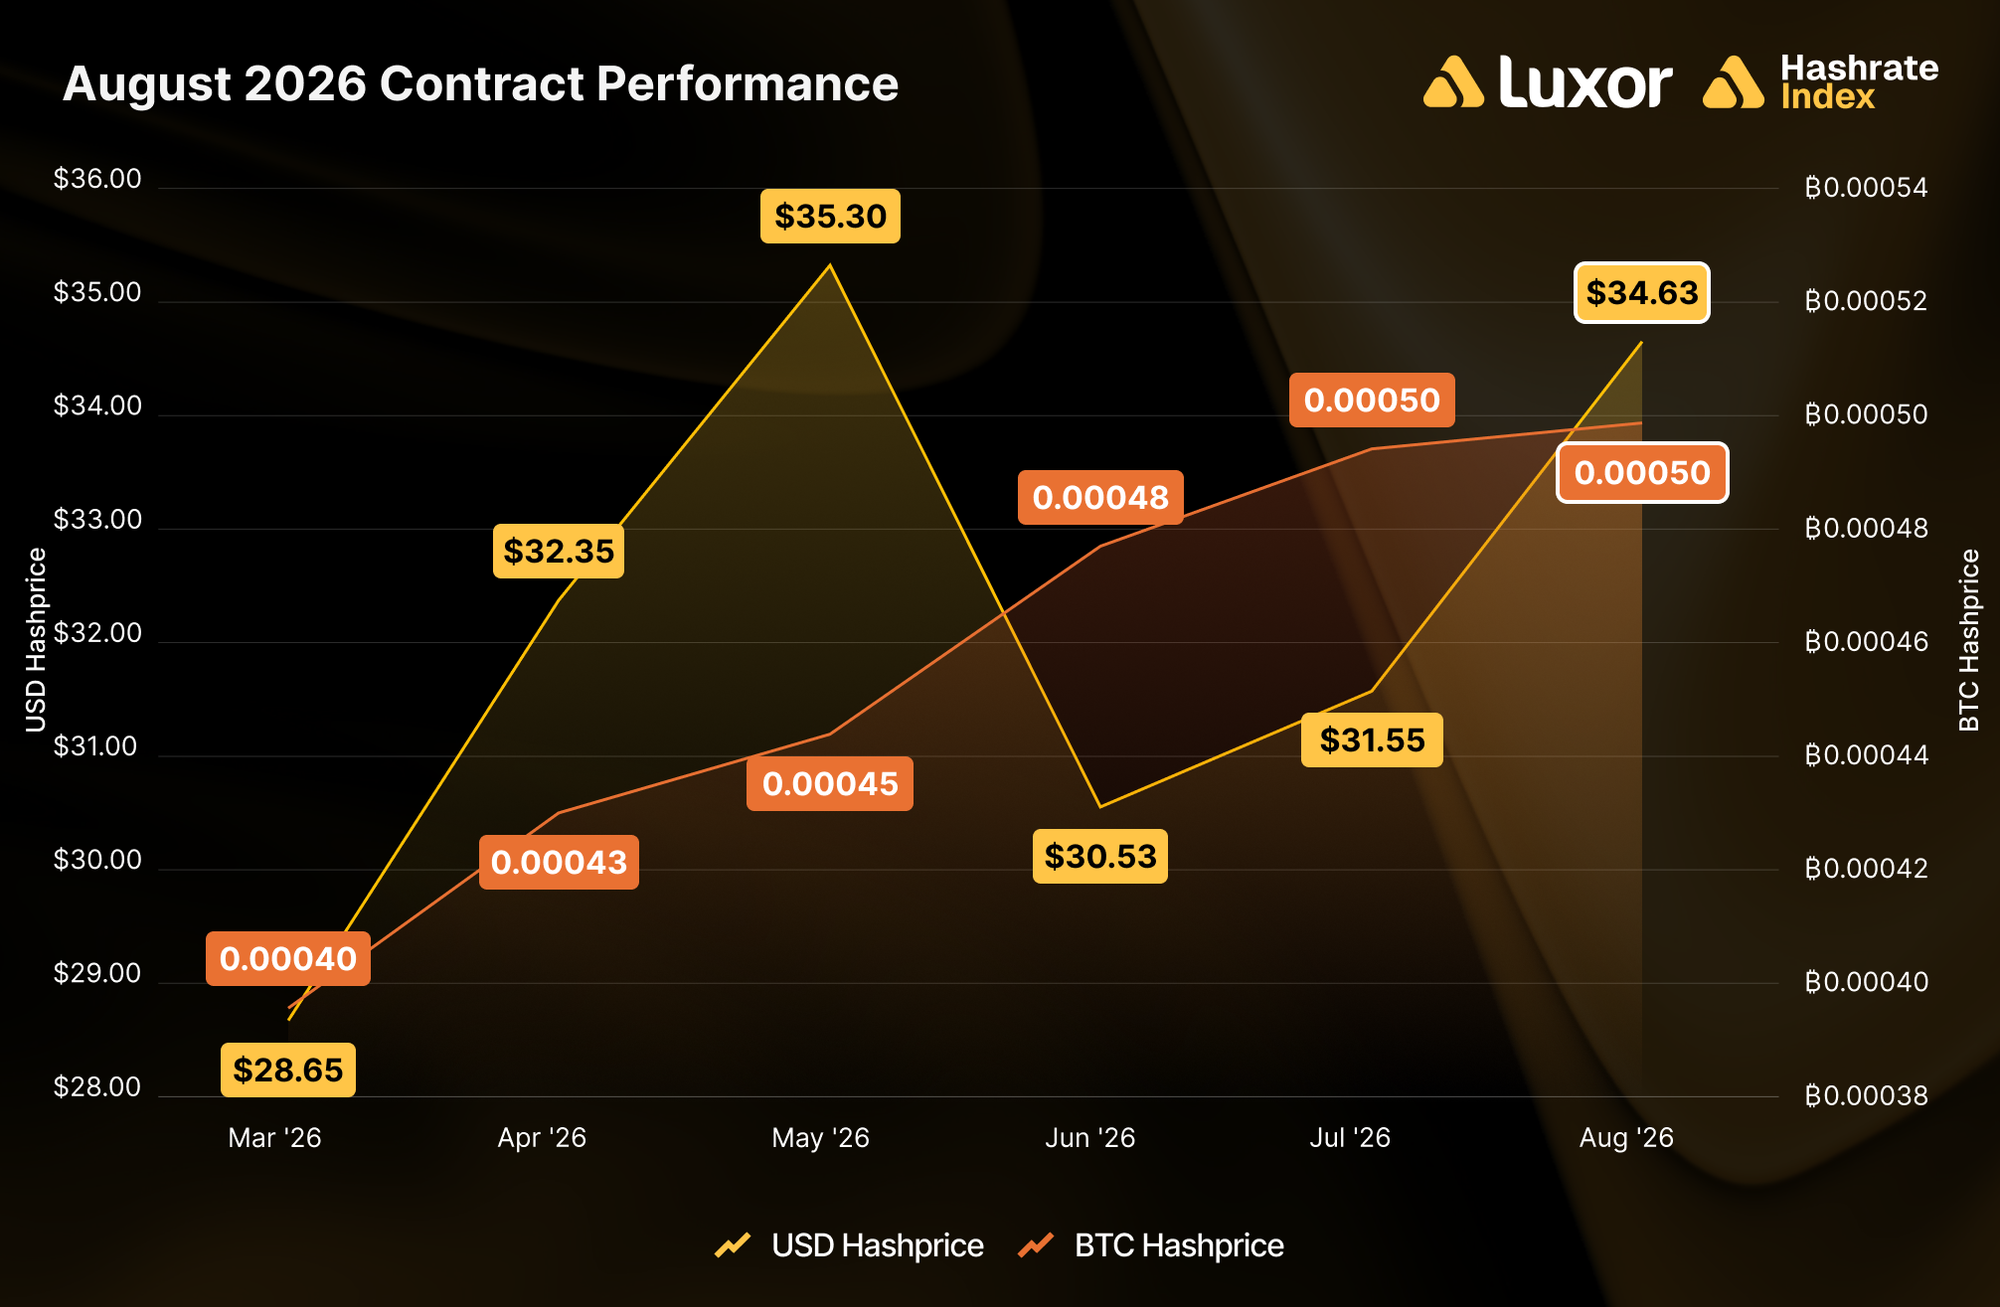
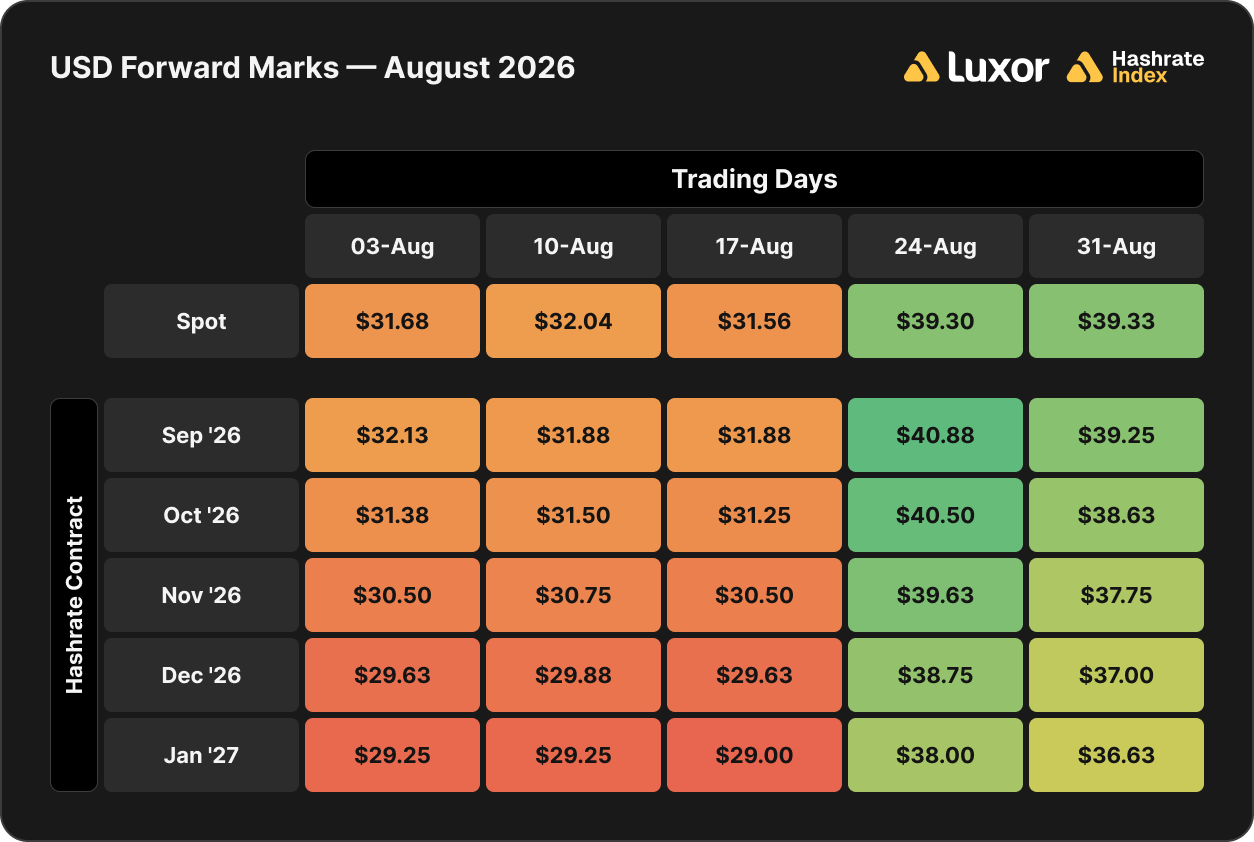
Sellers of the August USD-denominated forward contract locked in rates ranging between $28.65 and $35.30 per PH/s/day, comparing against a spot settlement of $34.63. Only the three-month forward sale executed in May at $35.30 outperformed spot, realizing a 1.9% gain, or roughly $20,819 per petahash per second. Every other historical hedge struck during periods of lower spot prices missed the subsequent August rally.
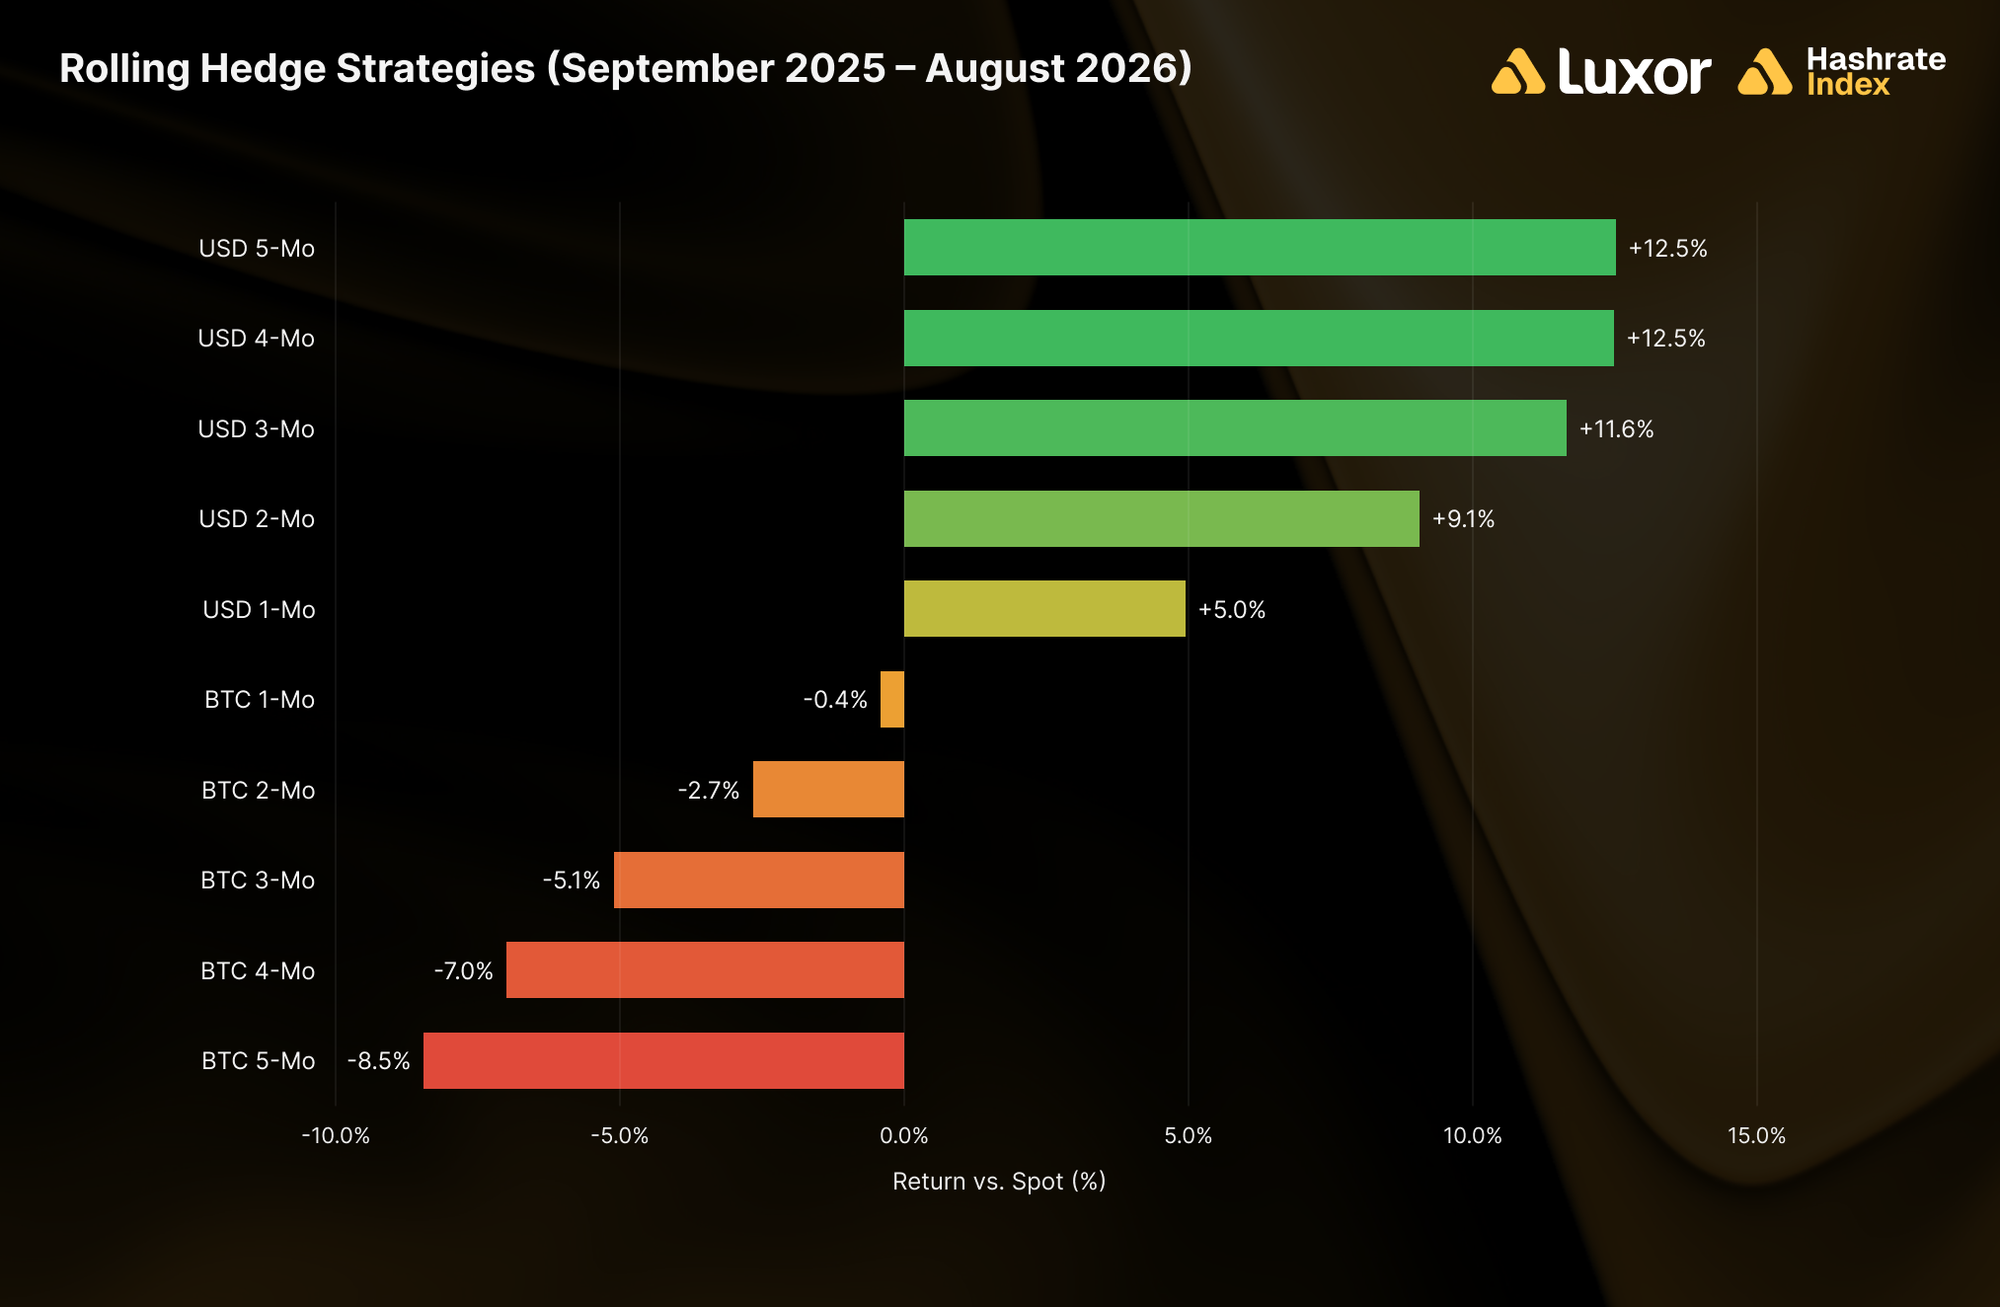
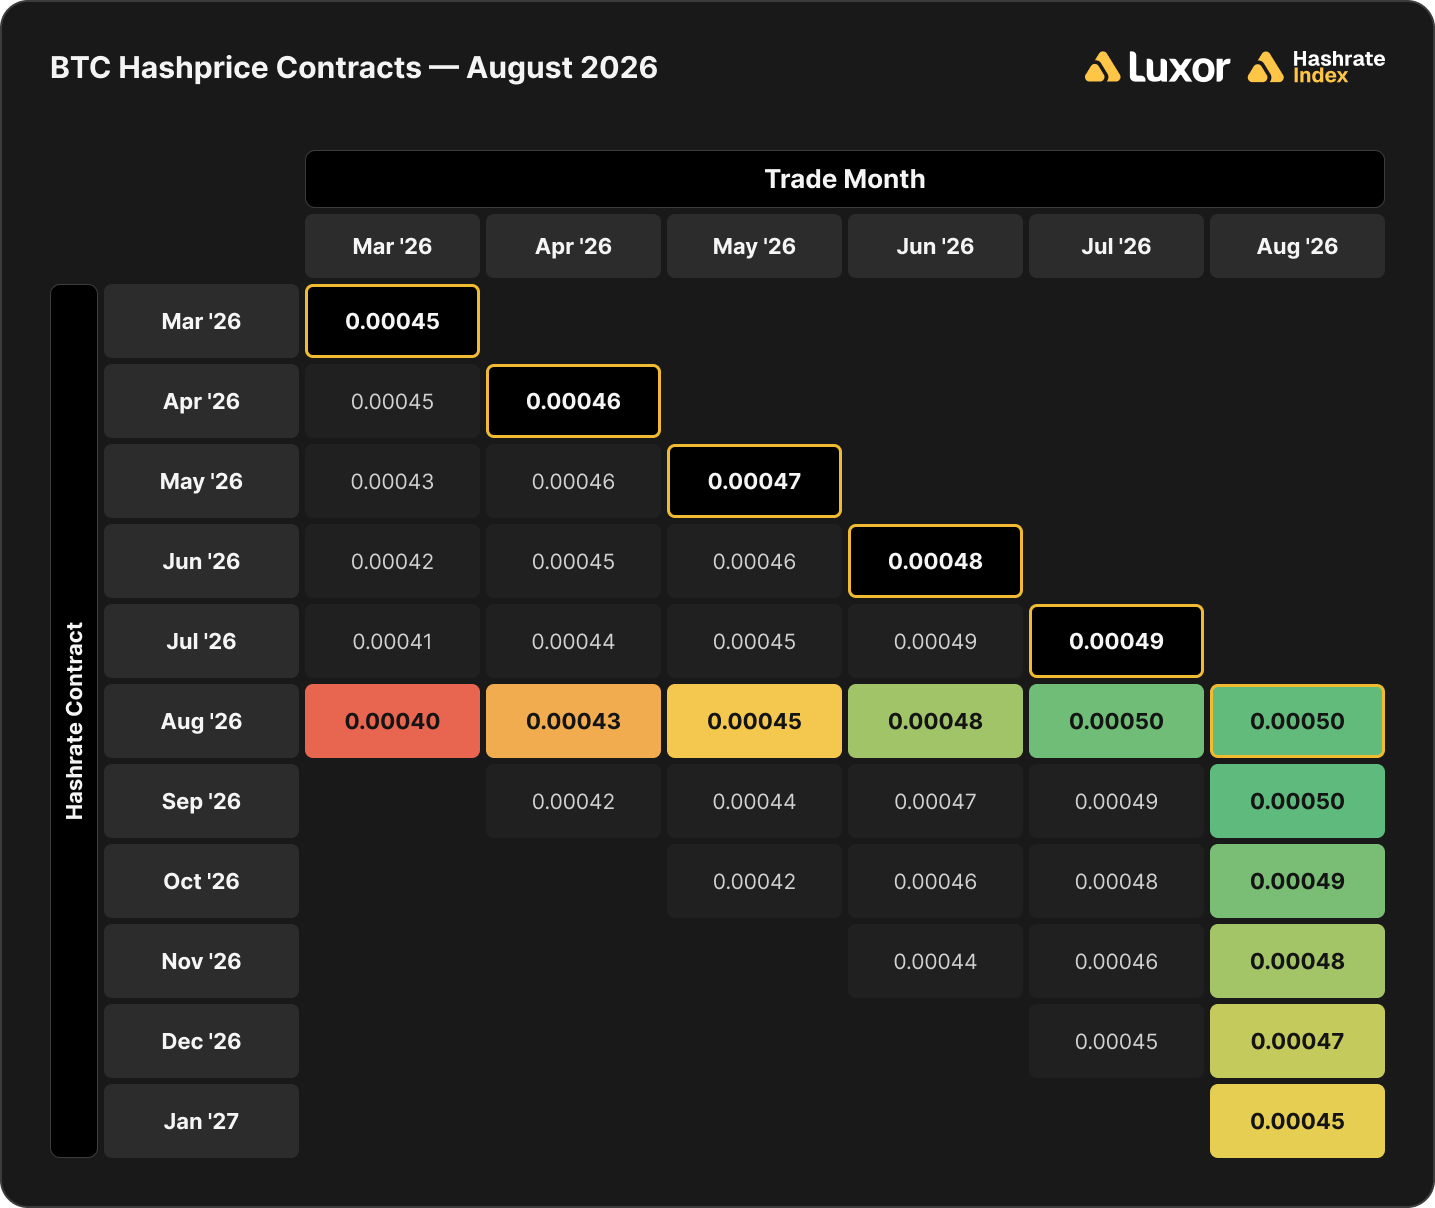
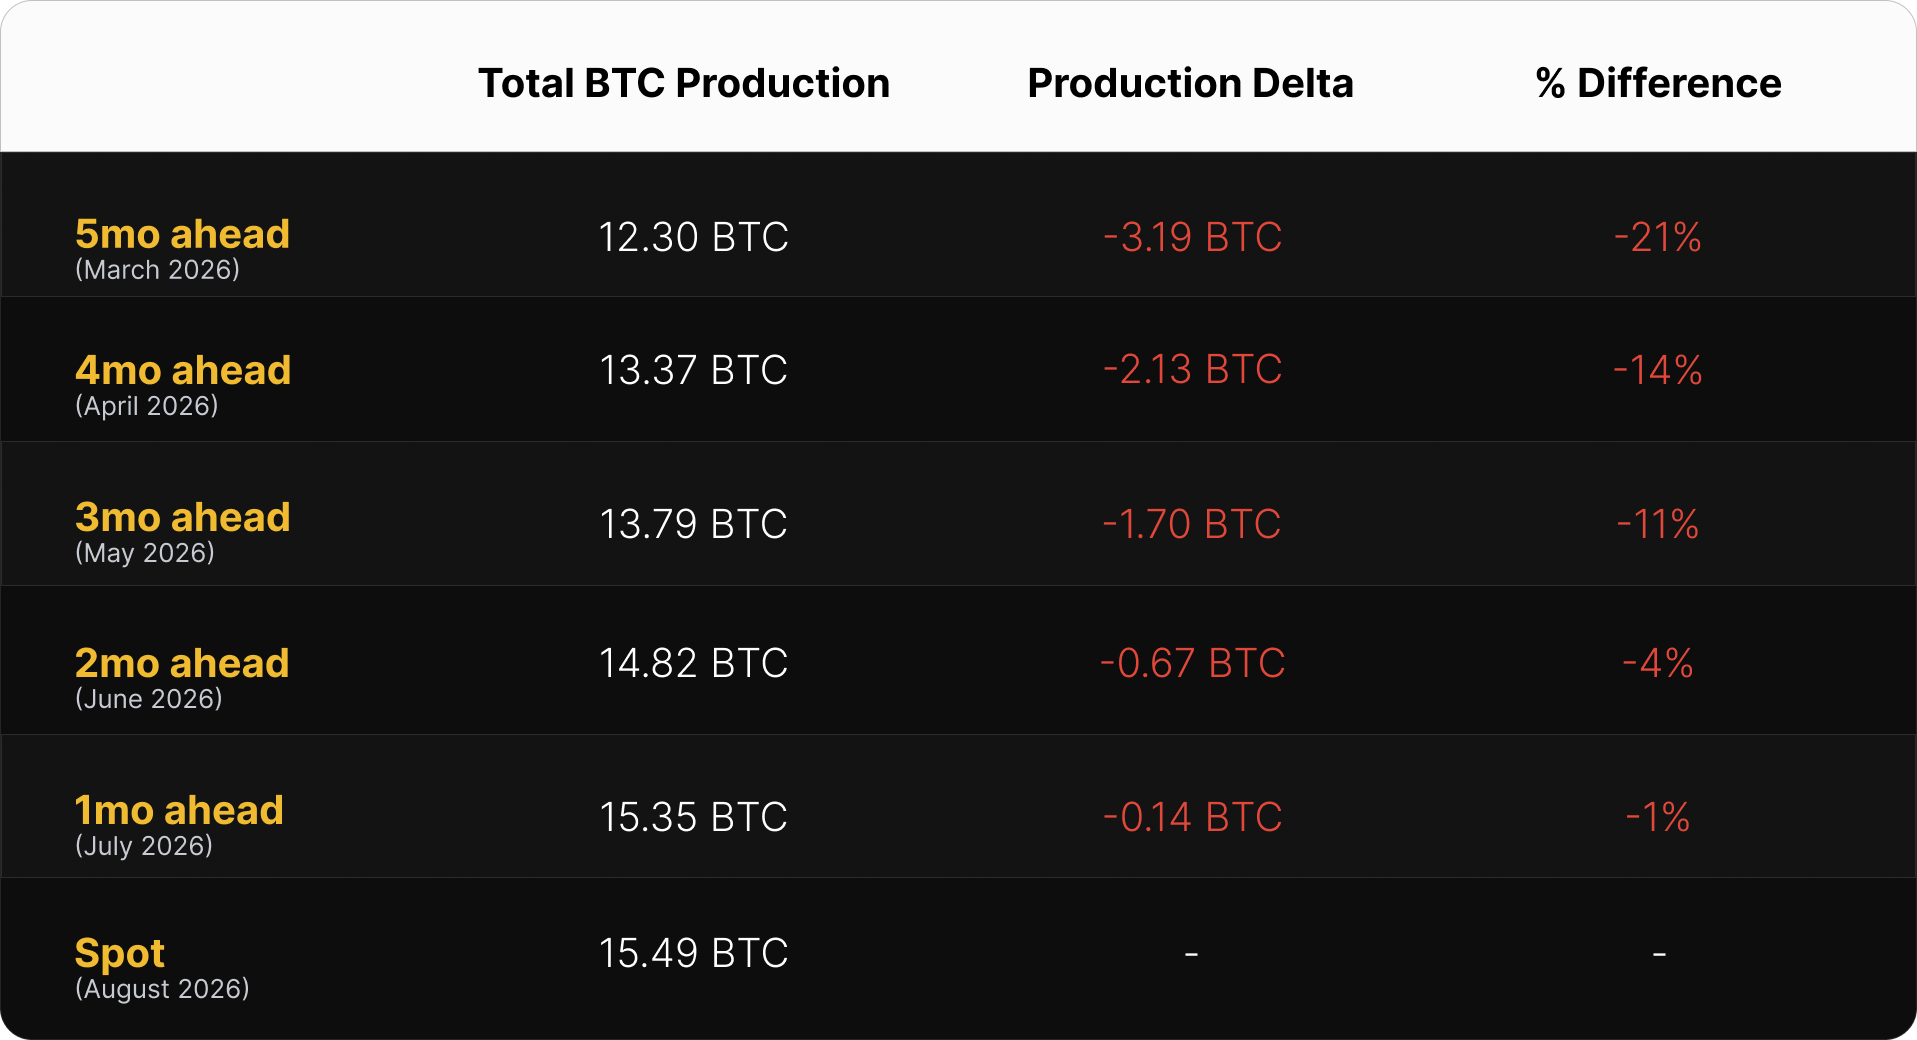
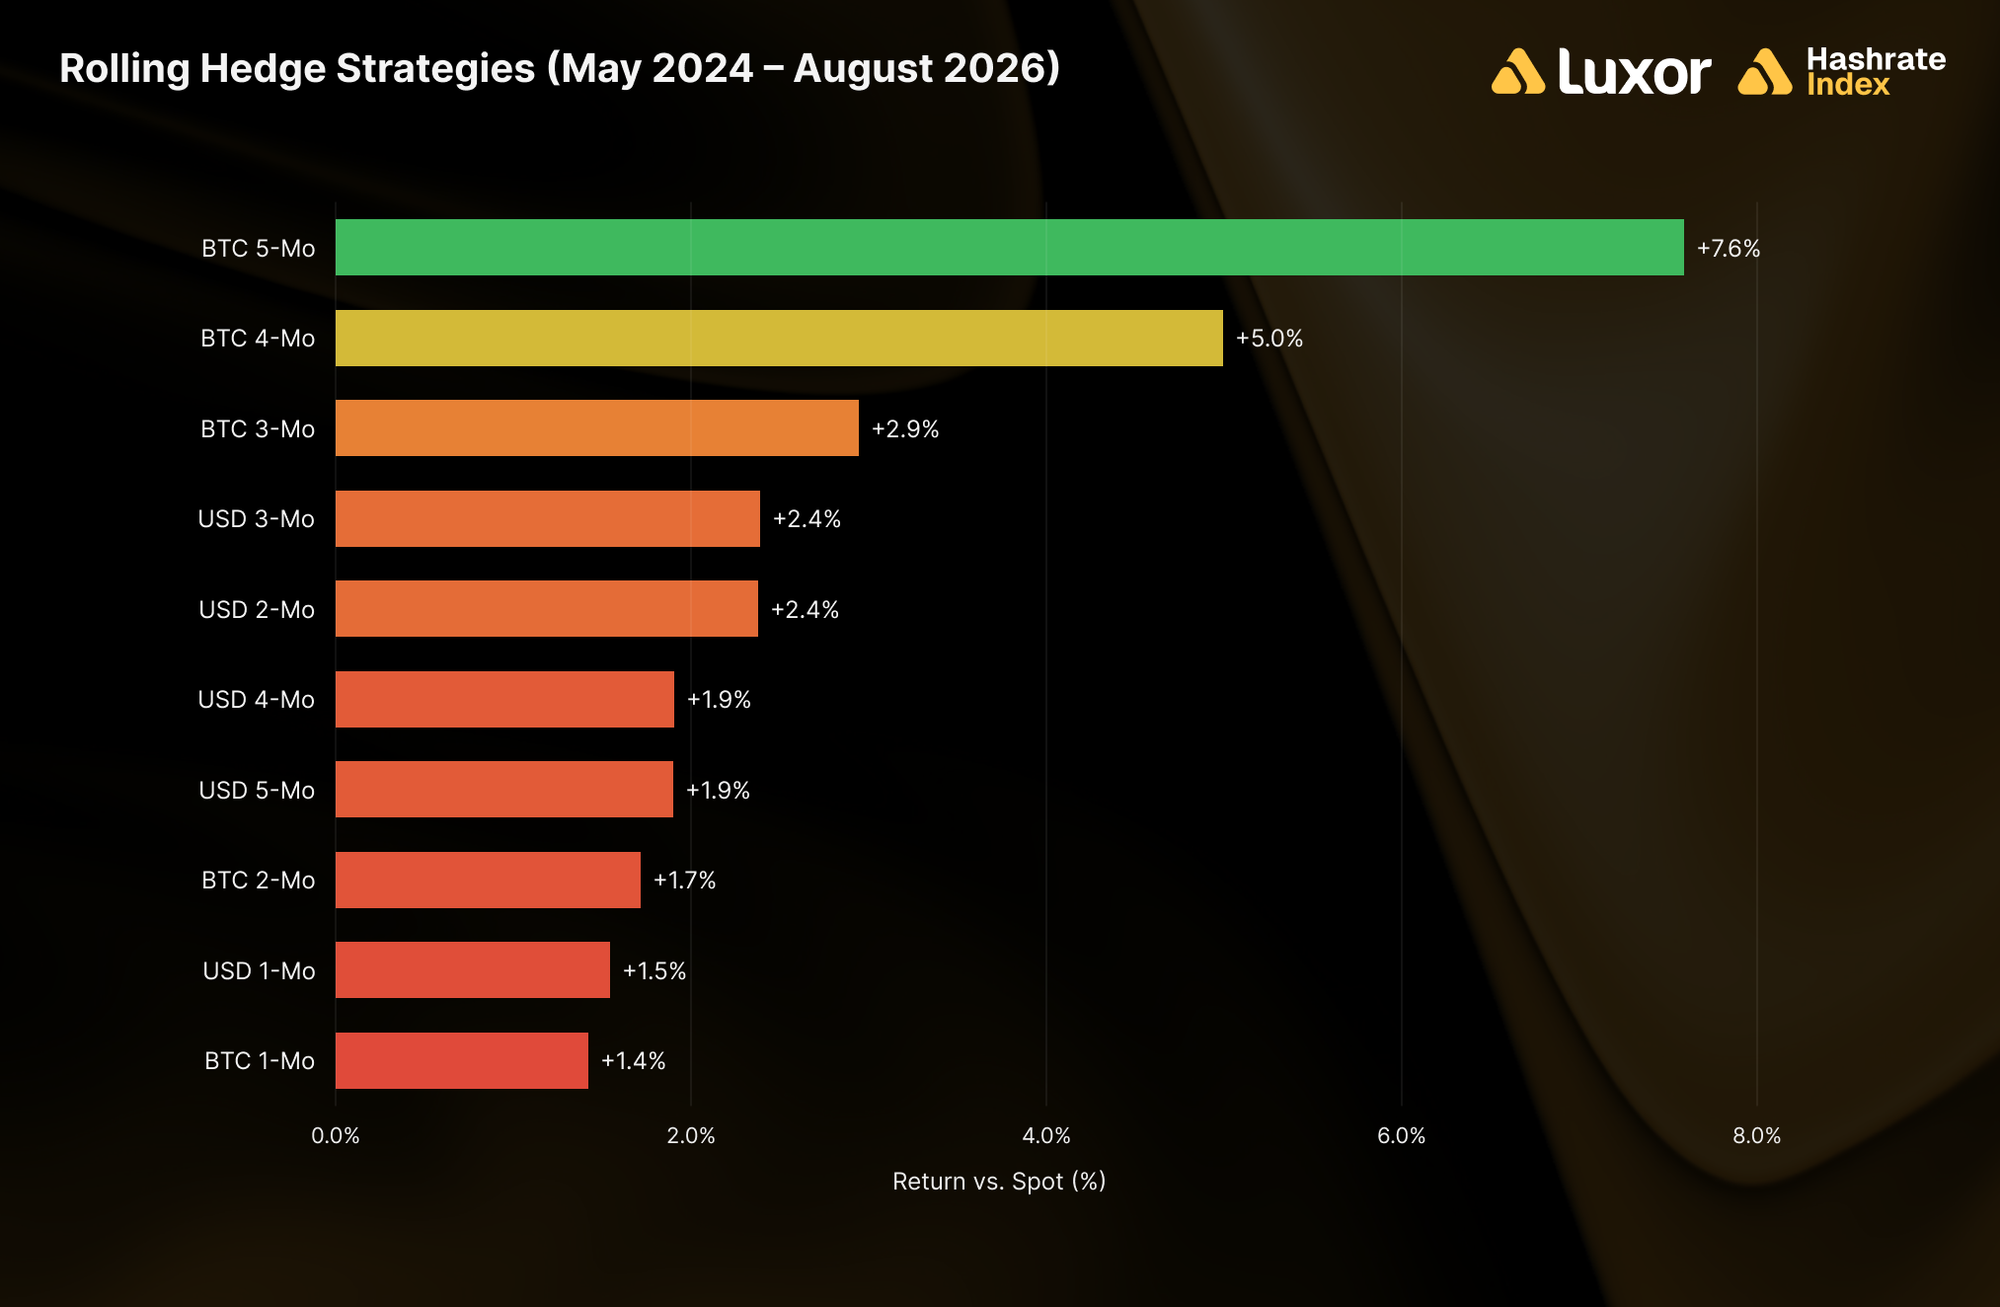
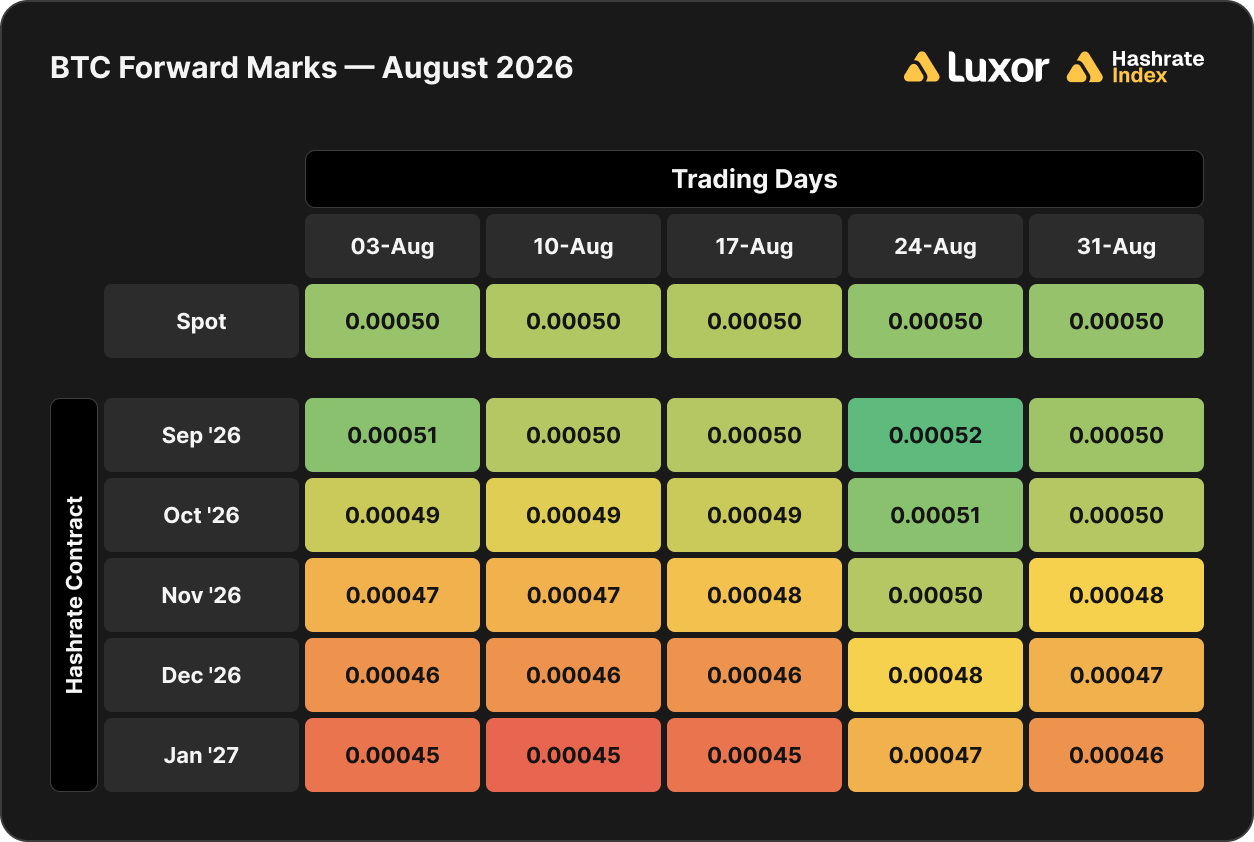
Conversely, buyers of BTC-denominated forwards outperformed spot across every time horizon for the fifth consecutive month. Sellers received between 0.00039676 and 0.00049523 BTC per PH/s/day, all falling below the 0.00049980 spot settlement. Network difficulty has now remained below forward market expectations for five consecutive months. Across the trailing twelve months, rolling USD hashprice hedges outperformed spot across all horizons, posting gains ranging from 5.0% for the one-month roll to 12.5% for the five-month roll, while rolling BTC hedges underperformed spot across all durations, showing losses between 0.4% and 8.5%.
Looking across the subsequent five-month window from September 2026 through January 2027, the USD-denominated forward curve moved in tandem with spot hashprice. Lock-in rates for these future monthly contracts rose 23.8% between August 3 and August 31, closely tracking the 24.2% increase in spot hashprice. Meanwhile, the BTC forward curve remained virtually flat, moving up by an average of just 1.3%. This divergence indicates that the market repriced Bitcoin itself while leaving expectations for network difficulty and transaction fees largely unchanged.
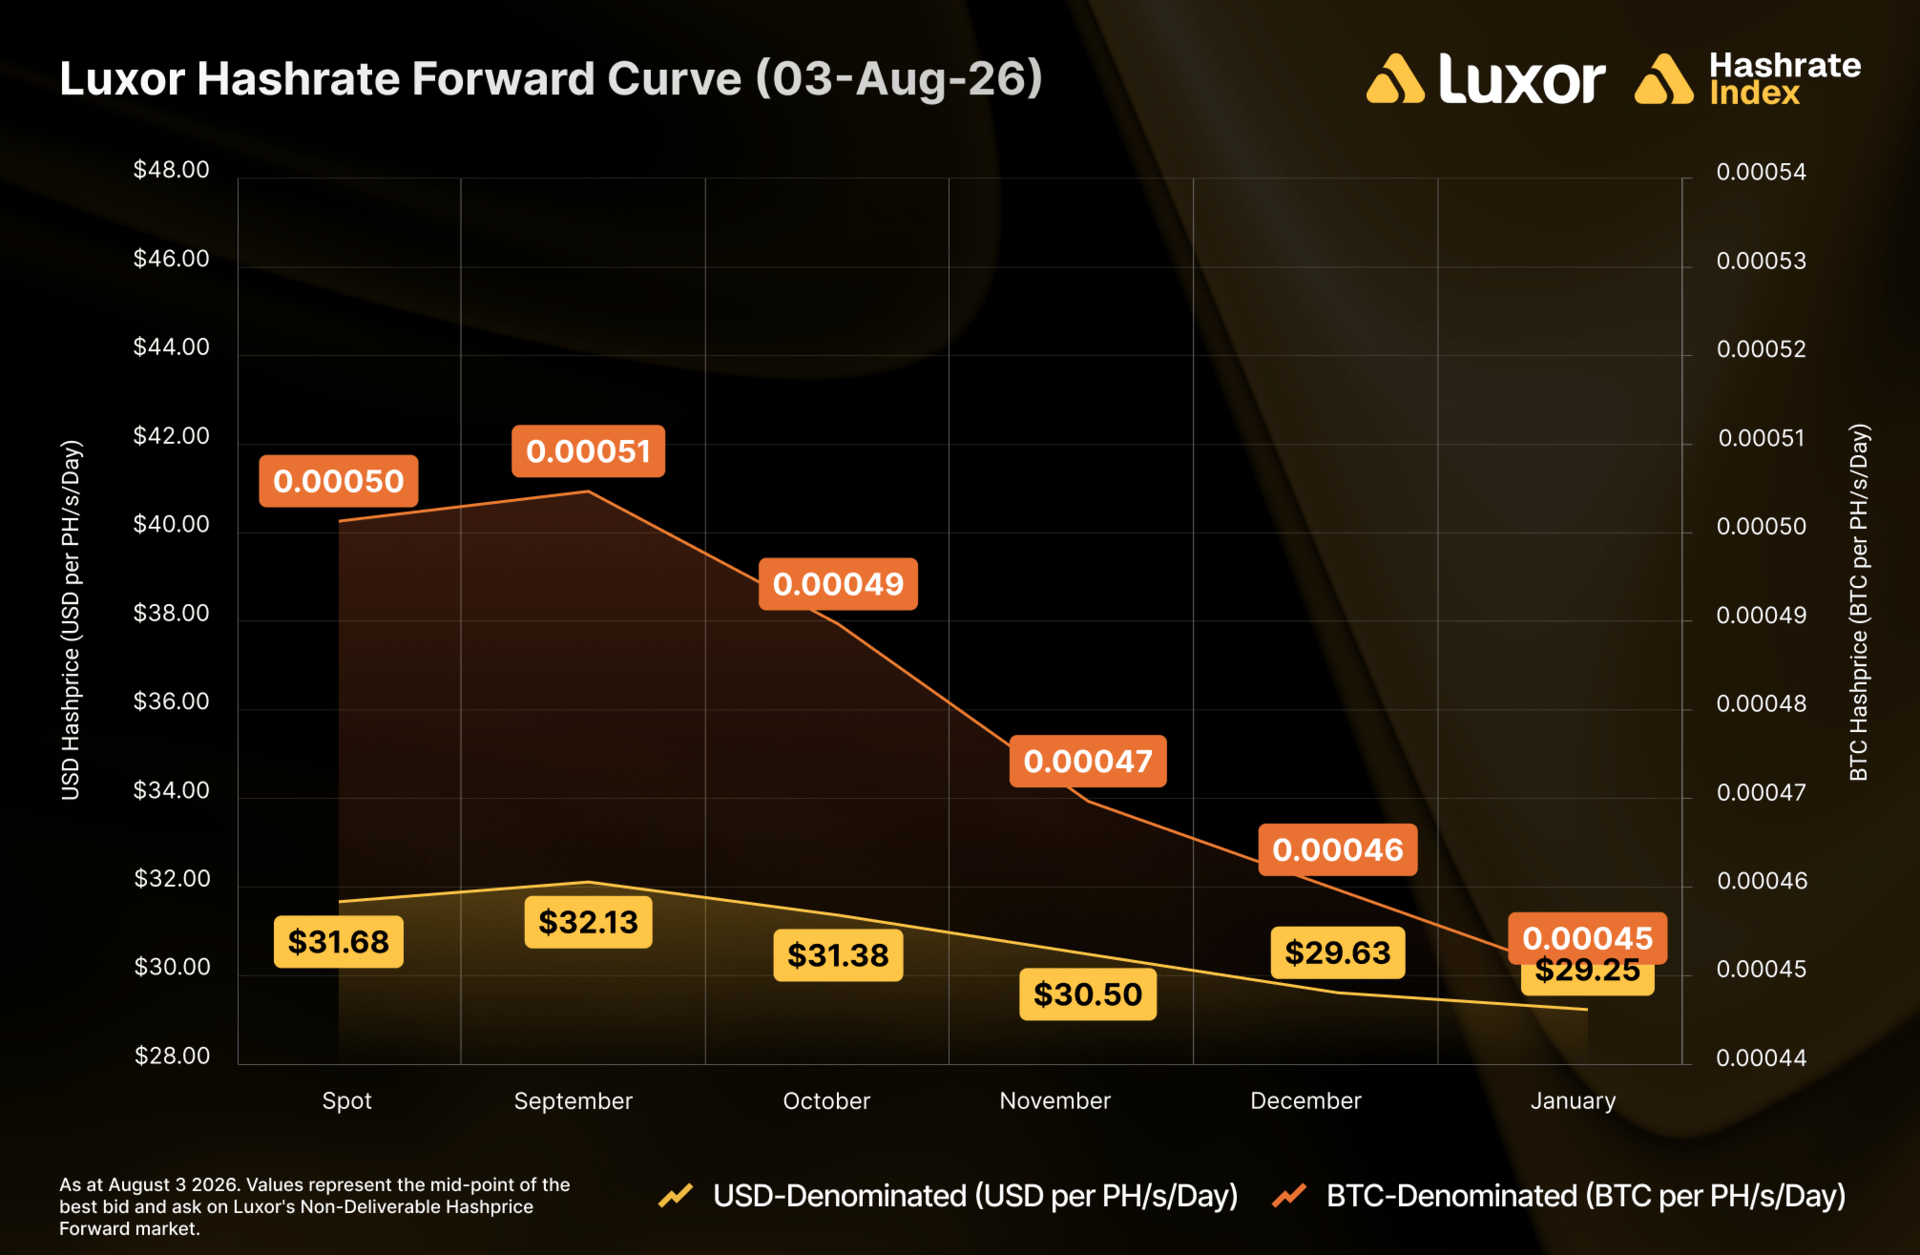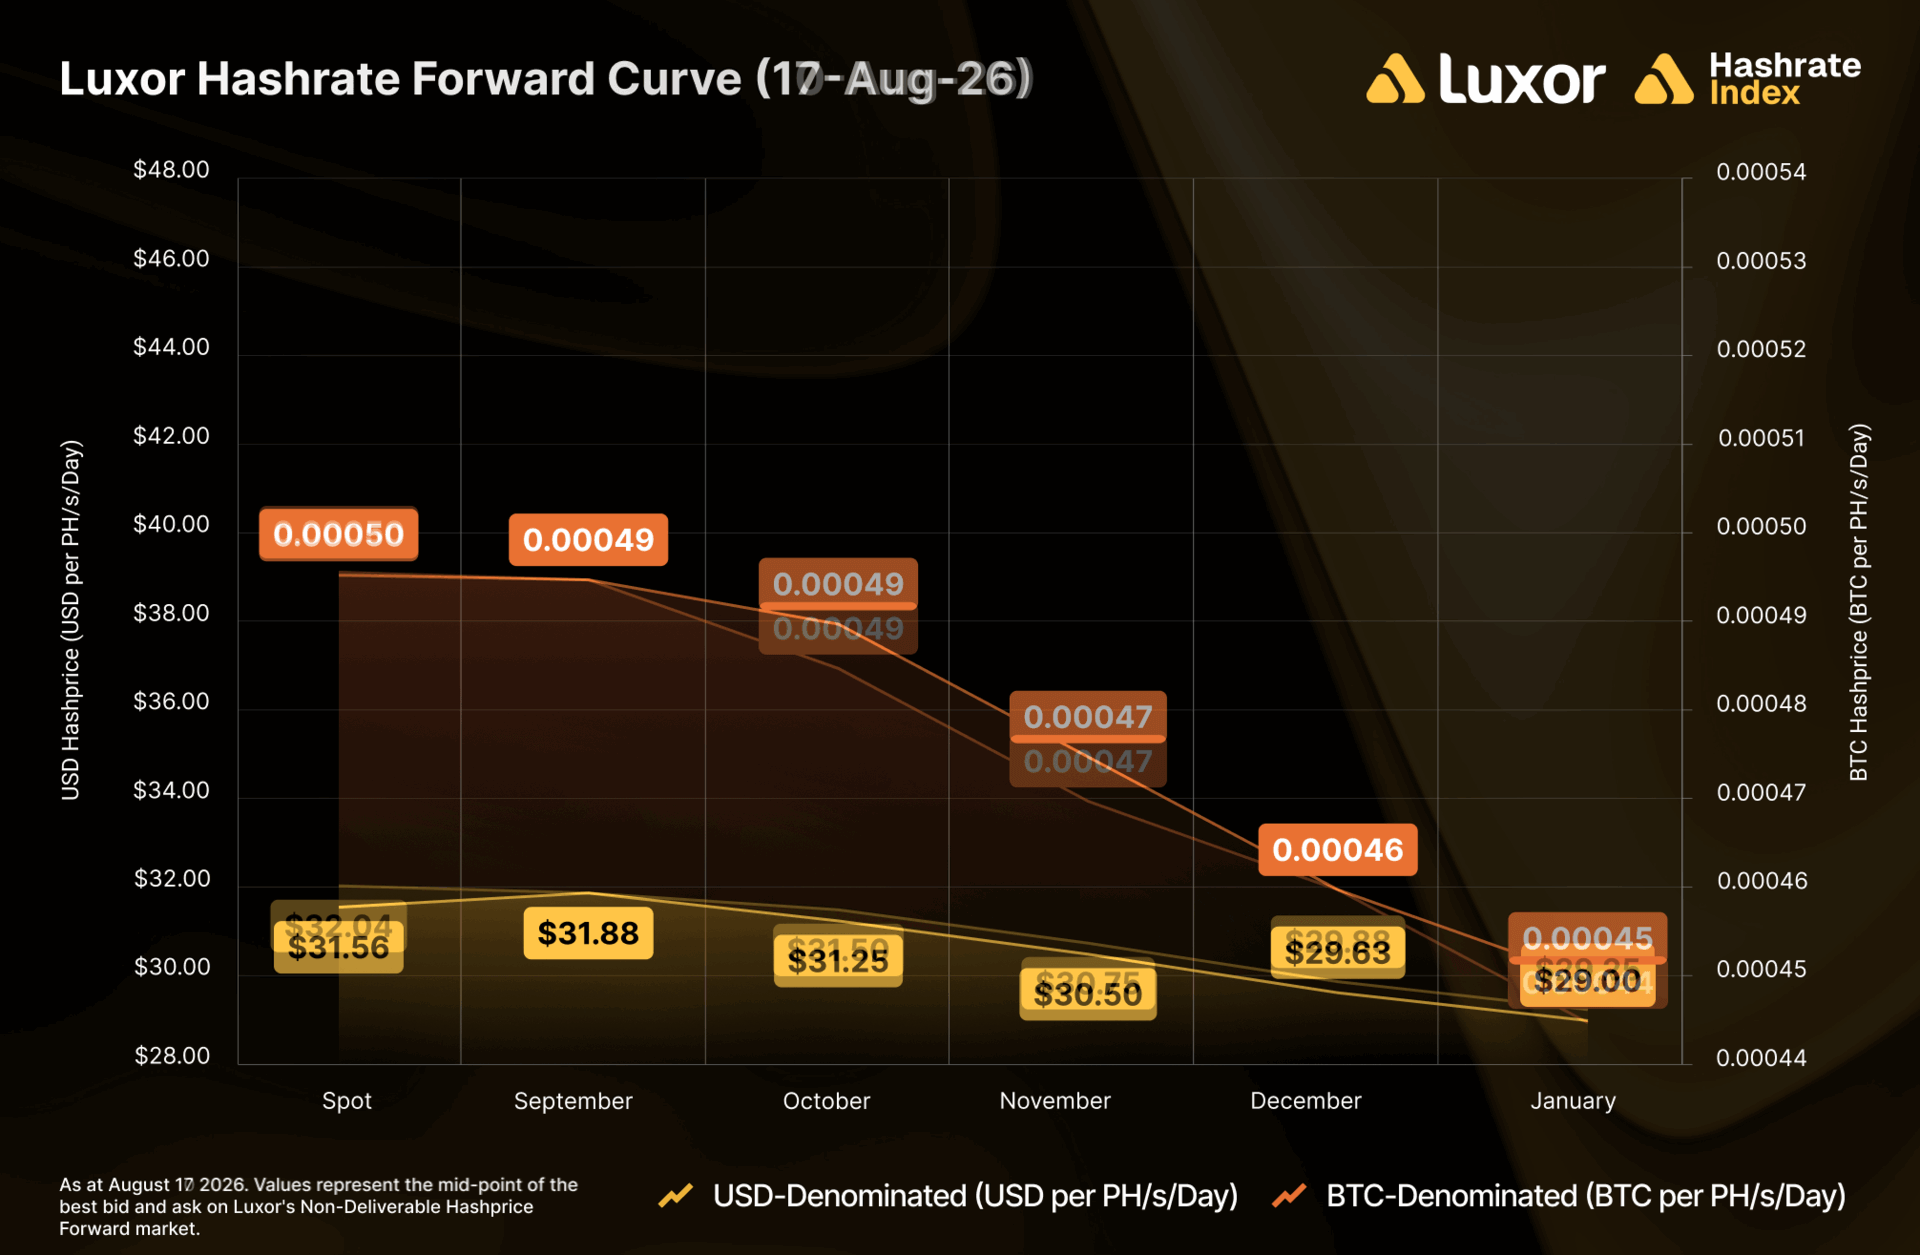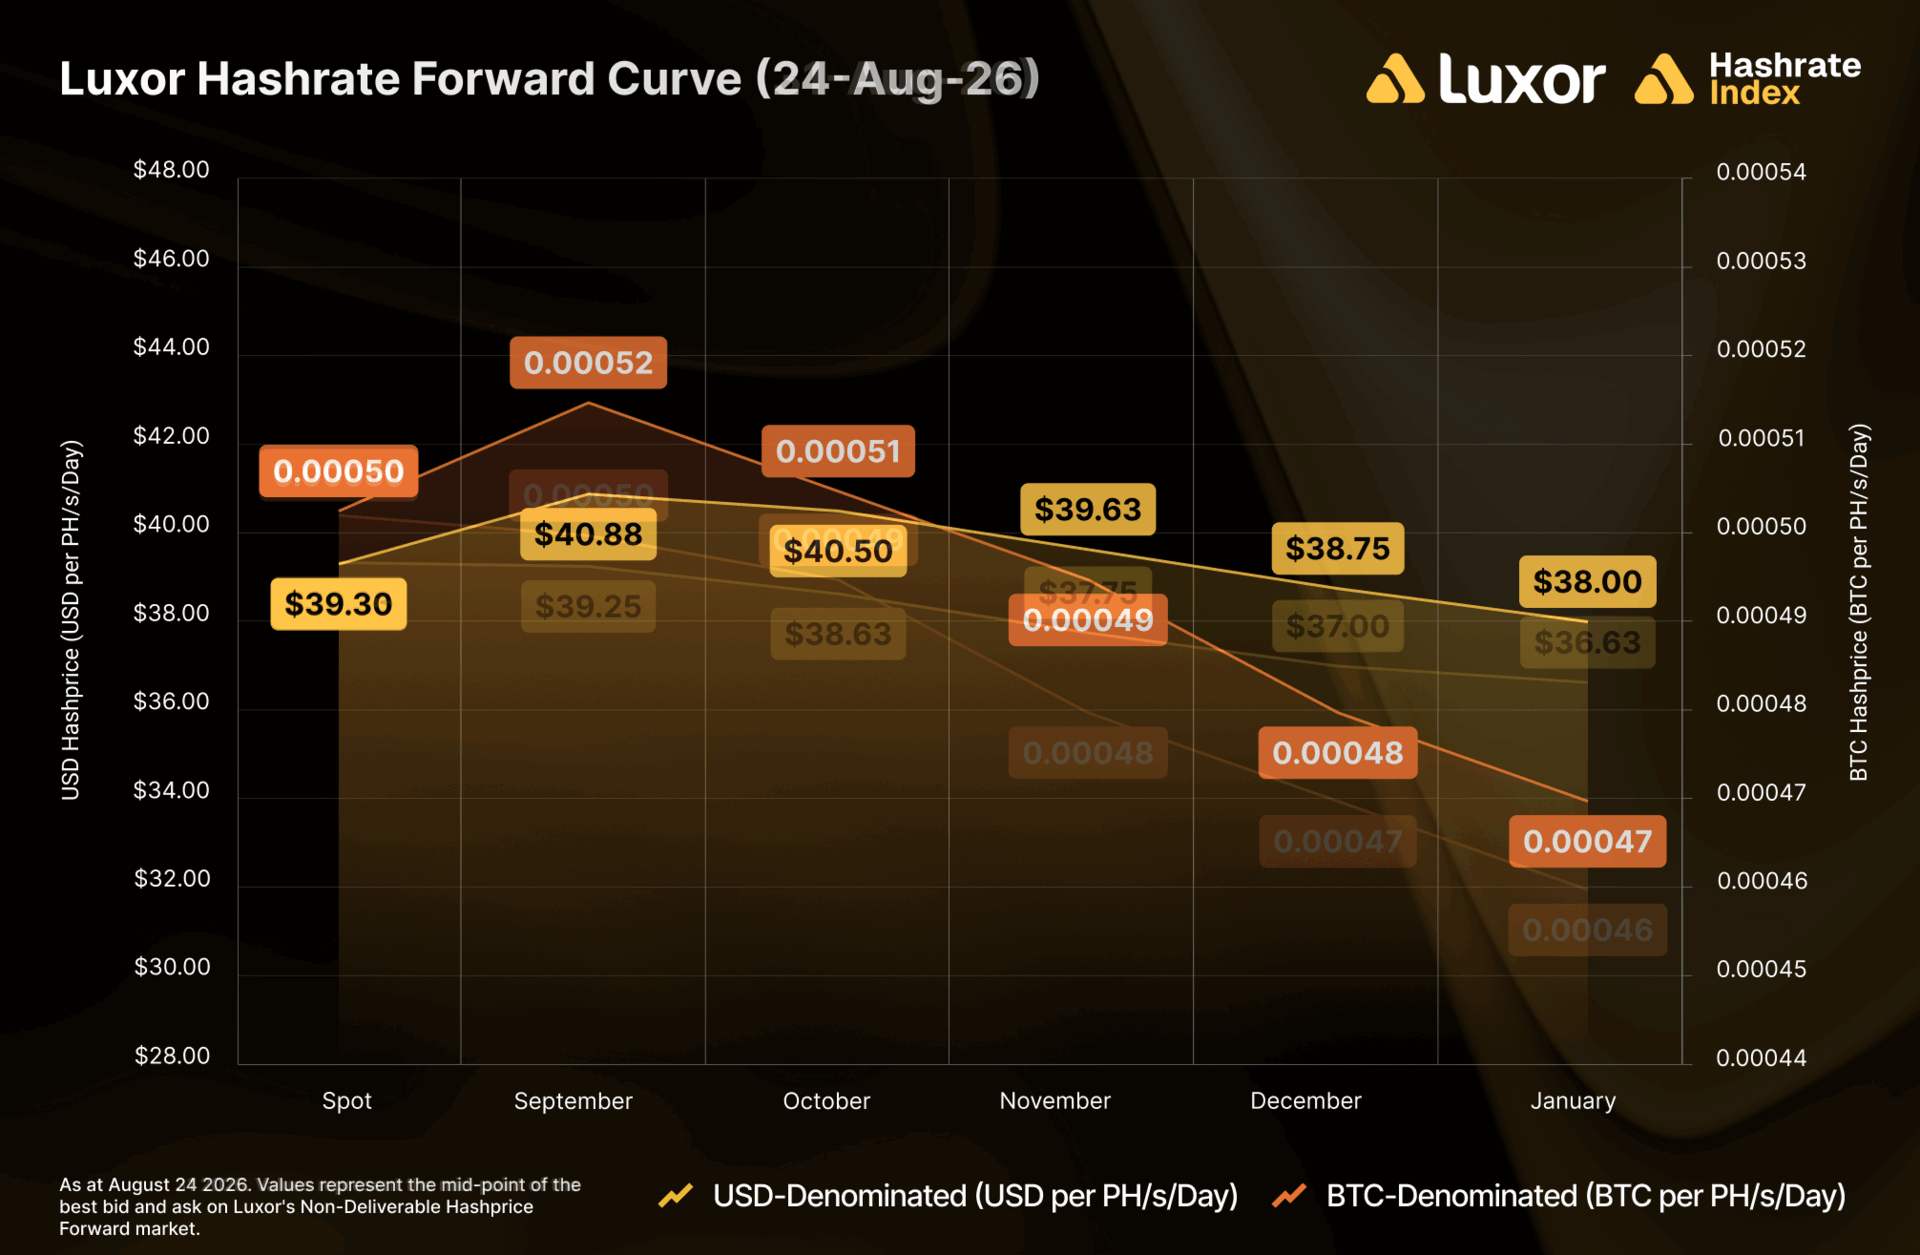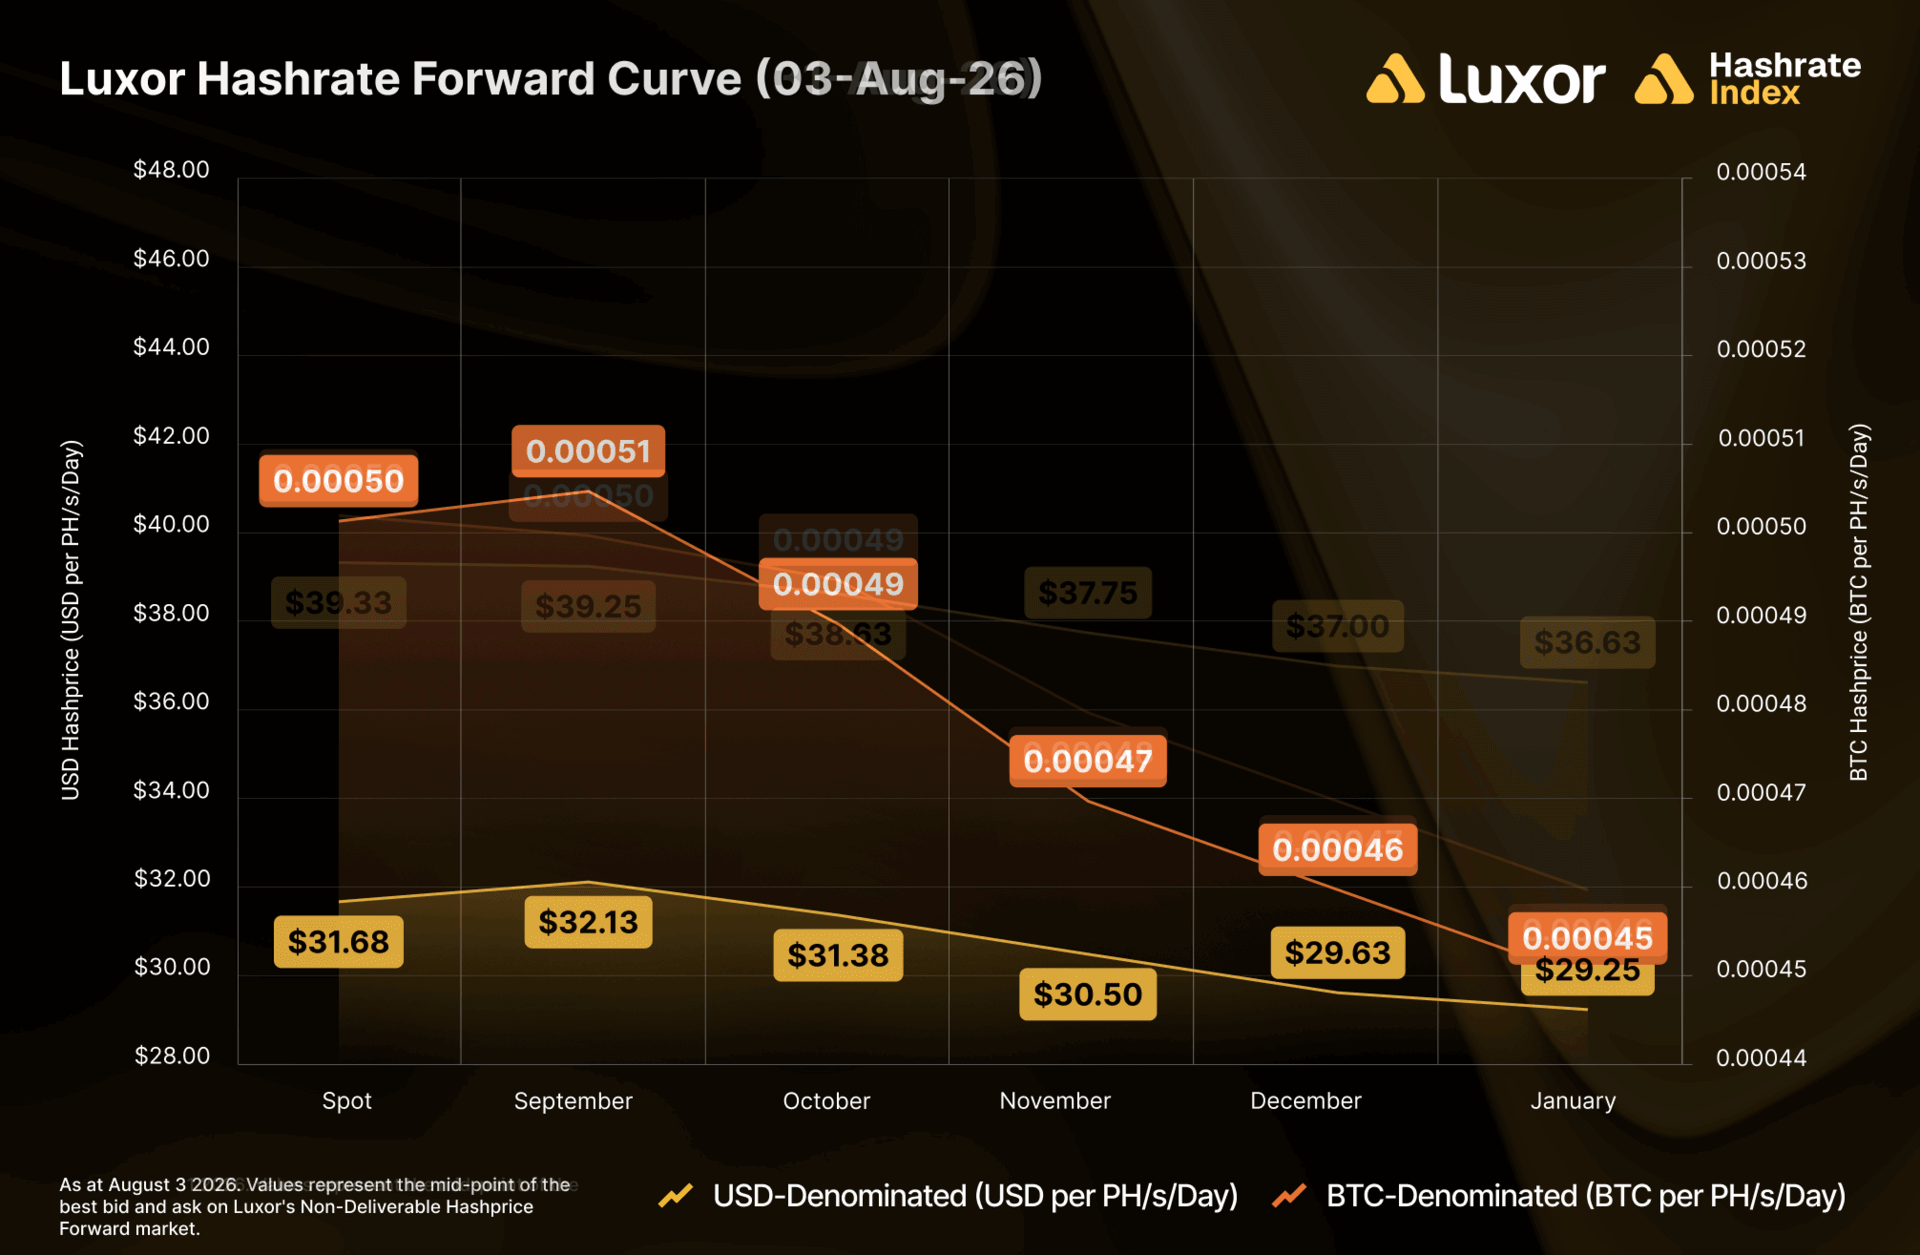
Dividing the USD contract values by their BTC counterparts reveals the implied Bitcoin price embedded within the forward hashrate market. The implied BTC price for the September contract moved from approximately $63,600 to $78,500, with the broader forward curve stabilizing between $78,000 and $79,600 across the five-month horizon. Assuming August’s realized transaction fee average of 0.0222 BTC per block, these contracts imply forward-looking expectations for difficulty to average 126.62T in September—consistent with a network running faster than target—while shaving expectations for October through January by 1.0% to 2.2%. This adjustment lowered implied December hashrate from 985 EH/s to 964 EH/s and January 2027 from 1,007 EH/s to 985 EH/s, marking the third consecutive month that the curve has trimmed its autumn recovery expectations from a high of 1,054 EH/s in June.
Concluding Outlook
September opened on a stable footing, maintaining momentum above August’s close. Through the first week of the month, spot hashprice averaged $39.60 while Bitcoin hovered near $79,000. Industry projections place average power costs at $0.048 per kilowatt-hour, placing the fleet breakeven efficiency threshold near 30 joules per terahash at August’s average hashprice of $34.63, and shifting it to approximately 35 joules per terahash at a $40 hashprice level.
Key policy milestones loom on the horizon for September, including a scheduled Senate vote on the Clarity Act and an upcoming Federal Open Market Committee rate decision. Meanwhile, the return of offline or curtailed hashrate—estimated at roughly 235 EH/s of idle capacity against total net ASIC capacity of approximately 1,150 EH/s—presents a balancing force. As summer curtailment programs wrap up, particularly in Texas following the final ERCOT coincident peak, the historical seasonal pattern points toward potential difficulty increases through October, setting up a dynamic where either Bitcoin price appreciation continues to outpace network expansion or rising difficulty absorbs the recent gains in hashprice.
 Cryptocurrency Mining
 Cryptocurrency Mining
 Cryptocurrency Mining