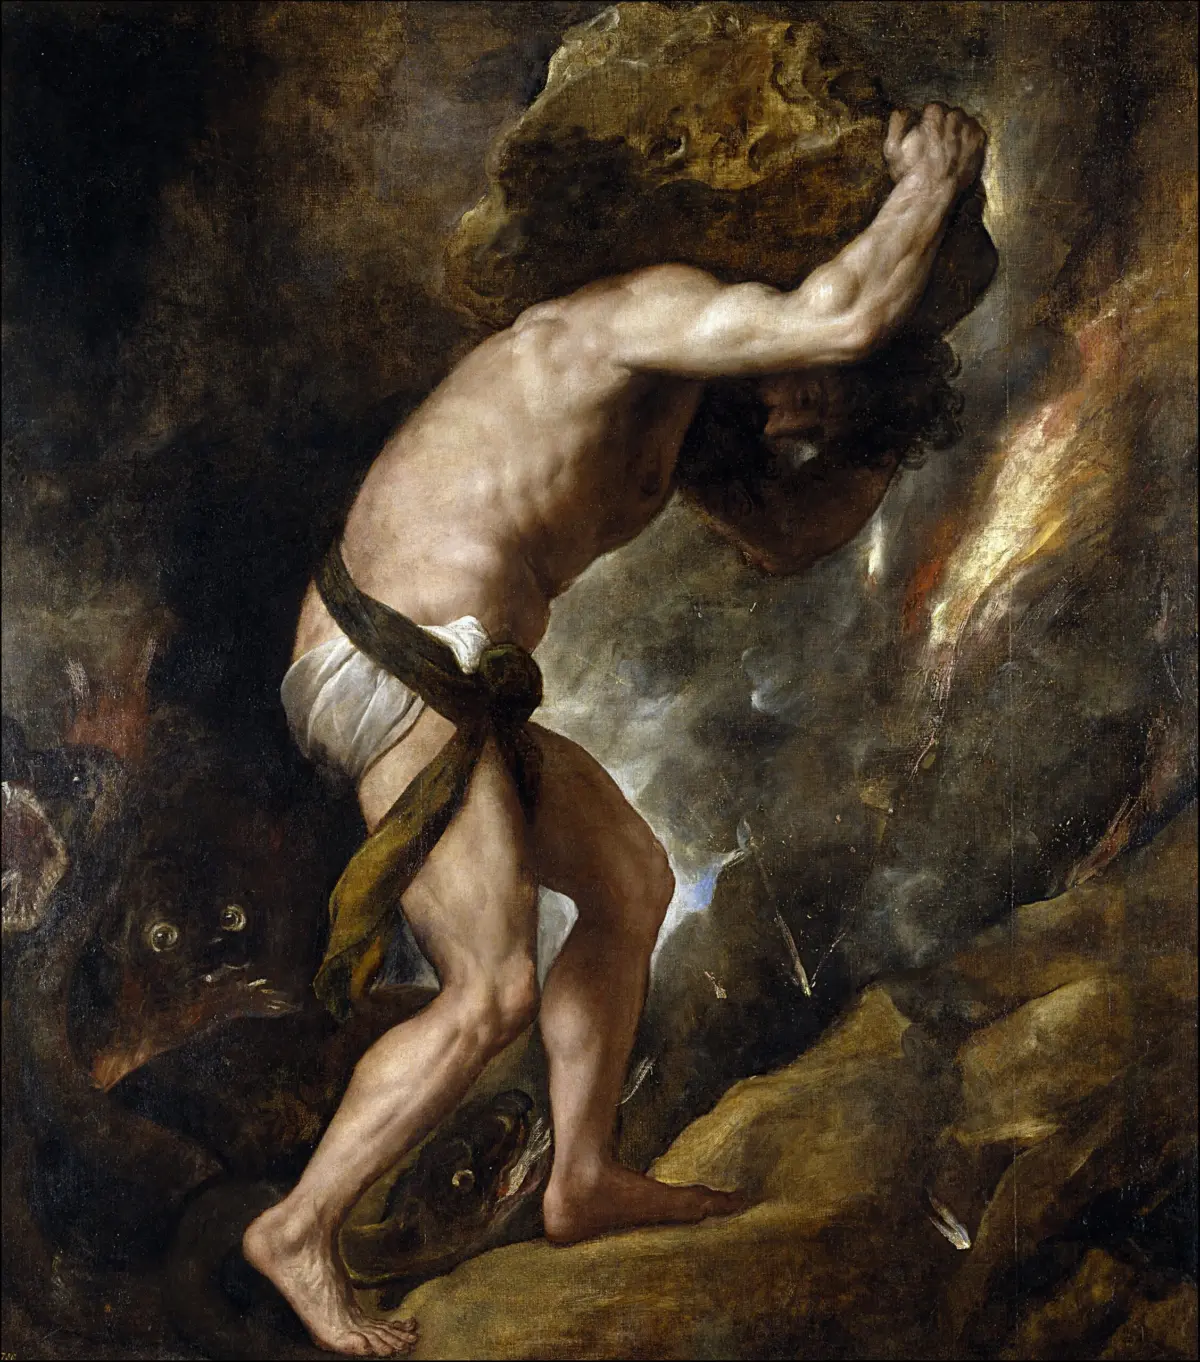
Washington — For years, the pursuit of regulatory clarity for the digital asset industry has drawn grim comparisons to the mythological fate of Sisyphus. Condemned by the gods to push a massive boulder up a steep hill, only to watch it roll back down to the bottom for eternity, crypto advocates and lawmakers have repeatedly found themselves trapped in a seemingly endless cycle of legislative effort followed by total collapse. The latest attempt to bring order to the burgeoning digital economy—weighing in at a sprawling 635 pages—has officially tumbled back down the mountain.
The United States Senate recently failed to advance the Digital Asset Market Clarity Act, widely known simply as the Clarity Act. With the midterm elections looming just around the corner, policy experts note that there is no longer any realistic legislative path to revive the bill before the end of the year.
As its name suggests, the Clarity Act was designed to establish a comprehensive market structure rulebook for the United States. Its primary objective was to sort digital tokens into appropriate legal categories, establish robust licensing frameworks for the firms trading them, and clearly divide supervisory authority between the nation’s top financial regulators: the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC).
According to Ryan Chan-Wei, a research fellow at the Cato Institute’s Center for Monetary and Financial Alternatives, enacting such a framework would have unlocked the considerable potential of cryptocurrency, including its capacity to significantly expand financial inclusion and drastically reduce the costs associated with cross-border payments. However, realizing those benefits at a national scale requires far more than technical ingenuity. Regulated financial institutions naturally hesitate to commit substantial capital while the rules of the road remain unwritten and ambiguous, and everyday Americans have little reason to place their trust in a dynamic market that lacks unified federal oversight.
Congress has long understood the pressing need for a comprehensive regulatory framework to govern digital assets. Legislative attempts to solve the regulatory puzzle date back nearly a decade, beginning with the Token Taxonomy Act introduced in the House of Representatives during the 115th Congress in 2018. Over the span of four successive congressional sessions, various legislative attempts have been introduced, debated, and ultimately allowed to falter, though none had ever managed to come as close to the finish line as the Clarity Act did this year.
Despite the broad momentum that carried the bill through months of intense negotiations, the political landscape is about to undergo a dramatic shift. Progress on the issue will effectively reset to square one when the new Congress is sworn in, largely because several key senators who quarterbacked the legislation will not be returning to Capitol Hill. Senator Cynthia Lummis of Wyoming, who serves as the chair of the Senate Banking Subcommittee on Digital Assets, is retiring at the end of her term. Similarly, Senator Thom Tillis of North Carolina, who played a pivotal role in brokering the delicate bipartisan compromise regarding stablecoin rewards that ultimately cleared the Clarity Act’s path out of committee, is also stepping down.
What makes the ultimate defeat of the legislation all the more exasperating for its supporters is that the heaviest lifting had already been accomplished. The most fundamental and contentious questions concerning market structure had largely been resolved through painstaking bipartisan compromise. This deep consensus explained the uniquely broad coalition that assembled behind the bill—an alliance that brought together traditional Wall Street heavyweights and representatives of the fast-moving crypto industry as unlikely bedfellows. Major traditional financial institutions, including financial giants like Goldman Sachs and BlackRock, had stepped forward to formally endorse the Clarity Act.
Achieving full agreement on every granular detail is an extreme rarity for legislation of this monumental scope and complexity, and a handful of loose ends inevitably remained. Yet, what ultimately tipped the scales against the bill and stalled its progress was a fierce debate over ethics, specifically concerning the perceived risk of conflicts of interest at the highest levels of government. Lawmakers and ethics watchdogs alike argued that the United States gains very little from a domestic crypto sector that remains widely perceived by the public as rife with corruption and self-dealing, making the safeguarding of public trust an absolute imperative.
Even so, critics of the obstruction argue that it was a severe strategic mistake to sacrifice the entire Clarity Act on the altar of ethics. Other traditional legislative avenues for addressing ethics concerns and potential conflicts of interest would have remained wide open even if the market structure bill had successfully been signed into law.
Underlying the entire legislative deadlock is a fundamental question of regulatory fairness. Nearly every other sector of American finance operates securely within a clearly defined regulatory perimeter, where established firms know precisely which federal rules bind them and which specific regulatory agency enforces compliance. Crypto, by contrast, has never had such a perimeter written into federal law.
Meanwhile, many other major developed economies around the world have already established definitive frameworks. Jurisdictions ranging from the European Union and the United Kingdom to international financial hubs like Japan and Singapore have successfully implemented comprehensive regulatory regimes for digital assets. While international precedent does not inherently dictate American domestic policy, financial analysts note that it remains deeply instructive that so many competing global economies have already settled these complex regulatory questions.
As the legislative clock runs out on the current session, policy experts emphasize that the next Congress will be forced to finish what its predecessors ultimately failed to accomplish. For nearly ten years, the heavy boulder of crypto regulation has been painfully pushed up Capitol Hill, only to tumble back down again before reaching the summit. Sisyphus, at least, had earned his legendary fate through a lifetime of trickery against the gods and repeated evasions of death. Whatever faults the digital asset industry may possess, its advocates argue it hardly warrants a legislative sentence quite like his.
 Global Crypto Markets
 Global Crypto Markets
 Global Crypto Markets