
After two consecutive quarters of contraction, the Bitcoin network’s global hashrate has finally halted its descent. According to the Q4 2026 update of the Hashrate Index Global Hashrate Heatmap, the network’s total compute power finished the third quarter at approximately 941 exahashes per second (EH/s), remaining effectively flat compared to the ~940 EH/s recorded in Q2.
While a flat headline figure might suggest a period of quiet stagnation, a closer look beneath the surface reveals an unusually active quarter defined by significant geographic shifts. During this period, the United States shed another 10 EH/s while Russia added 8 EH/s. Simultaneously, Ethiopia surrendered roughly a third of its network share due to environmental pressures, whereas Pakistan more than tripled its computing output. Although the global map is no longer shrinking, the underlying compute capacity of the Bitcoin network continues to aggressively redistribute across international borders.
From Falling to Flat
The stabilization of the network’s hashrate marks a notable shift following two consecutive quarters of decline. The 30-day simple moving average registered approximately 941 EH/s against the previous quarter’s 940 EH/s, representing the first quarter in 2026 where total compute power did not register a net loss.
However, market observers emphasize that a flat quarter is not synonymous with a full market recovery. The network remains roughly 8.7 percent smaller than it was a year prior, when it stood at approximately 1,031 EH/s in Q4 2025, and sits about 15 percent below its all-time peak reached in November 2025.
The primary change driving this stabilization is a slowing of the prior structural bleed. Marginal mining machines that were economically forced to switch off under prevailing hashprice conditions have largely already been unplugged. Meanwhile, network difficulty has adjusted downward sufficiently to keep surviving operators above water.
This environment of macroeconomic equilibrium has shifted the industry’s focal point toward the country level. Five distinct nations recorded shifts of more than 4 EH/s in either direction over the quarter. In a period where the global total barely budged, this represents pure geographical redistribution, signaling that Bitcoin’s physical infrastructure is actively relocating in search of optimal economic and operational conditions.
The Evolution of Country-Level Concentration
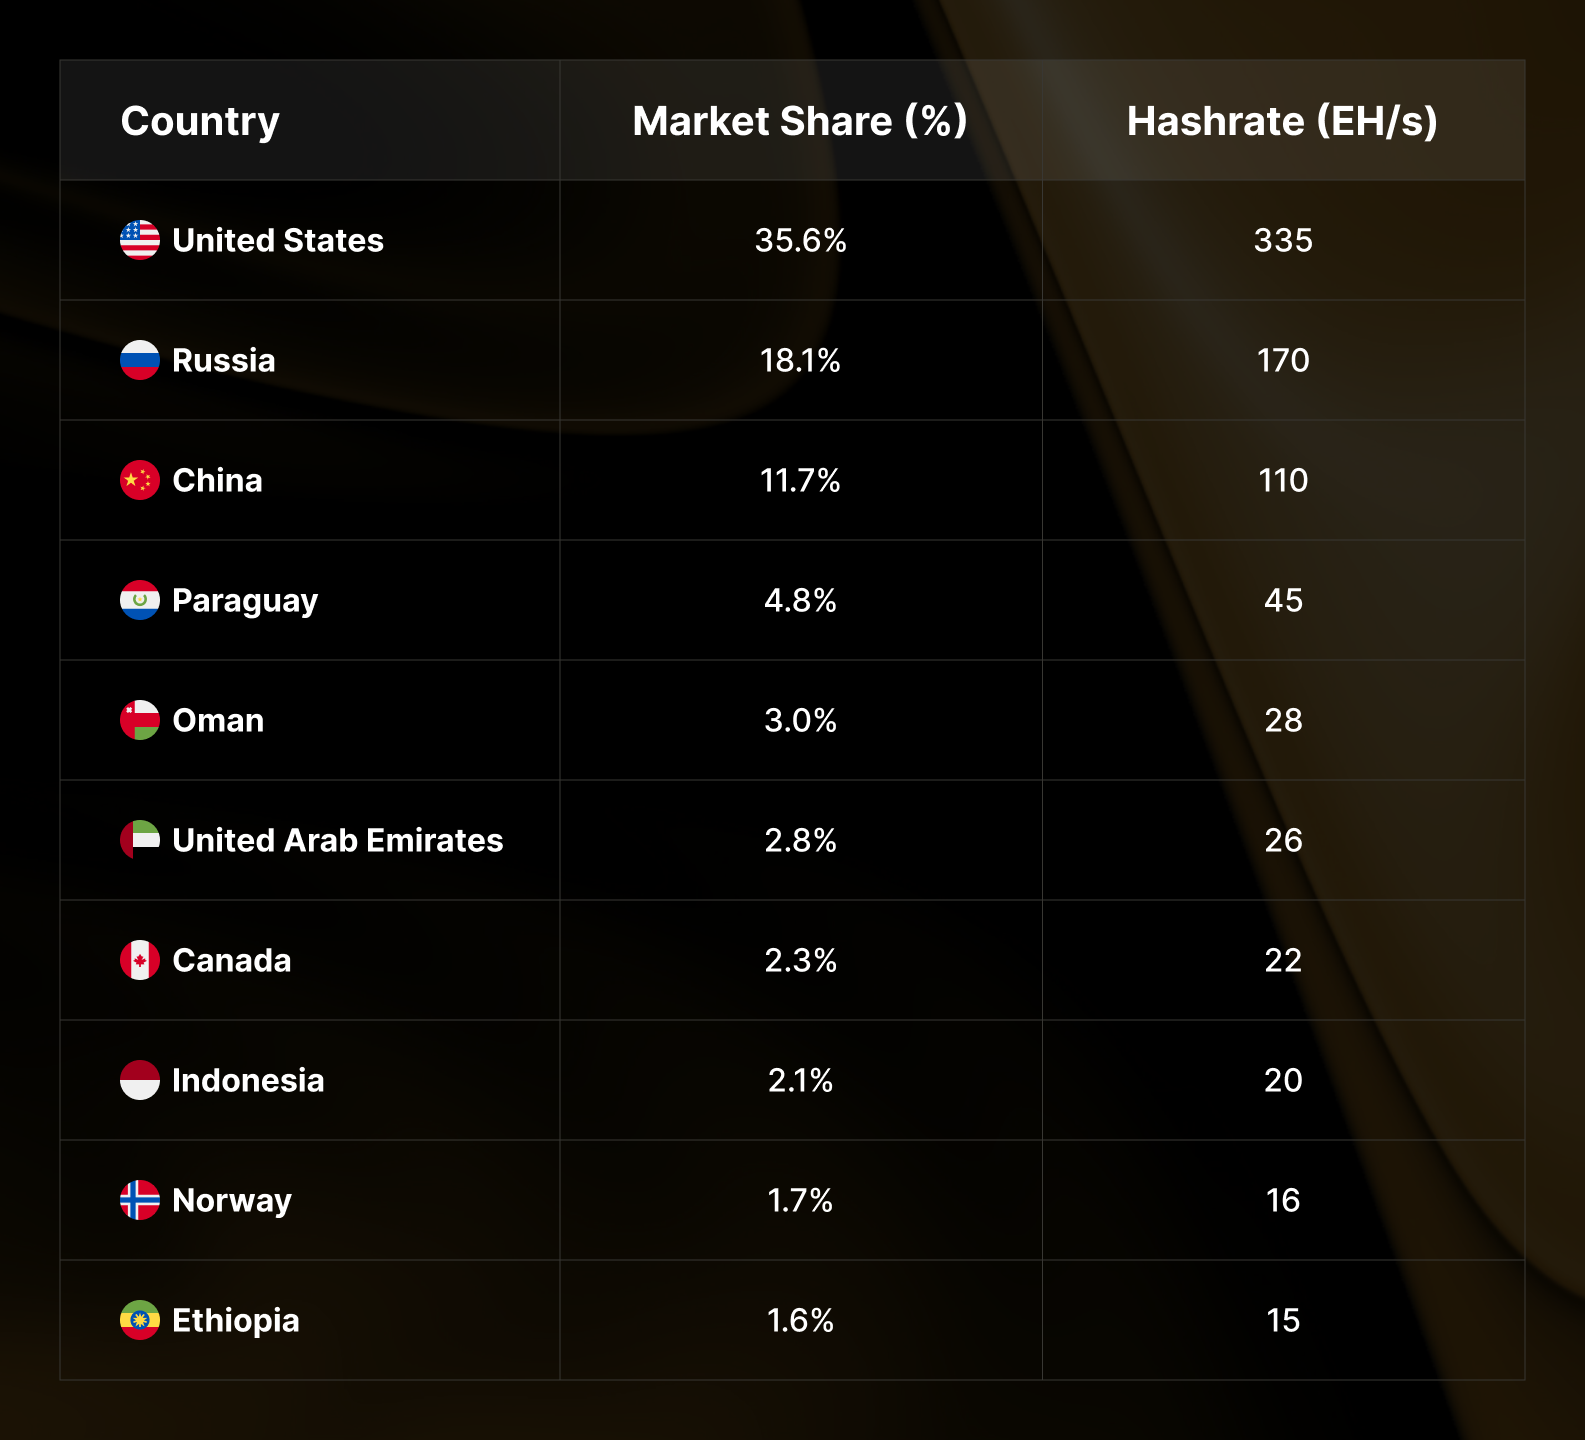
Bitcoin mining remains a heavily concentrated industry, with the top three nations continuing to command roughly two-thirds of the global hashrate. However, the exact hierarchy within the top tier and the broader top ten experienced notable shuffling during the quarter.
While the roster of the top ten countries remained identical to Q3, five of the positions changed hands. Oman successfully surpassed the United Arab Emirates to claim the fifth spot globally. Indonesia climbed from ninth to eighth on the back of a genuine 3 EH/s gain, while Ethiopia slid from eighth down to tenth place. Kazakhstan maintained its position at eleventh with approximately 15 EH/s for the second consecutive quarter, placing it in a virtual dead heat with Ethiopia for the final top-ten slot heading into the first quarter of 2027.
Meanwhile, concentration among the top three countries slipped slightly from 66.2 percent to 65.4 percent, marking the second consecutive quarterly decline in top-tier dominance. Data indicates that the United States is relinquishing its market share at a pace faster than Russia is able to absorb it.
Quarter-over-Quarter Movers and Structural Shifts
When comparing Q4 2026 to Q3 2026, the global map split cleanly into two distinct narratives: a shrinking developed core and an accelerating frontier.
The most notable decliners were led by traditional Western and developed mining hubs facing rising energy costs or competing industrial priorities. Conversely, the gainers were no longer mere statistical rounding errors. Pakistan recorded an absolute addition of 5.5 EH/s, marking the largest single-quarter expansion in its history. Similarly, Venezuela added roughly 4 EH/s, elevating its domestic market to approximately 10 EH/s and placing it ahead of established mid-tier jurisdictions such as Laos, Finland, and Malaysia.
An analysis of year-over-year trends strips away quarterly noise to highlight durable long-term trajectories. Every market that registered annual growth represents a story centered on low-cost or stranded energy supplies.
However, the declining markets do not form a simple mirror image of that dynamic. Countries like Canada and the United Arab Emirates are not prohibitively expensive locations for industrial power. Canadian hashrate relies heavily on hydroelectric generation in Quebec, Manitoba, and British Columbia, while Abu Dhabi’s energy grid is supported by natural gas, solar, and nuclear supply. These jurisdictions did not lose hashrate because electricity prices spiked; rather, they lost compute capacity because the available energy found more lucrative economic applications.
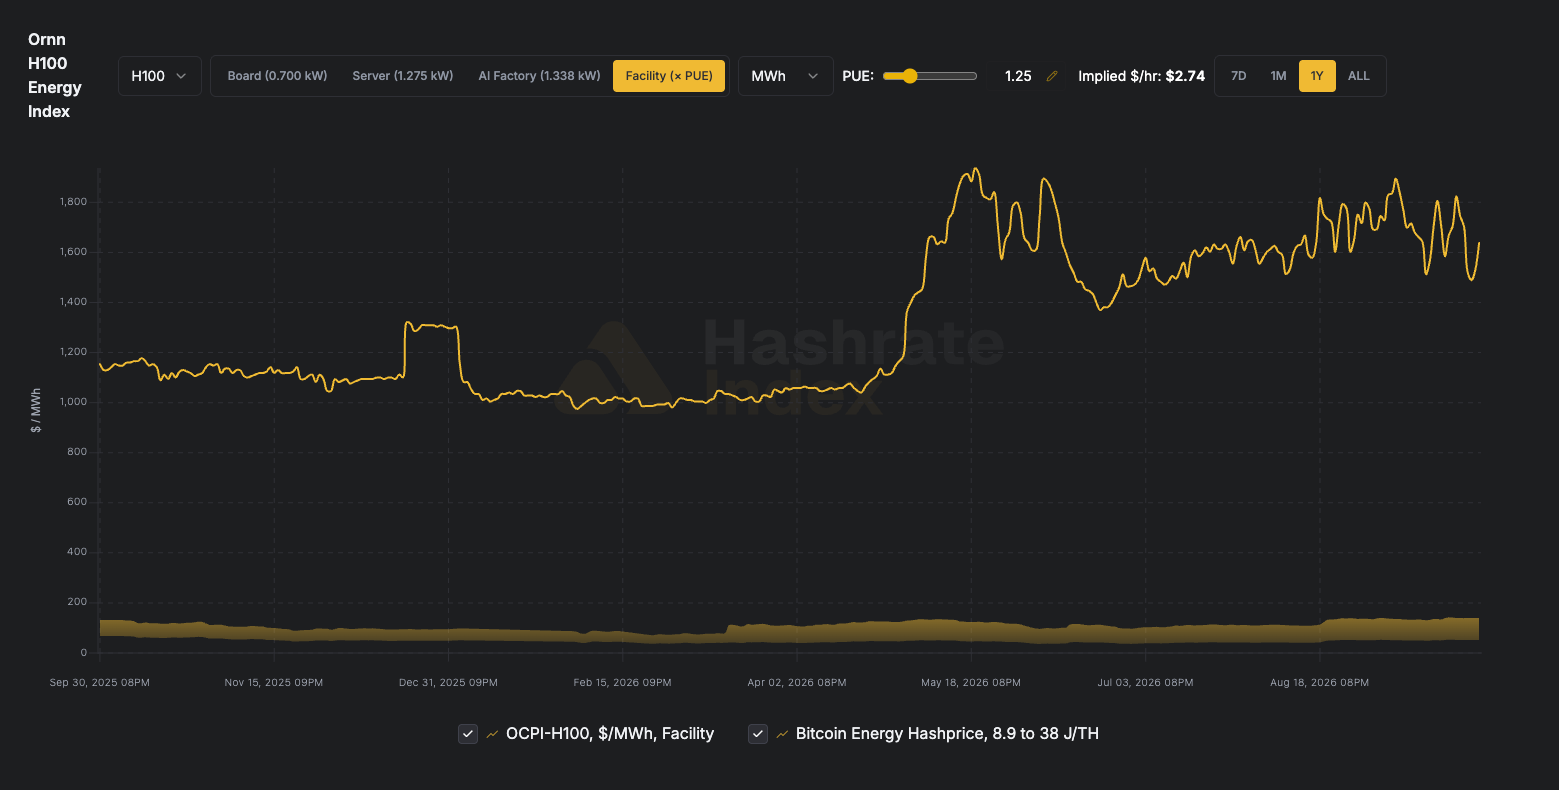
Both Canada and the UAE host sophisticated mining operators that are well-advanced in the pivot toward artificial intelligence and high-performance computing that dominated industrial trends throughout 2026. The economic disparity between the two sectors remains stark: AI and high-performance computing workloads generate anywhere from $1,500 to $3,500 per megawatt-hour, compared to a range of $50 to $150 for traditional Bitcoin mining.
This distinction carries profound implications for the future of the network. A marginal mining machine that goes offline due to a temporary drop in hashprice can easily be switched back on if market conditions improve. By contrast, power capacity committed to a multi-year AI tenant cannot be readily reclaimed, even if the price of Bitcoin rallies and network difficulty recedes. Consequently, the global decliners are splitting into distinct categories: capacity converting directly to AI infrastructure in the United States, Canada, and the UAE; ongoing regulatory pressures in jurisdictions like Kazakhstan, China, and Iran; and macroeconomic instability in countries such as Argentina.
Standouts and the Ethiopian Energy Crunch
Among the markets successfully expanding through the down-cycle, Paraguay continues to serve as a primary anchor. The nation added another 1 EH/s to reach approximately 45 EH/s, securing the fourth position globally and representing a 12 percent year-over-year increase anchored by the Itaipú hydroelectric dam. Indonesia emerged as the quarter’s clearest structural gainer, operating at around 20 EH/s with an 18 percent annual gain, driven by Southeast Asian hydro diversification. Meanwhile, Norway held steady at approximately 16 EH/s for the fourth consecutive quarter.
The most dramatic reversal of the period, however, occurred in Ethiopia. The country’s hashrate plunged from roughly 23 EH/s down to 15 EH/s, marking a 35 percent quarterly decline that pushed it from eighth to tenth place globally and returned its output to mid-2025 levels. Measured from its peak of 27.5 EH/s in the first quarter of 2026, the Ethiopian market has contracted by 45 percent in just three quarters.
This sudden contraction was not driven by regulatory policy shifts, but rather by environmental constraints. On September 15, Ethiopian Electric Power drastically curtailed electricity supplies to Bitcoin miners, cutting deliveries to roughly 23 percent of contracted volume—a reduction of approximately 75 percent. The cuts were implemented after reservoir water inflows fell by roughly 20 percent due to severe, El Niño-driven dry conditions.
Ethiopian operations proved unusually vulnerable to these climate shocks due to their heavy reliance on a single hydroelectric source, the Great Ethiopian Renaissance Dam, and the concentration of large-scale industrial loads on the national grid. Industry analysts warn that Ethiopian hashrate is likely to face further downward pressure into early 2027 unless seasonal water inflows recover significantly.
The Resurgence of Frontier Markets
As traditional hubs contract or pivot toward artificial intelligence, frontier mining markets have stepped in to absorb displaced hardware.
Pakistan experienced a dramatic expansion, surging from roughly 2.5 EH/s to 8 EH/s. This performance far exceeds the country’s previous peak of 4 EH/s earlier in the year, placing it on par with Bhutan and ahead of Finland and Malaysia.
Simultaneously, Venezuela crossed the double-digit threshold at approximately 10 EH/s, representing a 122 percent year-over-year increase. This growth occurred despite a blanket state prohibition on commercial cryptocurrency mining that has remained in force since mid-2024. Industry analyses of geolocated network traffic suggest that the surviving operations are predominantly informal or semi-legitimate rather than state-operated.
In the Middle East, Iran registered a modest uptick for the first time since regional tensions escalated with the United States in early 2026, edging upward from 2 EH/s to 3 EH/s.
Regional Dynamics Across the Globe
In North America, the United States remains the dominant global player with a 35.6 percent market share, yet it recorded its third consecutive quarterly decline, falling to approximately 335 EH/s—a 14 percent decrease year-over-year from its peak of roughly 400 EH/s in Q1 2026. Canada continued its downward trajectory to 22 EH/s, marking a 27 percent annual decline, the steepest drop among developed economies.
Across Europe and Central Asia, Russia established itself as the quarter’s largest absolute gainer, adding 8 EH/s to reach 170 EH/s and capturing an 18.1 percent global share. Kazakhstan successfully stabilized around 15 EH/s following a protracted period of losses, while Norway and Georgia held firm at 16 EH/s and 11 EH/s, respectively.
In the Asia-Pacific region, China’s domestic mining footprint continued its steady multi-quarter erosion, easing down to approximately 110 EH/s, a 24 percent year-over-year decline. Regional diversification efforts continued to benefit Southeast Asian neighbors, with Indonesia reaching 20 EH/s and Malaysia rising to 7 EH/s, while Laos expanded by 1 EH/s to hit 9 EH/s.
Within the Middle East, Oman’s expansion to 28 EH/s allowed it to edge past the United Arab Emirates, which retreated to 26 EH/s amid domestic infrastructure prioritization shifts.
In Latin America, Paraguay maintained its strong leadership position at 45 EH/s, while Bolivia recorded steady growth to reach 4 EH/s. Conversely, Argentina saw its domestic hashrate contract further to 3 EH/s due to persistent macroeconomic challenges.
Finally, the African continent experienced a sharp contraction as Ethiopia’s 35 percent quarterly drop dragged overall regional output down, leaving no other local markets large enough to offset the sudden deficit.
 Cryptocurrency Mining
 Cryptocurrency Mining
 Cryptocurrency Mining







