
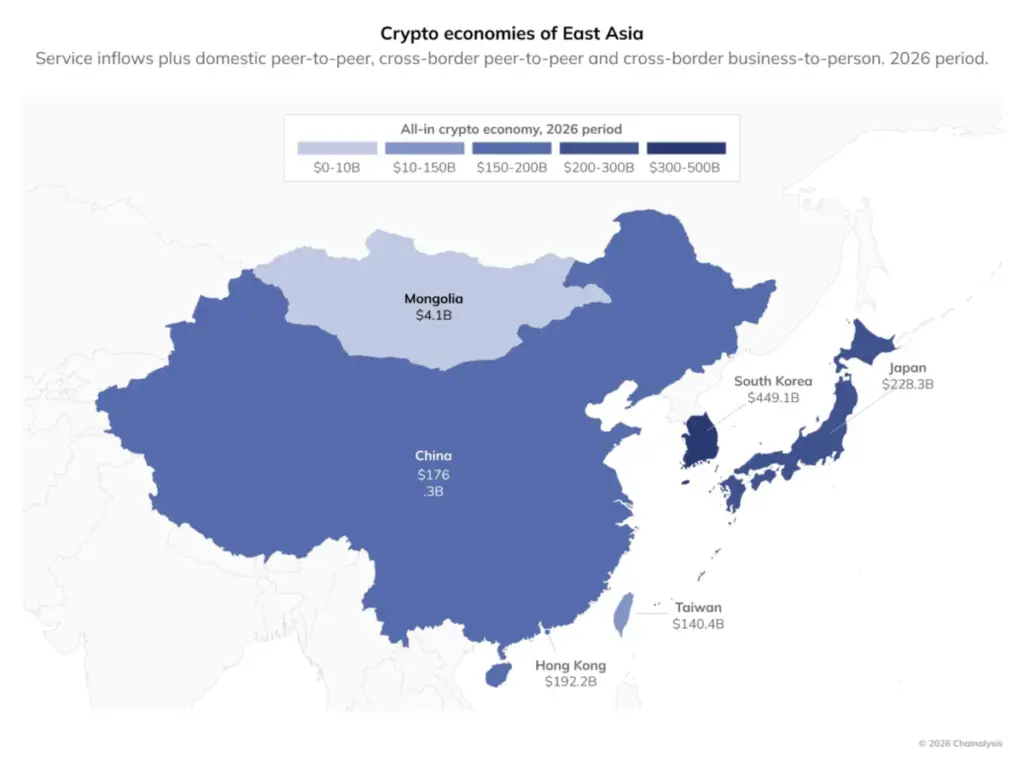
Eastern Asia’s cryptocurrency economy stands as one of the most diverse and economically significant financial ecosystems in the world. Across the region, wholly distinct regulatory environments, risk appetites, and business objectives drive users toward drastically different use cases. While the broader regional crypto economy contracted modestly between July 2025 and June 2026, aligning with a global bear market, this decline was far from uniform. Beneath the surface of regional contraction lies a complex story of growth hubs, regulatory experimentation, and grassroots financial behavior. Institutional platforms in Hong Kong experienced a surge of incoming capital, receiving 87% more than the previous year to mark the fastest institutional growth in East Asia, while Japanese users increasingly migrated to decentralized exchanges, pushing inflows on DEXs up by 36%.
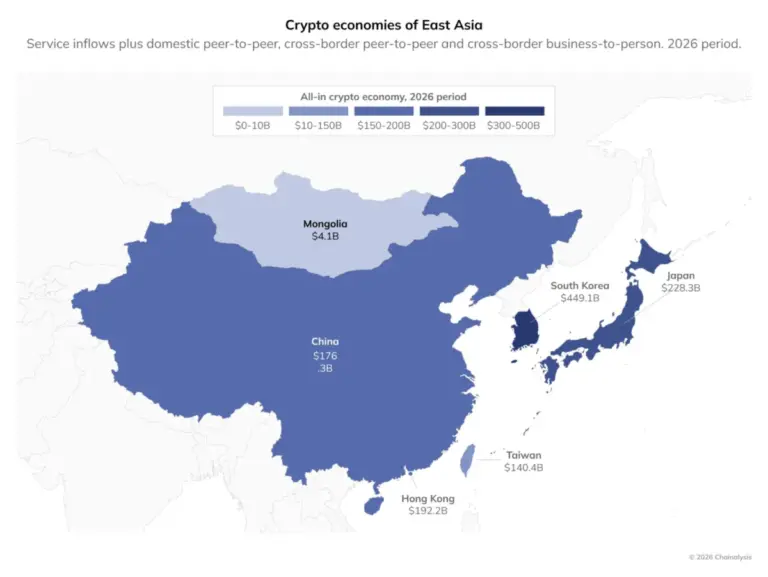
These localized shifts highlight the stark contrasts within the region. Regional leader South Korea maintained a massive $449 billion crypto economy during the 2026 period, growing 12.3% period-over-period. This expansion was powered by a 16.3% growth in the domestic exchange ecosystem and a remarkable retail-driven pivot toward buying and selling artificial intelligence-linked crypto assets. Meanwhile, other jurisdictions carved out entirely different niches, balancing institutional compliance with alternative financial channels. As Daniel Kim, CEO of Tiger Research, noted, Asia remains a rare region possessing both deep grassroots retail participation and substantial institutional firepower.
South Korea Leads the Region as Retail Traders Embrace High-Risk Opportunities
South Korea’s $449 billion all-in crypto economy, supported by an additional $51.1 billion in exchange-related flows, cements its status as the region’s largest digital asset market. Much of this sustained growth is attributable to the country’s famously retail-driven market dynamics, according to Francis Kang, executive director of Korea Blockchain Week. This retail enthusiasm has increasingly aligned with broader macroeconomic trends, most notably the global "AI trade."

Significantly, this growth occurred largely without the immediate, large-scale entry of major traditional financial institutions. Legislative roadblocks and conservative corporate governance have historically slowed institutional adoption for payments and investments. Although the South Korean government began easing a longstanding ban on corporate crypto trading in February 2026, local experts describe institutional engagement as being in a "preparatory mode." Every major bank and securities firm in the country now maintains a digital asset team, running pilots in stablecoins, tokenization, and custody, but scaled corporate participation remains on the horizon.
One major catalyst for South Korea’s retail dominance has been the absence of crypto taxes throughout the 2026 period. Although a long-delayed 22% tax on crypto profits is officially scheduled to take effect at the start of 2027, the National Assembly has postponed the implementation before and could potentially do so again. This looming tax deadline coincides with the gradual arrival of institutional participation. In February 2025, the Financial Services Commission announced a regulatory roadmap opening the market to nonprofits, exchanges, listed companies, and registered professional investment corporations, even if investment-driven corporate participation has yet to scale fully in practice.
If the capital gains tax takes effect on schedule while corporate access simultaneously broadens, 2027 could introduce a radically transformed Korean market where retail activity faces headwinds and institutions emerge as a meaningful counterweight for the first time. Jinhyeong Jo, a senior examiner at Korea’s Financial Intelligence Unit, emphasized that the outcome of ongoing National Assembly discussions will have a profound impact on retail investor demand and overall market participation.

The AI Cryptocurrency Trade Dominates South Korean Order Books
South Korea’s retail market has consistently favored high-risk, high-reward opportunities, a tendency most prominently displayed in the unprecedented popularity of AI-themed cryptocurrencies. The country’s mainstream equity market is heavily anchored by SK Hynix, a dominant global manufacturer of the high-performance memory chips powering the international data center and artificial intelligence boom.
Mirroring the ascent of SK Hynix in traditional equities, AI-crypto trading grew exponentially in South Korea. By June 2026, digital assets tied to AI-focused projects or supporting infrastructure became the single most popular thematically defined investment category measured by won-denominated trading volume, eclipsing traditional favorites like payment tokens such as XRP.
This hyper-concentration makes South Korea a global outlier. By comparison, Japanese yen trading of AI-crypto assets reached a mere 0.91% in June 2026, making South Korean won-denominated activity roughly 19.5 times higher than the Japanese rate. Won-denominated AI volumes also dwarf figures from other major global currencies, such as the Brazilian Real at 0.20%, the British Pound at 0.03%, and the Euro at 1.02%.

Traders in South Korea actively cycled through a wide assortment of AI tokens during the period. Worldcoin (WLD) led the category with $7.41 billion in trading volume, supported by newcomer token SAHARA with $3.2 billion, VIRTUAL with $2.7 billion, BIO with $2 billion, and NEAR with $1.7 billion. Furthermore, the specific tokens driving this volume turned over rapidly, with 2025 leaders giving way to newer projects by mid-2026, demonstrating that Korean retail traders navigate this specialized asset category with unmatched speed and intensity.
Japan Balances Institutional Ambition with a Resilient Consumer Base
Japan’s $228 billion crypto economy frequently draws international attention for its accelerating institutional activity. Unlike peer markets driven primarily by everyday consumers, the core driving force in the world’s fourth-largest economy by GDP is increasingly rooted in commercial banks and major financial services firms. Experts following Japan’s digital asset sector note that the most consequential developments are taking place within regulated institutional perimeters.
Nevertheless, Japan’s population of 122 million continues to maintain a substantial consumer crypto footprint. On-chain data from the 2026 study period revealed that roughly one in four individuals who withdraw funds from domestic Japanese exchanges subsequently deposit them into decentralized finance (DeFi) protocols. Furthermore, decentralized exchanges captured nearly 35% of Japan’s services industry market share, representing a higher proportion than any other market in the region. Japanese engagement with DEXs has expanded by more than 200% since 2022, while centralized exchange activity has remained comparatively flat, challenging the assumption that Japan’s consumer sector is inactive.

Much of this consumer-facing decentralized activity revolves around advanced trading instruments. Taishi Sato, CEO of DeFimans and an SBI subsidiary, pointed out that visible retail activity is heavily concentrated in perpetual futures. He attributes the popularity of perps in Japan to a sophisticated retail trader population already well-versed in foreign exchange markets, equipping currency traders with the hedging language necessary to navigate decentralized derivatives. Traders frequently utilize platforms like Hyperliquid alongside traditional equity portfolios to manage directional and macroeconomic exposure rather than treating them purely as crypto-native venues.
Regarding direct token investments, store-of-value assets such as Bitcoin remained the most popular category, commanding a 73.8% share of yen trading volume. However, store-of-value assets saw their overall market share slip by 4.32 percentage points amid a 27% contraction in total volume. Conversely, smart contract tokens like Ethereum and Solana emerged as the primary gainers, growing their share from 10% in the 2025 period to 15.4% by the end of the 2026 period following a 17.7% increase in absolute trading volume.
Arisa Toyosaki, general manager of Binance Japan, observed that while Japan possesses a large and active retail crypto base, growth has historically been constrained by punitive tax treatments and a conservative investment culture. Through the 2026 period, crypto traders faced a maximum marginal tax rate of 55%. However, a series of tax reforms advanced in July 2026—anticipated to lower eligible gains to a separate taxation rate of roughly 20%—may significantly ease financial friction and catalyze consumer and retail participation heading into 2027.

On the institutional front, Japanese financial institutions are increasingly recognizing digital assets as a legitimate new business line. Yuya Hasegawa, a market analyst at Bitbank, noted that Japanese banks, brokers, and payment companies are currently focused on building foundational business units rather than operating at massive scale. Industry experts are closely monitoring the introduction of locally tailored financial instruments, such as yen-denominated stablecoins. The first domestic stablecoin, JPYC, launched in October 2025 for international remittances, followed closely by the SBI Group’s JPYSC in June 2026 for over-the-counter trading, real-world asset settlement, and foreign exchange.
Hong Kong Emerges as Eastern Asia’s Premier Institutional Hub
Hong Kong’s $192 billion crypto economy is defined less by its sheer trading volume and more by the institutional profile of its participants. Deliberate government policy has placed digital assets at the core of the city’s broader financial strategy, with regulatory clarity serving as the primary driver of market participation. SB Seker, head of APAC at Binance, emphasized that Hong Kong’s recent evolution demonstrates how regulatory clarity and financial innovation can successfully advance in parallel.
The city’s first Five-Year Plan and its latest Policy Address explicitly identify stablecoins, tokenized finance, and central bank digital currencies as strategic priorities. Having issued its initial stablecoin licenses in 2026, Hong Kong has steadily advanced into live market testing with institutional partners. According to QCP Group, this regulatory direction favors larger, well-controlled, and properly licensed operators, raising operational standards for smaller firms while reinforcing overall market credibility.

This structured regulatory framework has successfully attracted institutional capital. Institutional platforms, encompassing over-the-counter desks, custody providers, and market makers, captured 16% of Hong Kong’s service inflows during the 2026 period, up from approximately 9% two years prior. No other Eastern Asian market exceeds a 6% institutional share. Hong Kong pulled in nearly $24 billion in inbound business-to-business crypto transfers, marking a volume roughly six times larger than Japan and 44 times that of South Korea. Outbound institutional flows remained similarly substantial at approximately $11 billion, illustrating Hong Kong’s function as a vital two-way corridor for capital moving across Asia.
Cumulative net B2B inflows climbed steadily from mid-2022 onward to reach $17.4 billion by mid-2026, proving that institutional capital has entered Hong Kong through licensed services at an accelerating rate. Conversely, non-B2B channels ran consistently negative on a net basis, indicating that wallet-based retail flows left the city while institutional capital arrived. Rather than merely passing through, institutional funds are settling within Hong Kong’s regulated legal perimeter, a positioning achieved at the expense of unregulated peer-to-peer activity.
China’s Stablecoin Use Surges Amid Social Credit Expansion
China’s cryptocurrency economy remains uniquely challenging to quantify due to the government’s longstanding, official ban on domestic crypto services, which suppresses formal exchange flows. Nevertheless, a substantial underground crypto economy persists, estimated at a minimum of $176 billion during the 2026 period, with true economic activity likely significantly higher.

Unlike most regional and global markets, the vast majority of China’s crypto activity is driven by peer-to-peer transactions rather than centralized exchange inflows and outflows. China’s domestic P2P economy accounted for 59.1% of its all-in crypto volume in the 2026 period, representing a 3.5-fold increase in share compared to the previous timeframe.
A primary catalyst for this dramatic expansion in P2P trading appears linked to China’s expanding social credit system. In March 2025, state officials broadened the application of the social credit system into finance and internet infrastructure. The system, which utilizes behavioral scoring and blacklists to restrict citizen access to travel, credit, employment, and commercial services, has steadily integrated with domestic banking compliance networks.
On-chain metrics reveal a distinct shift in the adoption rate of stablecoins for domestic payments starting around March 2025. Following slight negative monthly fluctuations in January and February, month-over-month activity turned decisively positive and sustained a dramatic upward trajectory for 13 consecutive months. Monthly additions grew from approximately $240 million in March 2025 to nearly $5 billion a year later, pointing toward a systemic behavioral change rather than a temporary spike.

This rapid adoption of stablecoins for domestic P2P payments aligns with two primary hypotheses. First, individuals blacklisted by the social credit system who lose access to traditional banking rails frequently turn to decentralized alternatives for censorship resistance. Second, citizens seeking to avoid triggering automated financial surveillance mechanisms increasingly choose to settle commercial transactions via crypto—such as advertising goods on e-commerce platforms and completing payments through shared digital wallets. Data indicates that transaction volumes in smaller monetary brackets—under $100, $100 to $1,000, and $1,000 to $10,000—experienced exponential growth surges following March 2025.
An analysis of monetary velocity further illuminates the functional nature of China’s stablecoin market. Economists define velocity as the turnover rate of currency units within a specific timeframe, where high velocity implies that funds circulate rapidly among active economic participants. China’s self-custodied stablecoin holdings turned over at an extraordinary rate of 33.2 times per year during the 2026 period. This turnover rate is more than three times the global average of 9.3 times, and drastically outpaces regional peers such as Japan at 9.9 times, Hong Kong at 6.1 times, and South Korea at 5.1 times. Moving $104.1 billion across 18.1 million individual transfers on an average holding base of $3.1 billion, Chinese users predominantly treat stablecoins as active working capital rather than long-term stores of value, mirroring the behavioral patterns expected of a functional domestic payment network.
Regulation Shapes the Future of Eastern Asia
As the regional market evolves, industry observers note a fundamental structural transition. Daniel Kim of Tiger Research observed that the center of gravity in a market historically dominated by retail traders is systematically shifting toward institutional entities, driven almost entirely by regulatory intervention.

Eastern Asia provides a clear empirical test of how differing regulatory philosophies impact digital asset markets. While China’s prohibition led activity to migrate into underground channels—evidenced by unique wallets sending stablecoin P2P transactions multiplying 43-fold in two years—jurisdictions like Japan, Hong Kong, Singapore, and South Korea pursued supervised-access frameworks designed to enclose activity within licensed perimeters. The resulting outcomes vary considerably, from Hong Kong capturing billions in net institutional inflows to South Korea maintaining a vibrant, retail-led expansion.
As regulatory bodies continue to refine their oversight, the core question facing the region is whether supervised access successfully channels all market activity into compliance across institutional, retail, and cross-border sectors, or if certain types of financial activity will continue seeking offshore alternatives. Upcoming market data will provide further clarity on the long-term trajectory of Eastern Asia’s multifaceted crypto economy.
 Crypto Wallets & Security
 Crypto Wallets & Security
 Crypto Wallets & Security







